
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| India Bag in Box Market Size 2023 | USD 115.46 Million |
| India Bag in Box Market, CAGR | 10.66% |
| India Bag in Box Market Size 2032 | USD 307.73 Million |
Market Overview
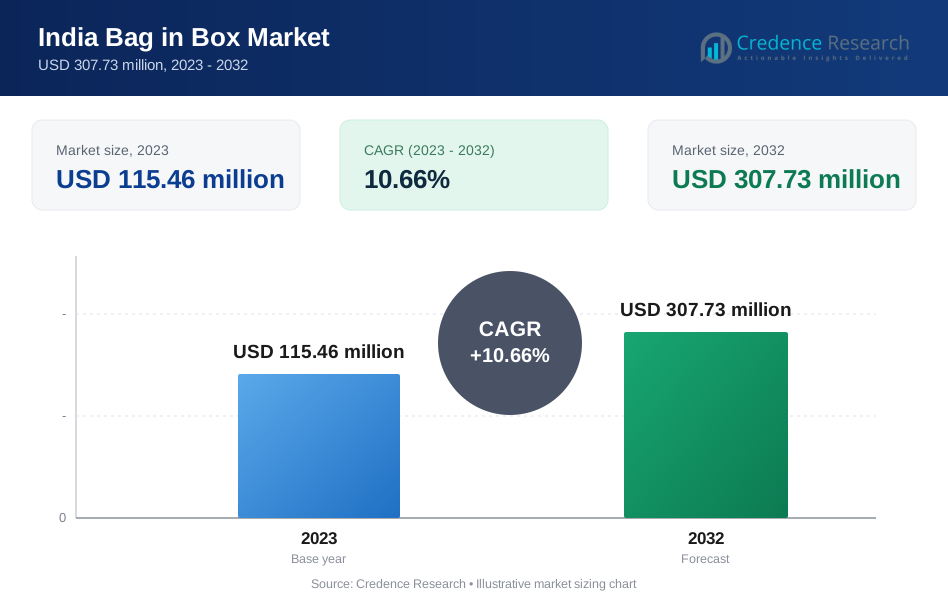
The India Bag in Box Market is projected to grow from USD 115.46 million in 2023 to an estimated USD 307.73 million by 2032, with a compound annual growth rate (CAGR) of 10.66% from 2024 to 2032. This growth is attributed to the increasing demand for convenient, eco-friendly, and cost-effective packaging solutions across various industries such as beverages, dairy products, and liquids.
Key drivers of the Bag in Box market include the rising preference for sustainable packaging solutions, growing demand in the beverage industry, and the cost-efficiency of Bag in Box technology. The trend toward eco-friendly packaging, along with the increased demand for liquid food products and convenience, is expected to propel the market. Moreover, innovations in Bag in Box designs and materials, such as better barrier properties and user-friendly spout features, are expected to boost the market's appeal.
Geographically, the India Bag in Box Market is gaining traction in major metropolitan regions and expanding rapidly across tier 2 and tier 3 cities. The rising awareness of sustainable packaging in India is contributing to this growth, along with the increasing demand for liquid products. Key players in the market include Smurfit Kappa, Liqui-Box Corporation, Mondi Group, and DS Smith, which continue to innovate and meet the growing demand for efficient, eco-friendly packaging solutions.
Market Drivers
Growing Demand for Sustainable Packaging Solutions
One of the primary drivers behind the growth of the Bag in Box market in India is the increasing demand for sustainable and eco-friendly packaging solutions. Consumers and businesses alike are becoming more aware of environmental concerns, which has led to a significant shift towards greener alternatives. Traditional packaging materials such as plastic and glass are being scrutinized for their environmental impact, including high carbon footprints and non-recyclability. In contrast, Bag in Box packaging offers a more sustainable solution, being made from renewable materials such as paperboard and featuring a smaller carbon footprint. The ability to use less material, along with its recyclability, aligns with the growing trend of sustainability and circular economy practices in India. Furthermore, the growing government regulations encouraging sustainable packaging and waste reduction further contribute to the popularity of Bag in Box solutions. As both consumers and manufacturers seek to reduce their environmental impact, Bag in Box packaging is positioned as a viable and responsible alternative, pushing the market's growth. For instance, the Bag in Box packaging format is increasingly being adopted by the beverage industry due to its ease of handling and extended shelf life. The lightweight and compact design of Bag in Box makes it ideal for transporting large quantities of liquids, such as juices and alcoholic beverages, while maintaining product quality. This packaging solution not only reduces transportation costs but also offers user-friendly dispensing systems, which enhance the overall consumer experience. Additionally, the recyclability of the materials used aligns with growing environmental concerns, further driving its popularity across multiple sectors.
Increase in Demand for Convenience and Cost-Effective Packaging
The Bag in Box packaging format offers significant convenience and cost-effectiveness, which is particularly attractive to both manufacturers and end consumers. Bag in Box packaging allows for easy handling, storage, and transportation due to its lightweight and compact design. This makes it ideal for a wide range of industries, especially for liquid-based products like beverages, dairy, and cooking oils. In addition, the packaging format often provides a more extended shelf life due to the enhanced barrier properties of the materials used. For manufacturers, this results in lower transportation costs, reduced material usage, and less waste. The ease of dispensing liquids from the bag through an attached spout also increases the overall user experience. Consumers, especially in the food and beverage sector, prefer Bag in Box packaging because of its ease of use, lower costs, and ability to store larger quantities of products in a smaller space. As a result, the demand for Bag in Box packaging has risen across various industries, contributing to the market's growth in India.
Expansion of the Beverage and Dairy Industries
The expansion of the beverage and dairy industries in India has been a crucial driver of the Bag in Box market. India is one of the largest producers and consumers of dairy products in the world, with a rapidly growing demand for both liquid dairy products and beverages such as juices, smoothies, and alcoholic drinks. Bag in Box packaging is especially popular in these sectors because it provides an efficient and cost-effective way to transport and store large quantities of liquids. The ease of filling and dispensing liquids from a Bag in Box system makes it ideal for the beverage industry, particularly in large-scale operations and bulk distribution. Additionally, for dairy producers, Bag in Box packaging offers enhanced freshness and shelf life, which is crucial for perishable goods. As India’s middle class continues to expand and consumer purchasing power increases, the demand for packaged beverages and dairy products is also rising, further boosting the need for efficient packaging solutions like Bag in Box. For instance, in the dairy industry, Bag in Box packaging is preferred for its ability to preserve freshness and extend the shelf life of perishable products like milk and yogurt. Its efficient design minimizes waste and supports bulk distribution, making it a cost-effective option for producers.
Technological Innovations and Product Advancements
Technological innovations and advancements in packaging materials and designs have also been instrumental in driving the growth of the Bag in Box market in India. Over the past decade, significant improvements have been made in the materials used in Bag in Box packaging, enhancing their strength, durability, and barrier properties. For instance, the use of advanced films in the inner bag layer, which improves the protection of the product against oxygen and moisture, has enhanced the shelf life of liquids, making Bag in Box packaging even more appealing to food and beverage manufacturers. The spout design, which allows for easier dispensing and reduces waste, has also evolved to become more user-friendly, ensuring a higher level of convenience for consumers. Additionally, customizations in the box design, such as branding opportunities and improved structural integrity, have made Bag in Box packaging more versatile across different industries. These technological advancements continue to enhance the functionality and attractiveness of Bag in Box packaging, ensuring that it remains competitive in the rapidly evolving packaging market.
Market Trends
Rising Popularity in the Wine and Beverage Industry
One of the prominent trends in the India Bag in Box market is the increasing adoption of this packaging format in the wine and beverage industry. As India's wine consumption continues to grow, particularly among the urban and middle-class population, Bag in Box packaging is being increasingly utilized for packaging and distributing wine, juices, and other liquid beverages. This trend is driven by the packaging format's cost-effectiveness, ability to extend product shelf life, and convenience for consumers. The Bag in Box solution provides an ideal packaging choice for the wine industry, where large-scale distribution and bulk sales are common. Furthermore, it supports wine preservation by reducing oxidation, which is crucial for maintaining the quality of the product over time. The beverage industry, in general, benefits from the lightweight and space-efficient design of the Bag in Box, making it easier to transport and store products. For instance, in the wine industry, the Bag in Box format has been increasingly adopted by producers due to its ability to preserve freshness and reduce oxidation, which is critical for maintaining the quality of wine over time. This packaging solution also offers logistical advantages, as it is lighter and more space-efficient compared to traditional glass bottles, making it easier to transport and store. Similarly, beverage manufacturers, including those producing juices and non-alcoholic drinks, are leveraging Bag in Box packaging for its cost-effectiveness and ability to extend shelf life by protecting contents from exposure to air and light. This trend reflects a broader global movement toward more sustainable and cost-efficient packaging solutions in the beverage sector, which is gaining traction in India as well.
Increased Focus on Customization and Branding
Another key trend in the India Bag in Box market is the growing demand for customization and branding opportunities. As consumer preferences shift toward personalized and unique packaging, manufacturers are increasingly focusing on offering customized designs for Bag in Box packaging. This trend is particularly evident in the food and beverage sectors, where companies seek to differentiate their products in a competitive market. Customization in Bag in Box packaging not only offers an avenue for branding but also allows companies to enhance the visual appeal of their products. Innovations such as digitally printed boxes, customized spouts, and distinctive box shapes are becoming more common as brands look for ways to appeal to consumers. In addition to aesthetics, this trend also involves the use of advanced packaging materials that improve the functionality of the box, such as better durability and ease of use. The rise of e-commerce has further accelerated the need for packaging that can stand out both on store shelves and in online marketplaces, making the customization of Bag in Box solutions an important trend in India’s packaging landscape.
Market Restraints and Challenges
High Initial Setup and Production Costs
One of the key challenges faced by the Bag in Box market in India is the relatively high initial setup and production costs. Manufacturing Bag in Box packaging requires specialized equipment, including filling machines, sealing systems, and advanced materials that can increase capital expenditure for businesses. For smaller manufacturers or startups, these upfront costs can be prohibitive, limiting their ability to enter the market or adopt this packaging format. Additionally, while Bag in Box packaging is cost-effective in the long run due to its material efficiency and reduced transportation expenses, the higher initial investment in production processes can slow down the adoption rate, especially in a price-sensitive market like India. The need for customizations and technological advancements, such as specialized films and advanced spout designs, can further increase costs. These financial barriers pose a challenge to widespread market adoption, particularly among smaller and mid-sized businesses that are hesitant to invest in the infrastructure required to produce and handle Bag in Box packaging.
Limited Consumer Awareness and Education
Another significant restraint for the Bag in Box market in India is the limited consumer awareness and education about the benefits and advantages of this packaging format. While Bag in Box has gained traction in certain industries, such as wine, dairy, and beverages, many consumers are still unfamiliar with its uses and benefits compared to traditional packaging formats like bottles and cartons. This lack of awareness results in hesitation among consumers to embrace Bag in Box solutions, particularly for products like juices and oils, where the packaging format may appear unconventional. Additionally, there is still a cultural preference for traditional packaging formats in some sectors, which could further limit the growth of the market. Overcoming this challenge requires increased marketing efforts, education campaigns, and strategic partnerships by manufacturers and retailers to promote the benefits of Bag in Box packaging, such as its environmental advantages, convenience, and cost-effectiveness. Until consumers and businesses are more educated on the advantages, the adoption of Bag in Box packaging could remain limited in certain sectors.
Market Segmentation Analysis
By Component
The India Bag in Box market is segmented based on three key components: bags, boxes, and fitments. Bags serve the primary function of containing liquid or semi-liquid products and are typically made from multi-layered films that offer excellent barrier properties to prevent leakage and maintain product quality. With growing demand for eco-friendly materials, manufacturers are focusing on developing recyclable or biodegradable bags. Boxes provide structural support to the bags, ensuring protection during storage and transportation. Made mainly from cardboard or paperboard, boxes are often customizable for branding and visual appeal, with an increasing demand for lightweight and sustainable options. Fitments, which include spouts or tap mechanisms, allow for easy dispensing of liquids from the bag, with ongoing innovations aimed at improving user convenience and durability, particularly in the food and beverage industries where functionality is crucial.
By Capacity
The capacity segment of the India Bag in Box market is divided into several ranges, including 5 to 10 liters, 10 to 15 liters, 15 to 20 liters, and others. The 5 to 10-liter range is commonly used for beverages such as juices and liquid dairy products, offering convenience for household and small retail use. The 10 to 15-liter range is increasingly popular in the beverage and dairy industries, serving mid-sized consumers and small businesses, often used for bulk packaging of fruit juices and alcoholic drinks like wine. The 15 to 20-liter capacity is typically used in industrial and commercial sectors for products like chemicals, oils, and large-scale beverage packaging. The "Others" category covers specialized packaging needs, often for large-scale industrial or chemical uses that require higher capacities or custom sizes.
Segments
Based on component
- Bags
- Boxes
- Fitments
Based on Capacity
- 5 to 10 liters
- 10 to 15 liters
- 15 to 20 liters
- Others
Based on End use
- Food
- Beverages
- Chemicals
- Industrial
- Others
Based on material state
- Semi-liquid
- Liquid
Based on tap
- With Tap
- Without Tap
Based on region
- North India
- South India
- West India
- East India
Regional Analysis
North India (30%):
North India holds a substantial share of the Bag in Box market, accounting for approximately 30% of the total market. This region includes major urban centers like Delhi, Chandigarh, and Haryana, where the demand for packaged food and beverages is rising due to an expanding middle class and a growing preference for convenience. The beverage sector, particularly juices and alcoholic drinks, has seen a surge in demand for Bag in Box packaging. Furthermore, the dairy industry in North India, one of the largest in the country, is contributing significantly to the market's growth, as Bag in Box packaging is increasingly used for liquid dairy products. Government initiatives promoting eco-friendly packaging solutions also support the growth of this region’s market share.
South India (28%):
South India is another key region, contributing around 28% to the overall Bag in Box market. States like Tamil Nadu, Karnataka, Andhra Pradesh, and Kerala have well-established food and beverage industries, particularly in dairy and liquid food products. The demand for Bag in Box packaging in this region is driven by the thriving beverage industry, including juices and soft drinks, as well as the growing popularity of eco-friendly packaging solutions in urban areas like Bangalore and Chennai. Additionally, the increasing awareness about the environmental benefits of Bag in Box packaging is expected to continue driving market growth in this region.
Key players
- Gerresheimer AG
- ITC Limited
- Westrock India
- Hitech Plast (Hitech Group)
- Jindal Poly Films Limited
- Manjushree Technopack Ltd
- Vikas Ecotech Ltd.
- Liquibox
- THE PACK CORPORATION
- Scholle IPN
Competitive Analysis
The India Bag in Box market is highly competitive, with several key players driving growth and innovation across different sectors. Gerresheimer AG and Liquibox are well-established global leaders, leveraging their advanced technology and extensive product portfolios to cater to a wide range of industries, including beverages, food, and chemicals. ITC Limited and Westrock India stand out due to their strong presence in the packaging industry, particularly within the food and beverage sectors. Hitech Plast and Jindal Poly Films are known for their robust manufacturing capabilities and cost-effective solutions, gaining traction in the mid-range segment of the market. Companies like Manjushree Technopack Ltd and Vikas Ecotech are strengthening their position through regional market penetration and innovations in sustainable packaging. Scholle IPN and THE PACK CORPORATION focus on high-quality products and strategic partnerships, further intensifying market competition. This competitive environment encourages continuous innovation and improvements in packaging designs and materials.
Recent Developments
- In February 2024, Gerresheimer launched a sustainable packaging solution for an innovative deodorant cream by 4peoplewhocare. This packaging includes a glass jar with a bio-based forewood closure, showcasing Gerresheimer’s commitment to environmentally friendly packaging solutions.
- In December 2022, ITC announced its acquisition of Sproutlife Foods Pvt Ltd, the parent company of Yoga Bar, to strengthen its presence in the nutrition and health foods space. This acquisition is part of ITC’s strategy to expand its portfolio in the "Good for You" segment.
- In August 2023, WestRock partnered with Liquibox to develop a Bag-in-Box solution for Amazon’s e-commerce platform. The packaging is designed to minimize overpackaging and reduce transportation costs while being eco-friendly.
- In November 2024, Manjushree Technopack filed draft papers for a Rs 3,000-crore IPO as part of its expansion strategy. The company is also exploring a potential buyout by PAG, which could lead to significant changes in ownership.
- In February 2023, SEE (formerly Sealed Air) completed the acquisition of Liquibox for $1.15 billion. This acquisition enhances SEE’s CRYOVAC brand and accelerates its growth in the sustainable fluids and liquids packaging market.
Market Concentration and Characteristics
The India Bag in Box market exhibits moderate market concentration, with a mix of global players and regional manufacturers competing for market share. Large international companies such as Gerresheimer AG, Liquibox, and Scholle IPN hold significant market positions, leveraging advanced technology and extensive distribution networks to cater to diverse industries like beverages, food, and chemicals. However, local players like ITC Limited, Hitech Plast, and Manjushree Technopack Ltd are also strong contenders, focusing on cost-effective solutions, regional market penetration, and sustainable packaging innovations. The market is characterized by a growing emphasis on eco-friendly packaging, with companies investing in research and development to improve product quality, sustainability, and consumer convenience. While there is intense competition in terms of product offerings, the market remains dynamic, driven by technological advancements, customization, and the increasing demand for efficient and cost-effective packaging solutions.
Report Coverage
The research report offers an in-depth analysis based on Component, Capacity, End use, Material, Tap and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- As environmental concerns continue to rise, there will be a shift towards more sustainable and recyclable packaging solutions, driving the adoption of Bag in Box systems. Eco-conscious consumers and manufacturers will further prioritize sustainable packaging options, increasing demand.
- With the rapid growth of the beverage industry, especially in non-alcoholic drinks like juices, packaged water, and soft drinks, the need for Bag in Box packaging will continue to rise. This growth will drive innovation and expansion in packaging solutions tailored for this sector.
- Ongoing innovations in materials and designs will enhance the performance and functionality of Bag in Box packaging. Advancements such as improved barrier properties and user-friendly dispensing mechanisms will further bolster the market's growth.
- Bag in Box packaging is expected to see increased adoption in the dairy and liquid food sectors due to its ability to prolong shelf life and reduce packaging waste. The growing demand for packaged dairy products will contribute significantly to market expansion.
- As cost reduction becomes a priority for manufacturers, Bag in Box packaging's affordability compared to traditional containers will drive its popularity. Its lower transportation and storage costs make it an attractive solution for large-scale packaging needs.
- The industrial sector, including chemicals and lubricants, will increasingly adopt Bag in Box packaging due to its safe, reliable, and space-efficient features. This trend will extend the market’s reach beyond food and beverage industries.
- The rise of e-commerce will facilitate the demand for efficient and robust packaging, which Bag in Box can easily fulfill. The ability to offer bulk packaging and easy-to-handle solutions will be a key driver in the market's growth in online retail.
- Regulatory frameworks focusing on waste reduction and sustainability will create favorable conditions for the adoption of eco-friendly packaging solutions, including Bag in Box. Government incentives will further encourage businesses to embrace such innovations.
- As the packaging market becomes more competitive, companies will increasingly opt for custom-designed Bag in Box solutions to enhance their branding. Customization will provide a competitive edge, particularly in the food and beverage sectors.
- As consumers become more educated about the benefits of Bag in Box packaging, such as its sustainability and cost-efficiency, acceptance will rise. Increased consumer preference for environmentally friendly products will fuel further market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the India Bag in Box market in 2023 and 2032?
What are the key drivers of the India Bag in Box market?
How does Bag in Box packaging contribute to sustainability?
Which industries are adopting Bag in Box packaging in India?
Who are the key players in the India Bag in Box market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 India Bag in Box Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global India Bag in Box Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 115.46 million → 2032: USD 307.73 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 India Bag in Box Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. India Bag in Box Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 India Bag in Box Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 India Bag in Box Market Drivers
- 3.3 India Bag in Box Market Restraints & Challenges
- 3.4 India Bag in Box Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 India Bag in Box Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 India Bag in Box Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, India Bag in Box category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 India Bag in Box Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. India Bag in Box Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the India Bag in Box market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 India Bag in Box Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 India Bag in Box Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 India Bag in Box Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in India Bag in Box (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New India Bag in Box Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global India Bag in Box Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America India Bag in Box Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe India Bag in Box Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific India Bag in Box Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America India Bag in Box Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East India Bag in Box Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa India Bag in Box Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. India Bag in Box Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
