
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Consumer Appliance Market Size 2024 | USD 48.15 million |
| India Consumer Appliance Market, CAGR | 6.74% |
| India Consumer Appliance Market Size 2032 | USD 81.13 million |
Market Overview
The India Consumer Appliance Market is projected to grow from USD 48.15 million in 2024 to an estimated USD 81.13 million based on 2032, with a compound annual growth rate (CAGR) of 6.74% from 2025 to 2032. Rising household incomes and expanding urbanization fuel adoption of both basic and premium appliances.
Consumers increasingly demand appliances that offer remote monitoring, voice control, and predictive maintenance through IoT integration. Government policies-such as the Bureau of Energy Efficiency’s star rating program-encourage uptake of high-efficiency products. Growth of organized retail and online marketplaces enhances product visibility and streamlines distribution, while digital marketing campaigns and extended warranties bolster brand loyalty. Appliance makers also invest in after-sales networks and localized service centers to improve customer experience and reduce churn.
Regionally, Western and Southern India lead volume sales thanks to higher urban density and robust retail infrastructure, while Northern and Eastern states exhibit accelerating growth as distribution reaches tier-2 and tier-3 cities. Key players including Samsung, LG, Whirlpool, Godrej, and Haier dominate through diversified portfolios and comprehensive service networks. Emerging domestic brands compete on price and localized features, and partnerships with e-commerce platforms help both multinationals and homegrown manufacturers capture incremental demand in underserved markets.
Market Insights
- The India Consumer Appliance Market grows from USD 48.15 million in 2024 to USD 81.13 million by 2032, at a 6.74 % CAGR, highlighting steady expansion.
- Rapid urbanization and rising household incomes drive higher penetration of basic and premium appliances.
- Stringent energy-efficiency norms and the star rating program push manufacturers to innovate and upsell premium models.
- Credit availability and low-interest financing options encourage consumers to upgrade existing appliances.
- High price sensitivity and input cost volatility constrain adoption of top-tier products in cost-conscious segments.
- Western and Southern India dominate sales due to dense urban centers and robust retail infrastructures.
- Tier-2 and tier-3 markets present significant growth opportunities as rural electrification and distribution networks improve.
Report Scope
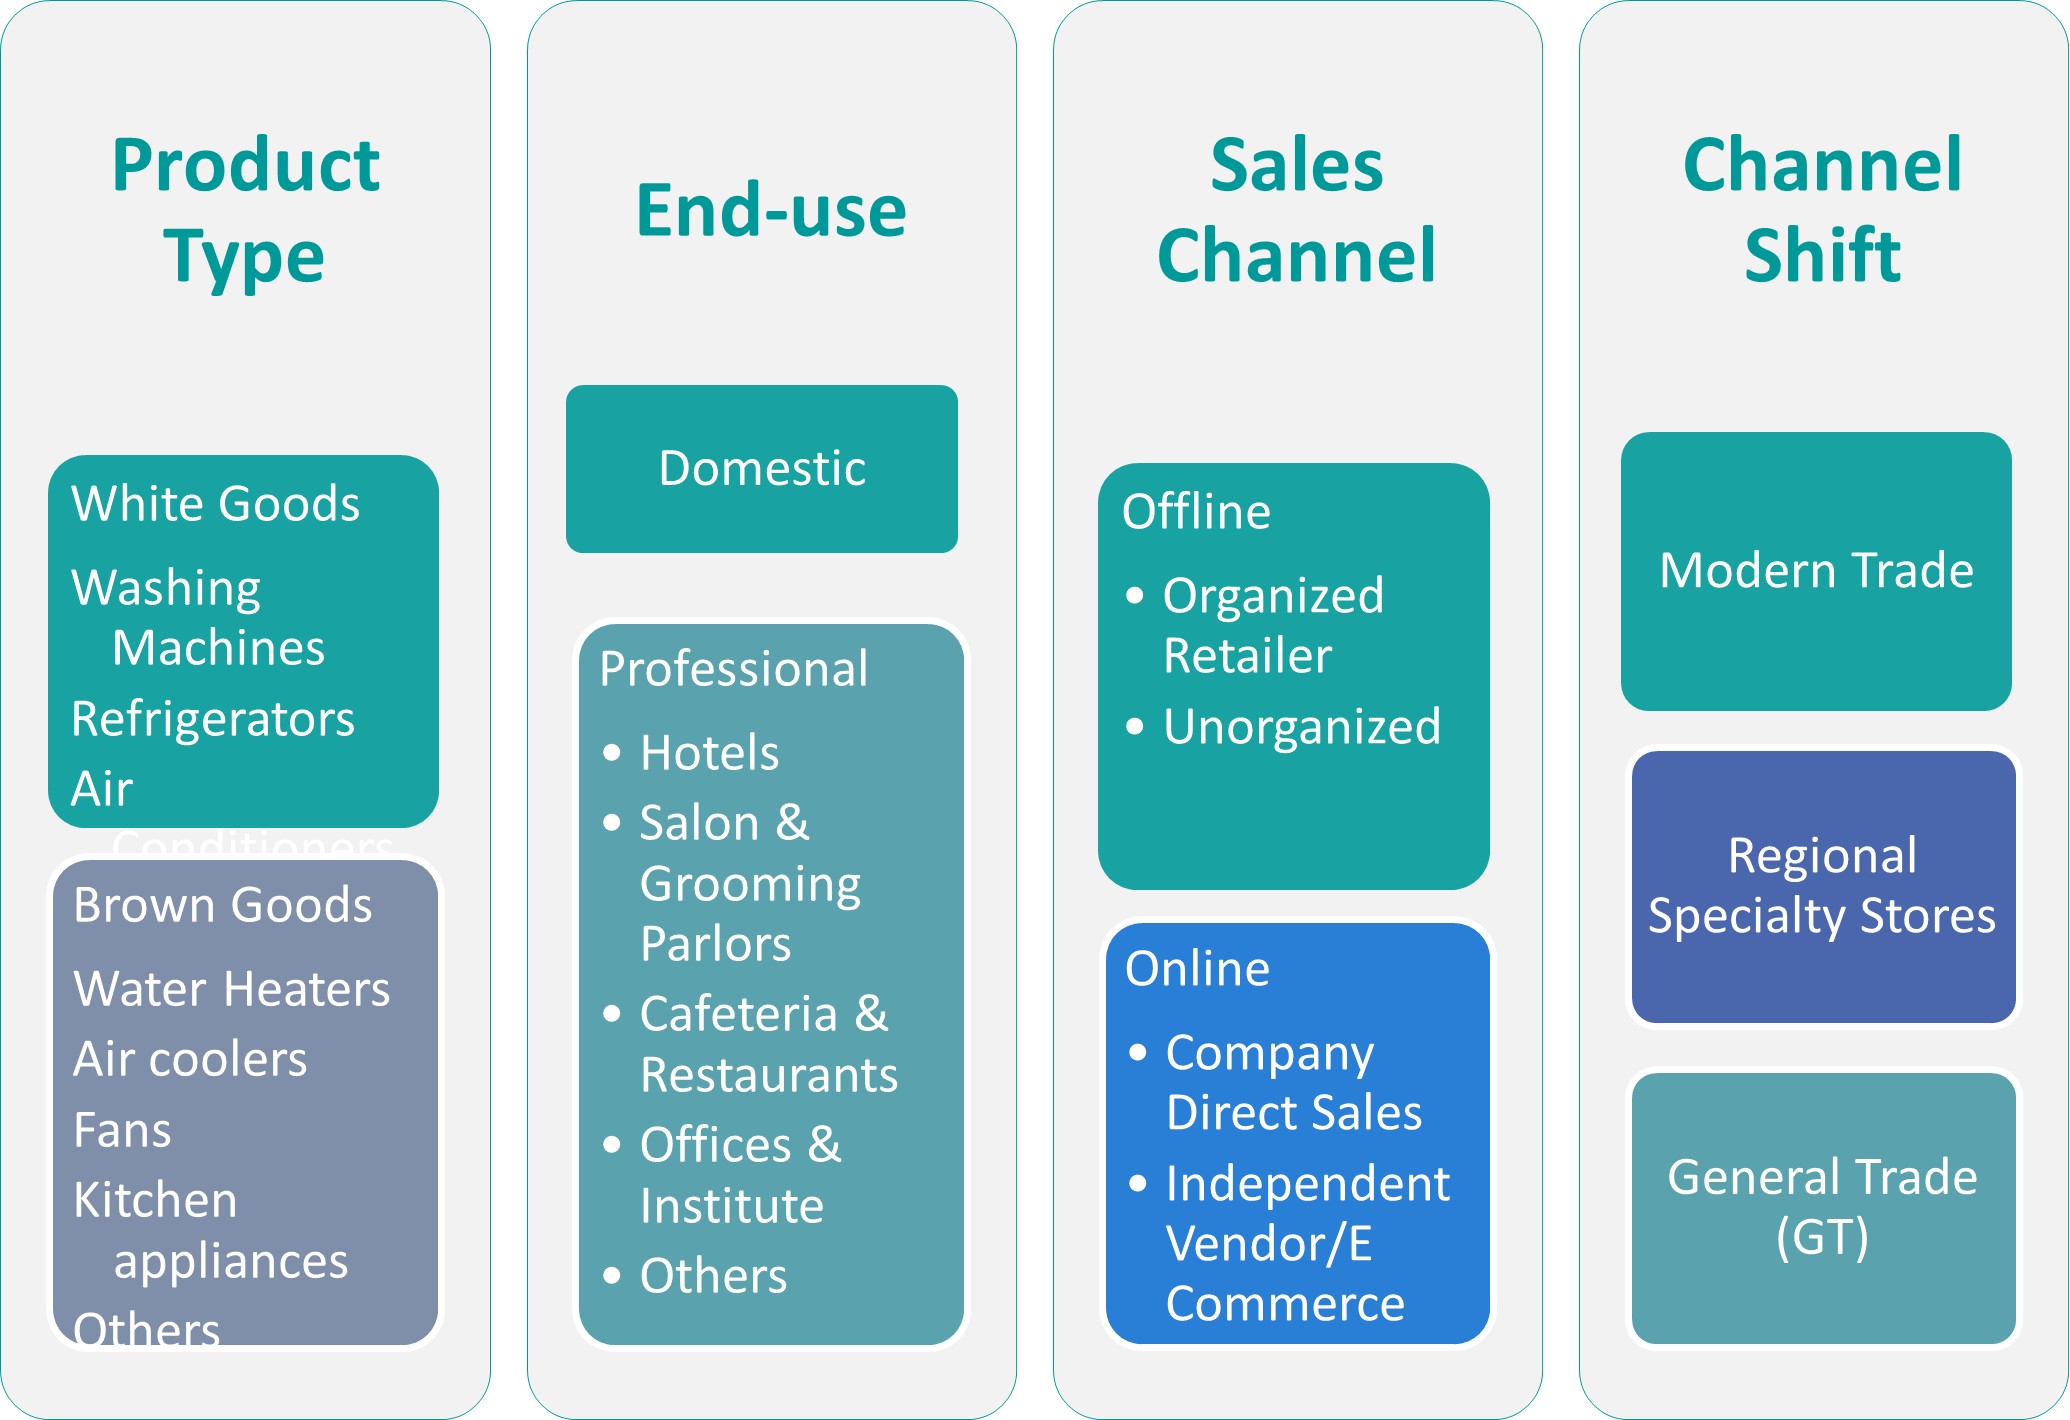
This report segments the India Consumer Appliance Market as follows:
Market Drivers
Strong Economic Growth Boosts Consumer Spending
The India Consumer Appliance Market benefits from sustained GDP expansion and rising household income. Consumers allocate a greater share of budgets to modern appliances. Credit availability and low interest rates support higher-ticket purchases. Younger buyers show interest in premium models that blend style and function. Manufacturers launch new features targeting evolving lifestyle preferences. It drives continuous product innovation to maintain consumer appeal. It rewards brands that align with shifting demand patterns.
- For instance, government surveys indicate that household appliance purchases have increased by over 5 million units annually, driven by rising disposable income and improved financing options
Urbanization and Infrastructure Expansion Expand Market Reach
Rapid migration into cities raises demand for washers, refrigerators, and air conditioners. National electrification programs bring power to remote communities. Improved road networks cut distribution time and lower shipping costs. It enables brands to enter tier-2 and tier-3 towns with confidence. Retail chains expand store count in growing urban corridors. The India Consumer Appliance Market captures new buyers through wider availability.
- For instance, over 2,500 new retail outlets for consumer appliances have opened in tier-2 and tier-3 cities in the past year, reflecting the expansion of urban infrastructure and growing market penetration
Government Energy Efficiency Norms Support Premium Adoption
Government agencies enforce star rating standards on electrical appliances. Consumers prefer models with top ratings to lower monthly power bills. Incentive schemes reduce cost barriers for energy-efficient products. It prompts manufacturers to upgrade compressors and inverter technologies. White goods deliver stronger performance under efficiency mandates. The Ina Consumer Appliance Market shifts toward higher-margin premium segments. It encourages investment in research to exceed regulatory benchmarks.
Digital Retail Channels Enhance Purchase Convenience
Online platforms present detailed product comparisons and customer reviews. Mobile payments and instant financing options simplify checkout. Virtual showrooms let shoppers test features through augmented reality. It reduces dependence on physical outlets and demo centers. E-commerce growth fuels seasonal promotions and flash sales. The India Consumer Appliance Market leverages digital tools to boost sales.
Market Trends
Integration of Smart Home Features Elevates Appliance Functionality
Firms integrate voice assistants and remote-control modules into refrigerators and washing machines. It lets homeowners monitor performance through mobile apps and optimize energy use. Brands partner with tech startups to launch appliances that predict maintenance needs and prevent failures. Surge in 5G rollout supports faster data exchange and higher device reliability. Enhanced connectivity drives consumer demand for unified home ecosystems. The India Consumer Appliance Market embraces these innovations to differentiate products. Tech-driven features command premium pricing and boost profitability.
- For instance, India ranked third globally in the number of smart homes as of 2022, reflecting the rapid adoption of connected appliances and home automation
Sustainability and Eco-Conscious Design Drive Purchasing Decisions
Environment-friendly materials appear in product packaging and internal components. It reduces carbon footprint throughout the supply chain. Manufacturers extend product lifespans through modular architecture and user-serviceable parts. Demand for refrigerators using natural refrigerants with low global warming potential grows rapidly. Government incentive schemes for eco-efficient appliances stimulate uptake. Consumers reward brands that implement circular economy initiatives and take-back programs. The India Consumer Appliance Market benefits from aligning with green commitments.
- For instance, data from the Bureau of Energy Efficiency shows a marked increase in the adoption of energy-efficient appliances across Indian households, supporting sustainability efforts
Market Challenges
High Price Sensitivity Constrains Premium Product Adoption
Consumers in India evaluate appliance features against budget constraints and energy costs. It forces companies to reduce equipment specification or absorb margin pressures. High import duties on advanced components increase retail prices. Intense competition drives frequent discount cycles that erode profitability. Commodity rates and currency fluctuations add input cost volatility. Stakeholders in the India Consumer Appliance Market must innovate cost structures to maintain margins.
- For instance, LG Electronics led the washing machine segment in India in 2022, followed by Samsung, Whirlpool, and Godrej
Uneven Distribution and After-Sales Network Hinder Market Penetration
Brands expand dealer networks in major metros but face gaps in tier-2 and tier-3 coverage. Customers in semi-urban areas experience long wait times for spare parts. It undermines brand reputation and discourages repeat purchases. Unreliable power supply in rural zones disrupts appliance use and increases service calls. Logistics bottlenecks raise delivery lead time in remote districts. Repair technician shortage limits on-site support quality. Service excellence becomes a key challenge for the India Consumer Appliance Market.
Market Opportunities
Rural Electrification and Last-Mile Distribution Present Growth Levers
The India Consumer Appliance Market can leverage government rural electrification plans. Access to untapped villages opens new revenue streams. Brands can deploy compact and multi-purpose appliances tailored to local needs. It allows cost-effective expansion beyond urban centers. Retailers can partner with micro-distributors to overcome infrastructure gaps. Training programs for local technicians reduce service turnaround and build consumer trust. Innovative financing options like micro-credit improve affordability in low-income households.
Smart Appliance Integration with Renewable Energy Systems Drives Differentiation
Manufacturers can integrate solar-ready inverters with refrigerators and fans. It reduces user dependence on unreliable grid power. Smart meters that optimize energy use appeal to eco-aware buyers. The India Consumer Appliance Market benefits when companies launch hybrid products. Pilot studies with remote sensors collect performance data under varied conditions. After-sale software updates maintain device reliability and extend lifecycle. Partnerships with energy service providers enable bundled offerings that boost adoption.
Market Segmentation Analysis
By Product Type
The India Consumer Appliance Market divides into white goods and brown goods. It allocates volume to refrigerators, washing machines, and air conditioners under white goods. Brown goods include televisions, audio systems, and small kitchen devices. Manufacturers optimize product portfolios to match consumer budgets and lifestyle preferences. It balances premium features and affordable solutions.
By End User
The India Consumer Appliance Market segments into domestic and professional buyers. It serves homes through refrigerators and washing machines under domestic. Professional users cover hotels, salons & grooming parlors, cafeterias & restaurants, offices & institutes, and other service sectors. Brands tailor warranty and service packages to meet diverse usage patterns. It adapts product specifications for high-demand environments.
Segments
Based on Product Type
- White Goods
- Brown Goods
Based on End User
- Domestic
- Professional
- Hotels
- Salon & Grooming Parlors
- Cafeteria & Restaurants
- Offices & Institute
- Other
Based on Sales Channel
- Offline
- Organized Retailer
- Unorganized
- Online
- Company Direct Sales
- Independent Vendor/E Commerce
Based on Channel Split
- Modern Trade
- Regional Specialty Stores
- General Trade (GT)
Based on Region
- Eastern India
- Western India
- Southern India
- Northern India
- Central India
Regional Analysis
Northern and Eastern Markets Accelerate Growth
Northern and Eastern regions drive significant demand for household appliances through rising urban incomes and infrastructure upgrades. The India Consumer Appliance Market records strong refrigerator and air conditioner sales in Delhi, Uttar Pradesh, West Bengal, and Bihar. It benefits from growing organized retail chains and expanding distributor networks in these states. Promotional offers and financing options attract first-time buyers and upgraders. Localized marketing campaigns that highlight energy efficiency resonate with cost-conscious consumers. Service centers in metropolitan hubs shorten repair timelines and reinforce brand trust. Manufacturers tailor product features to withstand diverse climatic conditions and voltage fluctuations.
Western and Southern Regions Lead Volume Sales
Western and Southern India represent the largest share of appliance revenues, supported by high urbanization rates and robust retail infrastructure. Mumbai, Pune, Bengaluru, Chennai, and Hyderabad serve as major consumption centers for premium white goods and smart devices. It leverages strong e-commerce penetration and omnichannel retail models to capture tech-savvy buyers. State government incentives for energy-efficient equipment boost sales of star-rated refrigerators and inverter air conditioners. Brands maintain dense after-sales networks to support heavy usage environments. Product launches coincide with regional festivals and shopping events to maximize visibility.
Tier-2 and Tier-3 Cities Present Expansion Opportunities
Tier-2 and Tier-3 towns exhibit faster growth percentages due to improving road connectivity and rural electrification schemes. The India Consumer Appliance Market taps into these areas through partnerships with micro-distributors and local retail associations. It introduces compact, budget-friendly appliances that match smaller living spaces and irregular power supply. Financing solutions with low down payments enhance affordability. Training local technicians ensures reliable maintenance and strengthens customer loyalty. Rural buyers show growing interest in modern conveniences, creating a clear path for incremental sales.
Key players
- Samsung Electronics Co Ltd
- LG Electronics Inc
- Godrej Appliances
- Sony Corporation
- Dell
Competitive Analysis
The India Consumer Appliance Market features intense rivalry between global giants and local champions. It drives rapid product launches and frequent feature updates. Premium brands like Samsung and LG invest in smart home integration to attract tech-savvy buyers while enhancing energy efficiency under regulatory mandates. Domestic players such as Godrej optimize cost structures and customize products for regional preferences. Sony and Dell leverage after-sales networks and bundled service plans to strengthen customer loyalty. It compels vendors to expand digital channels and improve warranty services. Price promotions and tailored financing options intensify competition during peak seasons. Brands develop robust distribution networks and local service centers to ensure fast repair response. Collaborations with e-commerce platforms and energy providers create bundling opportunities that differentiate offerings. It rewards agile companies that align products with shifting consumer priorities.
Recent Developments
- In May 2025, Samsung Electronics Co. Ltd. unveiled its 2025 Bespoke AI Home Appliances lineup, including the Bespoke AI Jet Ultra cordless vacuum cleaner with up to 400 W of suction power and SmartThings integration.
- In April 2024, LG Electronics Inc. introduced India’s first Energy Manager air conditioner as part of a 77-model 2024 lineup for improved energy efficiency and smart monitoring.
- In November 2024, Sony Corporation (Sony India) celebrated 30 years of operations in India, highlighting its innovation across TVs, audio, imaging, and gaming.
- On 16 May 2025, Dell launched the Intel-powered Dell Plus consumer portfolio in India, debuting AI-enabled PCs like the Dell 14 Plus and Dell 16 Plus under its Copilot+ brandin
Market Concentration and Characteristics
The India Consumer Appliance Market exhibits moderate concentration, with top global and domestic brands controlling a significant portion of total revenues. It features an oligopolistic structure in premium segments, where Samsung, LG and Whirlpool dominate through advanced technology and extensive retail networks. Niche and regional players capture value in budget tiers by tailoring products to local needs and offering competitive pricing. Distribution remains fragmented across modern trade, specialty stores and general trade, requiring partners to maintain broad coverage. High entry barriers in manufacturing and service infrastructure protect incumbents, while rapid feature cycles and energy efficiency norms drive continual investment in R&D
Report Coverage
The research report offers an in-depth analysis based on Product Type, End User, Sales Channel, Channel Split and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Manufacturers will integrate artificial intelligence into home appliances to offer predictive maintenance and personalized user experiences. Smart diagnostics will reduce downtime and extend equipment lifespan.
- Energy-efficient designs will dominate new product launches, driven by tightening regulations and consumer demand for lower power bills. High star ratings will become a key purchase criterion.
- Modular and upgradable appliances will gain traction, allowing customers to replace components rather than entire units. It will reduce e-waste and appeal to eco-conscious buyers.
- Voice and gesture controls will expand beyond premium models into mid-range segments. Widespread adoption of regional language support will enhance accessibility.
- Collaborative platforms will emerge, where appliance makers partner with energy providers to offer bundled financing and maintenance plans. Customers will benefit from one-stop solutions.
- 5G connectivity will enable real-time performance monitoring and firmware updates over the air. It will streamline feature rollouts and security patches
- Brands will leverage augmented reality in online and in-store experiences to showcase appliance features and dimensions. Virtual demos will reduce returns and improve satisfaction.
- Battery-backed and solar-compatible models will address unreliable grid supply in rural markets. It will unlock growth in tier-2 and tier-3 regions.
- Subscription-based ownership models will rise, letting customers pay monthly fees for appliances bundled with service and upgrades. It will lower upfront costs and foster loyalty.
- Data analytics will guide product development and marketing strategies by tracking usage patterns. It will enable brands to tailor features and promotions to specific consumer segments.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Strong Economic Growth and Rising Incomes
India's sustained GDP growth and increasing household incomes are enabling more consumers to purchase both basic and premium appliances, expanding the overall market size.
Urbanization and Infrastructure Expansion
Rapid migration to urban centers and improved infrastructure, including electrification and road networks, are making appliances more accessible and driving higher penetration in both metropolitan and emerging tier-2 and tier-3 cities.
Government Energy Efficiency Policies
Stringent energy efficiency norms and the Bureau of Energy Efficiency’s star rating program are pushing manufacturers to innovate and encouraging consumers to upgrade to high-efficiency, premium appliances.
Growth of Organized Retail and Digital Channels
The expansion of organized retail outlets and the rise of online marketplaces are increasing product visibility, streamlining distribution, and making it easier for consumers to compare and purchase appliances.
Integration of Smart and Sustainable Features
Consumer demand for IoT-enabled, smart appliances and eco-friendly designs is prompting manufacturers to differentiate products with advanced features, supporting premiumization and higher margins.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate of the India Consumer Appliance Market?
What factors are driving the growth of the India Consumer Appliance Market?
Which regions lead volume sales of consumer appliances in India?
Who are the leading players in the India Consumer Appliance Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Domestic
- 1.2.2 Professional
- 1.2.3 Hotels
- 1.2.4 Salon & Grooming Parlors
- 1.2.5 Cafeteria & Restaurants
- 1.2.6 Offices & Institute
- 1.2.7 Other
- 1.3 By Product Type
- 1.3.1 White Goods
- 1.3.2 Brown Goods
- 1.4 By Sales Channel
- 1.4.1 Offline
- 1.4.2 Organized Retailer
- 1.4.3 Unorganized
- 1.4.4 Online
- 1.4.5 Company Direct Sales
- 1.4.6 Independent Vendor/E Commerce
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 48.15 million → 2032: USD 81.13 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Consumer Appliance Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Consumer Appliance Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Consumer Appliance Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Consumer Appliance Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Consumer Appliance Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Consumer Appliance Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Consumer Appliance Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Consumer Appliance Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 48.15 million → 2032: USD 81.13 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Consumer Appliance Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Domestic
- 12.3.7.2 Professional
- 12.3.7.3 Hotels
- 12.3.7.4 Salon & Grooming Parlors
- 12.3.7.5 Cafeteria & Restaurants
- 12.3.7.6 Offices & Institute
- 12.3.7.7 Other
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 White Goods
- 12.4.7.2 Brown Goods
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Offline
- 12.5.7.2 Organized Retailer
- 12.5.7.3 Unorganized
- 12.5.7.4 Online
- 12.5.7.5 Company Direct Sales
- 12.5.7.6 Independent Vendor/E Commerce
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 India Consumer Appliance End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 India Consumer Appliance Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 India Consumer Appliance Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 India Consumer Appliance Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Samsung Electronics Co Ltd
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 LG Electronics Inc
- 18.4 Whirlpool Corporation
- 18.5 Godrej Appliances
- 18.6 Haier
- 18.7 Sony Corporation
- 18.8 Dell
- 18.9 Voltas
- 18.10 Panasonic
- 18.11 IFB Appliances
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

