
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Healthcare Supply Chain Management Market Size 2023 | USD 71.42 million |
| India Healthcare Supply Chain Management Market, CAGR | 14.4% |
| India Healthcare Supply Chain Management Market Size 2032 | USD 239.53 million |
Market Overview
India Healthcare Supply Chain Management Market size was valued at USD 71.42 million in 2023 and is anticipated to reach USD 239.53 million by 2032, at a CAGR of 14.4% during the forecast period (2023-2032).
The India healthcare supply chain management market is experiencing significant growth, driven by the rapid digitalization of healthcare infrastructure and the increasing need for operational efficiency. The growing demand for real-time data tracking, automation, and inventory optimization across hospitals and pharmaceutical companies is encouraging the adoption of advanced supply chain solutions. Government initiatives promoting the use of health IT systems and investments in smart healthcare facilities further support market expansion. Additionally, the rising prevalence of chronic diseases and the need for uninterrupted access to essential medical supplies are propelling demand for reliable and agile supply chain networks. Emerging trends such as the integration of AI, blockchain, and IoT technologies are transforming supply chain operations by enhancing transparency, traceability, and predictive analytics. Moreover, the shift towards value-based care models and the increasing participation of private players are fostering innovation and collaboration, ultimately strengthening the overall efficiency and responsiveness of India’s healthcare supply chain ecosystem.
The geographical landscape of the India healthcare supply chain management market is shaped by varying levels of infrastructure development, technological adoption, and healthcare access across regions. Northern and Western India are witnessing robust growth due to the presence of advanced healthcare facilities, major pharmaceutical hubs, and increasing investments in digital logistics solutions. Southern India is emerging as a strong contender with its focus on medical tourism and health tech innovations, while Eastern India is gradually evolving through improved public health infrastructure and government-led initiatives. Key players driving the market include IBM Corporation, SAP SE, Oracle Corporation, Medikon India, Rhenus Group, Coupa, Infor, UPS Healthcare, Epicor Software Corporation, and Cardinal Health. These companies are actively involved in offering cloud-based platforms, AI-driven analytics, and integrated software solutions tailored to the Indian healthcare landscape. Emerging domestic players like AWL India and GEP are also making strategic contributions, enhancing supply chain agility and supporting the sector’s digital transformation.
Market Insights
- The India healthcare supply chain management market was valued at USD 71.42 million in 2023 and is projected to reach USD 239.53 million by 2032, growing at a CAGR of 14.4% from 2023 to 2032.
- The global healthcare supply chain management market was valued at USD 2,480.91 million in 2023 and is projected to reach USD 6,991.12 million by 2032, growing at a CAGR of 12.2% during the forecast period.
- Increasing demand for real-time inventory tracking and digital healthcare logistics is significantly driving market growth.
- Adoption of AI, IoT, and blockchain technologies is transforming healthcare supply chain operations across hospitals and pharmaceutical companies.
- Key players such as IBM Corporation, SAP SE, Oracle Corporation, and Medikon India are focusing on integrated software and cloud-based solutions to stay competitive.
- Fragmented infrastructure, lack of standardization, and regulatory complexity continue to restrain the growth of efficient supply chain networks.
- Northern and Western India are leading in adoption due to better infrastructure and concentration of healthcare facilities, while Eastern India is slowly evolving.
- The market is witnessing a shift from manual to automated systems, promoting cost efficiency and better resource planning.
Report Scope
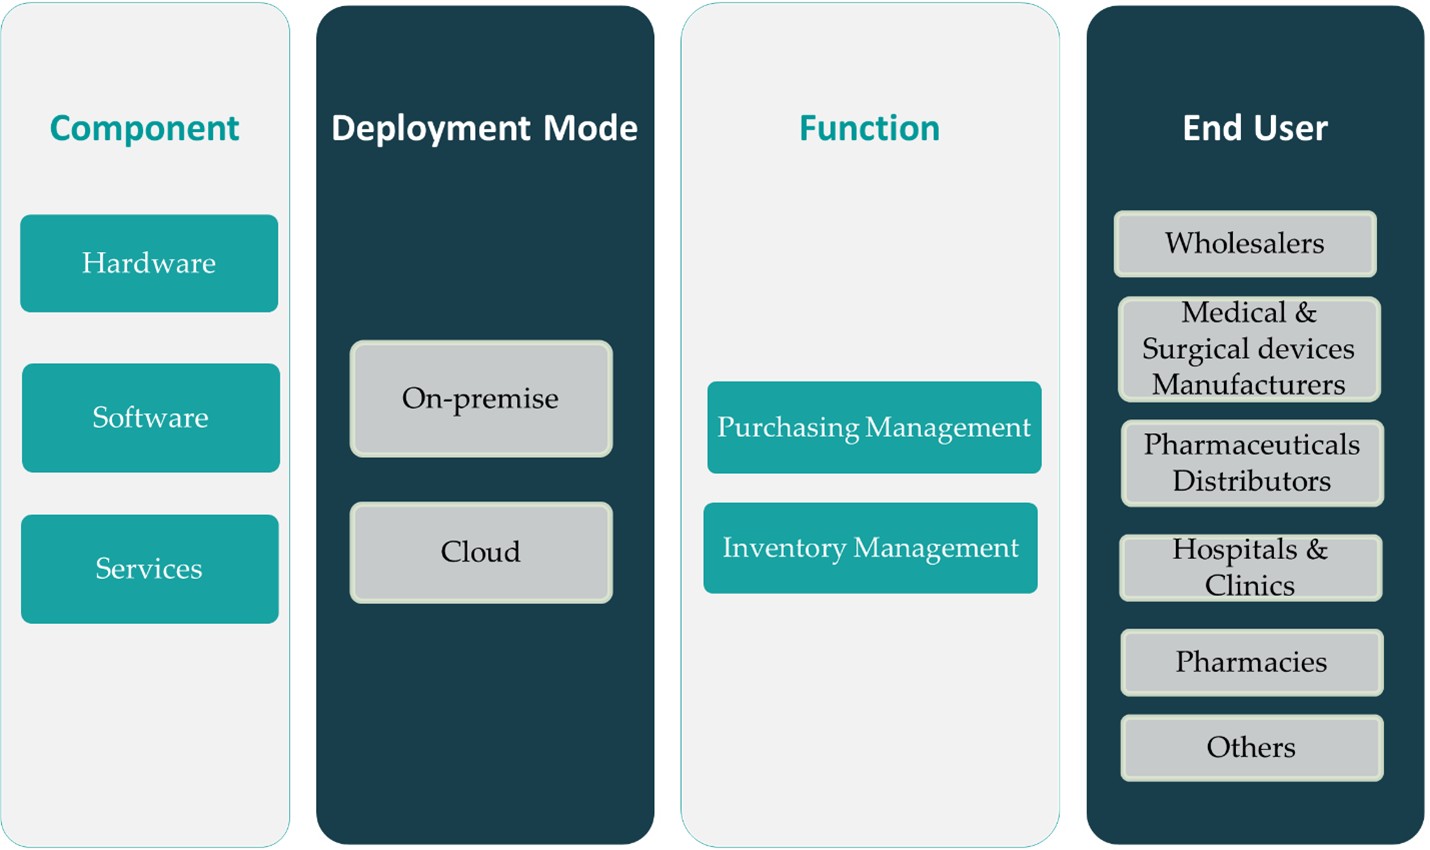
This report segments the India Healthcare Supply Chain Management Market as follows:
Market Drivers
Rising Demand for Efficient Inventory Management
The increasing pressure on healthcare facilities to manage growing patient volumes and expanding inventories has intensified the demand for efficient supply chain management systems across India. Hospitals and pharmaceutical companies are seeking real-time visibility and control over inventory levels to avoid stockouts or overstocking, which can disrupt patient care and incur financial losses. For instance, a survey conducted by the Ministry of Health and Family Welfare highlighted the adoption of automated inventory management systems in public hospitals, which has significantly reduced stockouts of essential medicines. Additionally, healthcare providers in metropolitan cities like Delhi and Mumbai have implemented AI-driven forecasting tools to maintain optimal inventory levels, ensuring timely availability of critical medical supplies in emergency departments.
Digital Transformation in Healthcare Logistics
Digitalization is playing a pivotal role in reshaping the Indian healthcare supply chain landscape. The adoption of technologies such as cloud computing, big data analytics, and enterprise resource planning (ERP) systems has empowered healthcare institutions to achieve greater transparency and control over supply chain processes. For instance, under the National Digital Health Mission (NDHM), hospitals in Bengaluru have integrated cloud-based ERP systems to track medical supplies in real-time, reducing inefficiencies and improving vendor coordination. Furthermore, a government-backed initiative in Hyderabad has implemented blockchain technology to prevent counterfeit drugs from entering the supply chain, ensuring the authenticity of pharmaceutical products.
Growing Emphasis on Cost Optimization and Operational Efficiency
Cost containment remains a top priority for both public and private healthcare providers in India, particularly amid rising treatment costs and budget constraints. Healthcare supply chain management solutions help reduce wastage, prevent pilferage, and improve procurement planning-ultimately lowering operational costs. As competition intensifies and margins tighten, hospitals and pharmaceutical firms are leveraging supply chain optimization to enhance resource utilization and ensure timely product availability without excess inventory. Moreover, third-party logistics (3PL) and supply chain outsourcing have gained popularity, allowing healthcare organizations to focus on core clinical functions while ensuring logistical efficiency. This heightened emphasis on cost-effective operations continues to fuel the adoption of innovative supply chain management systems.
Policy Support and Infrastructure Development
The Indian government’s ongoing efforts to improve healthcare infrastructure and accessibility are further catalyzing the growth of the healthcare supply chain management market. Initiatives such as Ayushman Bharat and Production Linked Incentive (PLI) schemes are fostering public-private collaborations and boosting domestic manufacturing of medical equipment and pharmaceuticals. These programs require strong supply chain frameworks to ensure the effective delivery of healthcare services and products, especially in rural and underserved regions. Furthermore, the government's push for Make in India and increased foreign direct investment (FDI) in the healthcare sector is leading to a more robust distribution network and advanced cold chain logistics. As policy frameworks become more favorable, healthcare organizations are increasingly investing in modernizing their supply chain capabilities to align with national healthcare goals.
Market Trends
Integration of Advanced Technologies
A major trend shaping the India healthcare supply chain management market is the growing integration of advanced technologies such as artificial intelligence (AI), blockchain, Internet of Things (IoT), and machine learning. These technologies are enhancing the accuracy, traceability, and efficiency of supply chain operations. AI and machine learning algorithms enable predictive analytics for demand forecasting, while IoT devices provide real-time tracking of medical assets and cold chain products. Blockchain is gaining traction for its ability to create tamper-proof records, ensuring the authenticity of pharmaceuticals and preventing counterfeit drugs. These innovations are not only streamlining supply chain workflows but also improving regulatory compliance and decision-making capabilities across the healthcare sector.
Rising Adoption of Cloud-Based Supply Chain Solutions
The shift toward cloud-based supply chain management platforms is another notable trend in the Indian healthcare industry. Cloud technology offers scalability, cost-efficiency, and seamless integration across multiple healthcare facilities, making it ideal for hospitals, clinics, and pharma distributors operating in a geographically diverse market like India. For instance, under the National Digital Health Mission (NDHM), hospitals in Delhi have adopted cloud-based platforms to centralize data access and automate workflows, significantly enhancing supply chain visibility and coordination. Furthermore, healthcare providers in Chennai have leveraged cloud solutions to enable remote monitoring and multi-location inventory control, which proved invaluable during the COVID-19 pandemic.
Expansion of Cold Chain Logistics
With the rising demand for vaccines, biologics, and temperature-sensitive drugs, the development of cold chain logistics has become a vital trend in the healthcare supply chain landscape. For instance, a survey by the Indian Council of Medical Research (ICMR) highlighted the deployment of sensor-based monitoring systems in refrigerated vehicles to ensure the safe transportation of vaccines. Additionally, government initiatives in Tier II and Tier III cities, such as those in Lucknow and Jaipur, have focused on enhancing cold chain infrastructure to improve accessibility and ensure the safe distribution of critical healthcare products. This trend is expected to significantly strengthen the supply chain resilience in both urban and rural healthcare networks.
Growing Role of Data Analytics in Strategic Decision-Making
Data analytics is playing an increasingly crucial role in shaping strategic supply chain decisions within the Indian healthcare sector. Organizations are leveraging data-driven insights to improve procurement planning, reduce lead times, minimize wastage, and enhance supplier performance. Advanced analytics tools help identify supply-demand gaps, monitor vendor compliance, and track product movement with high precision. By transforming raw data into actionable intelligence, healthcare providers and distributors are optimizing operational efficiency and responding more proactively to market changes. This data-centric approach is becoming integral to building agile and responsive supply chains, capable of adapting to evolving patient needs and regulatory requirements.
Market Challenges Analysis
Infrastructure Limitations and Fragmentation of Supply Chain
One of the most significant challenges facing the India healthcare supply chain management market is the inadequate infrastructure and fragmentation across various supply chain tiers. Many regions, especially in Tier II and Tier III cities and rural areas, lack proper warehousing facilities, transportation networks, and cold chain systems. For instance, a survey conducted by the Ministry of Health and Family Welfare highlighted that rural healthcare centers in Uttar Pradesh and Bihar face frequent stockouts due to inadequate cold chain infrastructure. Additionally, logistics companies in Maharashtra have started deploying sensor-based monitoring systems to reduce spoilage of temperature-sensitive medical products during transit. The absence of standardized logistics protocols further complicates coordination among stakeholders, as noted in a government-backed study on healthcare supply chain inefficiencies.
Regulatory Complexity and Data Management Challenges
Regulatory compliance remains a complex hurdle for supply chain operators in the Indian healthcare sector. Frequent policy changes, lack of centralized oversight, and varying compliance requirements across states often lead to confusion and inconsistent implementation. Navigating these regulatory frameworks can be time-consuming and resource-intensive, particularly for small and mid-sized enterprises. In addition, the healthcare sector generates vast volumes of data that are often unstructured and poorly integrated across systems. Many healthcare organizations struggle with limited IT infrastructure, making it difficult to capture, store, and analyze supply chain data effectively. This lack of data interoperability hinders informed decision-making, slows response times, and reduces overall supply chain agility. Ensuring data privacy and security further complicates digital transformation initiatives, especially as more stakeholders adopt cloud-based and IoT-enabled supply chain platforms. These regulatory and data management issues continue to pose serious challenges to the widespread adoption and optimization of healthcare supply chain management solutions in India.
Market Opportunities
The India healthcare supply chain management market presents significant growth opportunities, largely driven by the rapid expansion of the country's healthcare infrastructure and the increasing adoption of digital health technologies. As public and private healthcare providers continue to invest in modernizing their operations, there is a growing demand for integrated supply chain solutions that ensure efficiency, transparency, and resilience. The government’s initiatives such as Ayushman Bharat, National Digital Health Mission, and Production Linked Incentive (PLI) schemes are catalyzing investments in healthcare delivery systems, thereby creating a favorable environment for the deployment of advanced supply chain technologies. Additionally, the increasing burden of chronic diseases, a growing aging population, and rising patient expectations are pushing healthcare institutions to adopt data-driven logistics and inventory management solutions that improve patient care and operational efficiency.
Moreover, the increasing penetration of technologies such as AI, IoT, blockchain, and cloud computing offers new avenues for innovation within the healthcare supply chain ecosystem. Start-ups and technology providers have ample scope to develop scalable, secure, and cost-effective platforms tailored to the unique needs of India’s diverse healthcare landscape. With a growing emphasis on personalized medicine, temperature-sensitive biologics, and telehealth, the demand for agile, responsive, and compliant supply chains is set to rise. There is also a strong opportunity for expanding cold chain logistics and last-mile delivery systems, particularly in rural and underserved regions, to ensure equitable access to critical medicines and vaccines. As the industry continues to move toward digital transformation, companies that can offer customizable, interoperable, and regulatory-compliant solutions will be well-positioned to capitalize on the evolving needs of India's healthcare supply chain sector.
Market Segmentation Analysis:
By Component:
The India healthcare supply chain management market is segmented by component into hardware, software, and services. Among these, the software segment holds a significant share, driven by the increasing demand for integrated platforms that support inventory tracking, procurement planning, and order management. Healthcare providers are increasingly deploying supply chain management software to streamline workflows, enhance operational visibility, and ensure regulatory compliance. The growing need to reduce wastage and optimize resource allocation has further accelerated the adoption of AI-powered and analytics-based software systems. Meanwhile, the hardware segment-comprising RFID tags, barcode scanners, and IoT devices-is also witnessing growth due to its crucial role in asset tracking and cold chain monitoring. Additionally, the services segment is expected to gain momentum as healthcare organizations increasingly rely on third-party logistics, maintenance, system integration, and consulting services to improve supply chain performance. With the ongoing shift toward value-based healthcare delivery, all three components are anticipated to contribute steadily to market expansion in the coming years.
By Deployment Mode:
Based on deployment mode, the market is divided into on-premise and cloud-based solutions. Cloud-based deployment is gaining rapid traction, particularly among small to mid-sized hospitals and clinics, due to its scalability, cost-effectiveness, and ease of access across multiple locations. Cloud platforms enable real-time data synchronization, centralized inventory control, and seamless communication among stakeholders, making them ideal for India's fragmented and geographically dispersed healthcare landscape. Moreover, the increasing preference for remote monitoring and mobile accessibility is further driving the adoption of cloud solutions. On the other hand, on-premise deployment continues to be favored by larger healthcare institutions that require high levels of customization, data control, and security. These systems offer robust functionality but demand significant upfront investments and IT infrastructure. Despite this, the shift toward cloud adoption is expected to accelerate in the coming years, supported by improvements in digital literacy, regulatory clarity, and government initiatives promoting health IT integration across the country.
Segments:
Based on Component:
- Hardware
- Software
- Services
Based on Deployment Mode:
- On-premise
- Cloud
Based on Function:
- Purchasing Management
- Inventory Management
Based on End User:
- Medical & Surgical Device Manufacturers
- Pharmaceutical Distributors
- Wholesalers
- Hospital & Clinics
- Pharmacies
- Others
Based on the Geography:
- Northern
- Western
- Southern
- Eastern
Regional Analysis
Northern
Northern India accounts for the largest share of the India healthcare supply chain management market, contributing approximately 35% of the total market revenue in 2023. This dominance is primarily attributed to the presence of major metropolitan cities like Delhi and Chandigarh, which host a high concentration of multi-specialty hospitals, diagnostic centers, and pharmaceutical companies. The region benefits from relatively advanced healthcare infrastructure, robust public-private healthcare partnerships, and higher awareness levels regarding digital supply chain solutions. Additionally, ongoing government initiatives and investments in smart healthcare logistics and digital health integration across Northern states such as Uttar Pradesh, Haryana, and Punjab are driving the adoption of cloud-based and AI-enabled supply chain management tools. The presence of top-tier healthcare institutions and a strong pharmaceutical manufacturing base further fuels the region’s leadership in this domain.
Western
Western India holds a substantial 28% market share in the healthcare supply chain management landscape, supported by industrial hubs such as Mumbai, Pune, and Ahmedabad. These cities are home to leading pharmaceutical manufacturers and healthcare technology providers that are actively investing in smart logistics and supply chain infrastructure. Maharashtra and Gujarat, in particular, have shown significant progress in adopting automation, IoT, and cold chain technologies for streamlined distribution of vaccines and medical supplies. The presence of specialized healthcare logistics companies and a strong regulatory framework also enhance the efficiency of healthcare supply chains in this region. Moreover, the Western region benefits from advanced connectivity, strong vendor networks, and increased deployment of ERP and inventory management systems, contributing to its notable share in the national market.
Southern
Southern India represents around 22% of the India healthcare supply chain management market, driven by the growing healthcare demands in states like Tamil Nadu, Karnataka, and Telangana. The region is recognized for its medical tourism, well-established hospital networks, and early adoption of digital health solutions. Cities such as Bengaluru, Hyderabad, and Chennai have become hubs for health tech start-ups and innovation, which has accelerated the integration of cloud platforms, RFID-based tracking, and AI-powered analytics into healthcare logistics. Southern India also benefits from government-backed digital infrastructure projects and training programs aimed at improving supply chain capabilities in public healthcare systems. This proactive digital approach is steadily enhancing the region’s contribution to the national market.
Eastern
Eastern India holds the smallest market share at approximately 15%, primarily due to infrastructural limitations and lower penetration of advanced healthcare systems in several areas. However, the region is experiencing gradual growth supported by increasing healthcare investments in states like West Bengal, Odisha, and Assam. The ongoing development of medical colleges, district hospitals, and regional health centers is boosting the demand for efficient supply chain systems to manage pharmaceutical distribution and medical equipment supply. Additionally, government schemes and donor-funded programs are encouraging digital transformation across public health logistics. Although the market is still emerging in Eastern India, improvements in connectivity, awareness, and technology adoption are likely to enhance its market presence in the near future.
Key Player Analysis
- IBM Corporation
- SAP SE
- Medikon India
- Rhenus Group
- Oracle Corporation
- Coupa
- Infor
- UPS Healthcare
- Epicor Software Corporation
- Cardinal Health
- Blue Yonder Group, Inc.
- AWL India
- Workday Inc.
- GEP
- Manhattan Associates
- Others
Competitive Analysis
The India healthcare supply chain management market is highly competitive, with key players actively leveraging technological advancements to strengthen their market position. Leading companies such as IBM Corporation, SAP SE, Oracle Corporation, Medikon India, Rhenus Group, Coupa, Infor, UPS Healthcare, Epicor Software Corporation, Cardinal Health, Blue Yonder Group, Inc., AWL India, Workday Inc., GEP, and Manhattan Associates are focusing on offering comprehensive supply chain solutions that include real-time tracking, cloud-based inventory management, demand forecasting, and analytics-driven decision-making. These players are investing heavily in research and development to enhance their platforms with AI, machine learning, and IoT capabilities tailored to the healthcare sector. Multinational corporations are forming strategic alliances with local healthcare providers and logistics firms to expand their footprint and offer localized solutions, while domestic players are focusing on affordability and customization to address the unique needs of India’s diverse healthcare ecosystem. Additionally, the increasing demand for cold chain logistics, data interoperability, and regulatory compliance has intensified competition among players striving to differentiate themselves through innovation, customer service, and end-to-end integration. As the market continues to digitize, companies that offer scalable, secure, and agile supply chain platforms are expected to gain a competitive edge in the evolving Indian healthcare landscape.
Recent Developments
- In March 2025, SAP unveiled its vision for autonomous supply chains embedded with AI-first strategies and launched SAP Business Data Cloud for enhanced operational visibility.
- In February 2025, GHX celebrated its Supply Chains of Distinction Award, recognizing top-performing hospitals that excelled in automation and clinical integration.
- In January 2025, McKesson's Practice Insights was named a Qualified Clinical Data Registry by CMS, enabling oncology practices to streamline data reporting and improve patient care.
- In November 2024, IBM integrated generative AI into its cognitive control tower, enabling natural language queries for faster decision-making. This transformation saved $388 million in inventory and shipping costs.
- In September 2024, Oracle introduced RFID-powered replenishment solutions in its Cloud SCM platform to automate inventory management and improve visibility across healthcare supply chains.
Market Concentration & Characteristics
The India healthcare supply chain management market demonstrates a moderately concentrated structure, characterized by the presence of several established global players alongside emerging domestic firms. While multinational companies such as IBM Corporation, SAP SE, and Oracle Corporation dominate with advanced technological offerings and robust financial capabilities, regional players like Medikon India and AWL India are gaining traction through localized, cost-effective solutions. The market is defined by rapid digitalization, increasing adoption of cloud-based systems, and rising demand for integrated logistics platforms tailored to healthcare requirements. Key characteristics include a growing emphasis on real-time inventory visibility, automation of procurement processes, and regulatory compliance across pharmaceutical and hospital supply chains. The market also reflects high entry barriers due to the need for domain expertise, investment in advanced IT infrastructure, and adherence to health regulations. As the sector continues to evolve, strategic collaborations and innovation will play a vital role in shaping the competitive dynamics and market expansion.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment Mode, Function, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The healthcare supply chain in India will increasingly adopt digital technologies for real-time tracking and inventory management.
- Artificial intelligence and machine learning will enhance forecasting accuracy and decision-making in supply chain operations.
- The demand for cold chain logistics will rise due to growth in biologics and temperature-sensitive pharmaceuticals.
- Public-private partnerships are expected to strengthen, improving logistics efficiency and healthcare access in rural areas.
- Automation and robotics will play a larger role in warehouse management and order fulfillment.
- The adoption of blockchain technology will improve transparency, traceability, and security across the supply chain.
- E-pharmacy growth will drive the need for faster last-mile delivery solutions and advanced distribution networks.
- Government initiatives like Ayushman Bharat will continue to influence supply chain infrastructure upgrades.
- Increased focus on sustainability will encourage green logistics and eco-friendly packaging in the healthcare sector.
- Investment in supply chain workforce training and development will become a priority to support digital transformation.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Digital Transformation in Healthcare Logistics
The rapid adoption of cloud computing, big data analytics, and ERP systems is enabling Indian healthcare providers to achieve greater transparency, control, and efficiency in supply chain operations, driving market growth.
Government Policy Support and Infrastructure Development
Initiatives such as Ayushman Bharat, the National Digital Health Mission, and Production Linked Incentive schemes are fostering public-private partnerships and investments in healthcare infrastructure, necessitating robust supply chain management solutions.
Emphasis on Cost Optimization and Operational Efficiency
Healthcare organizations are increasingly adopting supply chain management systems to reduce wastage, prevent pilferage, and optimize procurement, which is critical for maintaining profitability amid rising treatment costs and budget constraints.
Integration of Advanced Technologies
The use of AI, IoT, and blockchain is transforming supply chain operations by improving real-time tracking, predictive analytics, and traceability, which enhances regulatory compliance and reduces the risk of counterfeit drugs.
Expansion of Cold Chain Logistics
Growing demand for vaccines, biologics, and temperature-sensitive pharmaceuticals is driving investments in cold chain infrastructure and sensor-based monitoring, ensuring safe and efficient distribution across urban and rural regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
what is the current size of the India Healthcare Supply Chain Management market?
What factors are driving the growth of the India Healthcare Supply Chain Management market?
What are the key segments within the India Healthcare Supply Chain Management market?
Who are the major players in the India Healthcare Supply Chain Management market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Medical & Surgical Device Manufacturers
- 1.2.2 Pharmaceutical Distributors
- 1.2.3 Wholesalers
- 1.2.4 Hospitals & Clinics
- 1.2.5 Pharmacies
- 1.2.6 Others
- 1.3 By Function
- 1.3.1 Purchasing Management
- 1.3.2 Inventory Management
- 1.4 By Component
- 1.4.1 Hardware
- 1.4.2 Software
- 1.4.3 Services
- 1.5 By Deployment Mode
- 1.5.1 On-premise
- 1.5.2 Cloud
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 71.42 million → 2032: USD 239.53 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Healthcare Supply Chain Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Healthcare Supply Chain Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Healthcare Supply Chain Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Healthcare Supply Chain Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Healthcare Supply Chain Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Healthcare Supply Chain Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Healthcare Supply Chain Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Healthcare Supply Chain Management Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 71.42 million → 2032: USD 239.53 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Healthcare Supply Chain Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Medical & Surgical Device Manufacturers
- 12.3.7.2 Pharmaceutical Distributors
- 12.3.7.3 Wholesalers
- 12.3.7.4 Hospitals & Clinics
- 12.3.7.5 Pharmacies
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Function - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Purchasing Management
- 12.4.7.2 Inventory Management
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Component - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hardware
- 12.5.7.2 Software
- 12.5.7.3 Services
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Deployment Mode - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 On-premise
- 12.6.7.2 Cloud
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 India Healthcare Supply Chain Management End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 India Healthcare Supply Chain Management Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 India Healthcare Supply Chain Management Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 India Healthcare Supply Chain Management Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 IBM Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 SAP SE
- 18.4 Oracle Corporation
- 18.5 Medikon India
- 18.6 Rhenus Group
- 18.7 Coupa
- 18.8 Infor
- 18.9 UPS Healthcare
- 18.10 Epicor Software Corporation
- 18.11 Cardinal Health
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

