
Market Overview
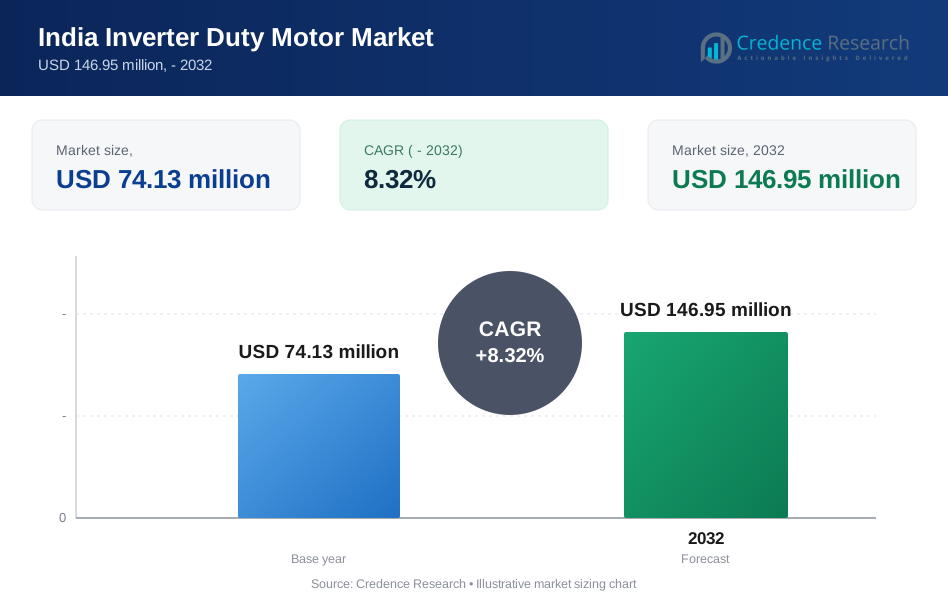
India Inverter Duty Motor market size was valued at USD 45.04 million in 2018 to USD 74.13 million in 2024 and is anticipated to reach USD 146.95 million by 2032, at a CAGR of 8.32% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Inverter Duty Motor Market Size 2024 | USD 74.13 Million |
| India Inverter Duty Motor Market, CAGR | 8.32% |
| India Inverter Duty Motor Market Size 2032 | USD 146.95 Million |
The India inverter duty motor market features strong participation from leading players such as Regal Rexnord, ABB Ltd., Siemens AG, General Electric Company (GE), Nidec Motor Corporation, Rockwell Automation, Inc., and Havells India Ltd. These companies compete through advanced product portfolios, energy-efficient designs, and robust service networks that cater to diverse industrial applications. Global players focus on innovation and digital integration, while domestic firms deliver cost-effective solutions for localized needs. Regionally, North India leads with a 34% market share in 2024, supported by thriving chemicals, cement, and textile industries, followed by South and West India, which remain major growth hubs due to oil, gas, and mining activities.
Market Insights
- The India inverter duty motor market was valued at USD 74.13 million in 2024 and is projected to reach USD 146.95 million by 2032, growing at a CAGR of 8.32%.
- Rising industrial automation and demand for energy-efficient systems drive adoption, with pumps holding the dominant application share of 38% due to extensive use in water handling and chemical processes.
- Key trends include the shift toward IE2 and IE3 efficiency-class motors and integration of IoT-enabled monitoring solutions, enabling predictive maintenance and improved performance across industries.
- The competitive landscape includes global players such as Regal Rexnord, ABB, Siemens, GE, Nidec, Rockwell Automation, and Havells India, with domestic manufacturers focusing on cost-effective localized offerings to capture SME demand.
- Regionally, North India leads with 34% share, followed by South India at 28%, West India at 24%, and East India at 14%, driven by chemicals, oil and gas, cement, and textile clusters.
Market Segmentation Analysis:
By Construction Material
Cast iron holds the dominant share in the India inverter duty motor market, accounting for over 45% of the segment in 2024. Its widespread use comes from superior strength, vibration damping, and cost-effectiveness in heavy-duty applications. Laminated steel motors follow, driven by efficiency and lower core losses, making them ideal in high-performance operations. Aluminum motors, while lighter and corrosion-resistant, remain concentrated in smaller machinery. Rising demand for robust motors in industrial processes ensures cast iron continues to lead, supported by long service life and suitability for harsh environments.
- For instance, ABB manufactures a wide range of motors for the cement industry. The company provides high-efficiency, robust cast-iron motors designed for demanding applications such as crushers, mills, and kilns, which are typical in cement plants.
By Application
Pumps represent the leading application segment, contributing nearly 38% of the total share in 2024. Industries rely heavily on inverter duty motors for consistent fluid handling, chemical dosing, and water circulation. Fans follow closely due to their extensive use in HVAC systems, power plants, and industrial ventilation. Conveyors and extruders expand steadily with the growth of material handling and plastics sectors. The dominance of pumps is supported by India’s rapid industrialization, infrastructure expansion, and water treatment projects, which demand energy-efficient, variable-speed motor solutions.
- For instance, in 2025, Crompton Greaves Consumer Electricals Ltd. secured two major orders for solar-powered water pumps under the government's PM-KUSUM scheme -an order for 4,500 solar pumping systems from the Maharashtra Energy Development Agency (MEDA).
By End User Industry
The chemicals industry holds the largest share, exceeding 22% in 2024, reflecting its heavy reliance on pumps, agitators, and compressors driven by inverter duty motors. Oil and gas follows, where motors are critical for upstream and downstream operations requiring reliable performance in harsh conditions. Metals and mining also remain a strong contributor due to demand for rugged equipment. Growth in pulp and paper, pharmaceuticals, textiles, and cement industries supports diversification. Rising chemical production capacity and expansion of refineries cement the chemical sector’s leadership, driven by durability and efficiency needs.
Key Growth Drivers
Rising Industrial Automation
The India inverter duty motor market grows with rapid industrial automation adoption across sectors. Automated systems in chemicals, cement, and metals rely on motors that can handle variable speeds and high torque. Inverter duty motors enable energy efficiency, reduced downtime, and flexible operation under fluctuating loads. With Industry 4.0 driving smart manufacturing, the demand for motors supporting continuous process optimization is increasing. This shift toward automated plants positions inverter duty motors as essential components for ensuring reliability and operational excellence in India’s expanding industrial landscape.
- For instance, ABB is a major supplier of motors and drives to the steel and cement industries in India and has a long-standing business relationship with JSW Steel's Vijayanagar plant, which has a production capacity of 17.5 MTPA.
Expansion of Water and Wastewater Infrastructure
Government investments in water supply and wastewater treatment projects boost demand for inverter duty motors in pumping applications. These motors offer precise speed control, energy savings, and durability, making them ideal for large-scale water handling. Rising urbanization and population growth increase pressure on water management systems, pushing utilities toward efficient motorized pumping solutions. As cities modernize and industrial zones expand, the adoption of inverter duty motors strengthens. Their ability to support long operational hours under varying loads makes them critical for India’s water infrastructure projects.
- For instance, in 2023 and 2024, Crompton Greaves secured multiple projects in Maharashtra under the PM-KUSUM scheme to supply and install solar photovoltaic water pumping systems for agricultural use. Some of these contracts included a project for 1,884 solar pumps valued at around ₹49 crore and a larger project for 4,500 pumps worth approximately ₹101 crore. The company continues to be a market leader in pumps, with a focus on sustainable and energy-efficient pumping solutions.
Growth in Oil, Gas, and Petrochemical Sector
The oil, gas, and petrochemical industries in India require motors that withstand hazardous and high-temperature environments. Inverter duty motors are essential in driving compressors, pumps, and agitators in upstream and downstream operations. Rising refining capacity, expanding petrochemical plants, and ongoing energy investments fuel demand for high-performance motors. Their ability to function reliably under variable load conditions provides significant operational benefits. As the sector remains a key contributor to India’s industrial GDP, investments in energy projects continue to support the strong adoption of inverter duty motors.
Key Trends & Opportunities
Shift Toward Energy-Efficient Solutions
Energy efficiency regulations and rising electricity costs encourage industries to adopt inverter duty motors. These motors, when paired with variable frequency drives, help reduce energy consumption by 20–30% in many applications. Companies are investing in IE2 and IE3 efficiency class motors to meet both regulatory and sustainability targets. This trend creates opportunities for manufacturers to introduce advanced, eco-friendly motor designs. Growing awareness of lifecycle cost savings supports continued replacement of conventional motors with energy-efficient inverter duty variants across industrial sectors in India.
- For instance, in December 2014, Siemens Ltd. announced it had surpassed a milestone of delivering over 100,000 IE-class energy-efficient motors since their launch in India in 2012.
Integration of Digital Monitoring and IoT
The integration of IoT-enabled sensors and predictive monitoring systems enhances motor performance and lifespan. Industries use smart diagnostics to monitor vibration, temperature, and load fluctuations in real time. This adoption supports predictive maintenance strategies, minimizing unplanned downtime and extending asset life. Manufacturers offering inverter duty motors with built-in connectivity features gain a competitive edge. With India’s push toward digital transformation in manufacturing, demand for smart, connected inverter duty motors is expected to rise, creating opportunities for suppliers that focus on advanced monitoring capabilities.
- For instance, ABB offers the ABB Ability Smart Sensor system, which enables predictive maintenance for industrial motors. According to ABB, the use of this system can potentially reduce unplanned downtime by up to 70%, extend motor lifespan by up to 30%, and improve energy efficiency.
Key Challenges
High Initial Investment Costs
Inverter duty motors are more expensive than conventional motors due to specialized windings, insulation, and design enhancements. Small and medium enterprises often hesitate to adopt these motors because of high upfront costs. While lifecycle savings through energy efficiency and reduced maintenance are significant, the payback period discourages budget-sensitive buyers. Limited awareness of long-term benefits further slows adoption. This cost barrier remains a critical challenge, particularly in price-sensitive industrial segments where capital expenditure decisions heavily influence motor selection.
Lack of Skilled Workforce for Advanced Systems
Operating and maintaining inverter duty motors requires specialized knowledge of variable frequency drives and control systems. Many industrial plants in India face shortages of skilled technicians capable of handling advanced motor technologies. Inadequate training programs and limited technical expertise create maintenance gaps, leading to reduced efficiency or unexpected downtime. This skill shortage restricts full-scale adoption in sectors that could otherwise benefit from inverter duty motors. Addressing workforce development through targeted training programs remains vital to overcome this operational challenge.
Regional Analysis
North India
North India accounts for the largest share of the India inverter duty motor market, contributing nearly 34% in 2024. The region benefits from strong demand in chemicals, cement, and textile industries concentrated in states like Uttar Pradesh, Haryana, and Punjab. Rapid expansion of water treatment infrastructure and industrial clusters further supports adoption. Investments in smart city projects and urban utilities create additional opportunities for pumps and fans driven by inverter duty motors. With its established manufacturing base and growing focus on energy-efficient solutions, North India continues to dominate the market.
South India
South India holds around 28% of the India inverter duty motor market in 2024, driven by thriving oil and gas, cement, and food processing sectors. States such as Tamil Nadu, Karnataka, and Andhra Pradesh serve as hubs for heavy industries and refineries. Strong port infrastructure and large-scale industrial corridors accelerate demand for reliable motorized equipment. The presence of global and domestic manufacturing facilities also promotes higher adoption. South India’s growing pharmaceutical production and continuous expansion in petrochemical capacity further strengthen its role as a key market for inverter duty motors.
West India
West India captures close to 24% of the inverter duty motor market in 2024, fueled by metals, mining, and cement industries. Maharashtra and Gujarat host major industrial hubs, with significant investments in manufacturing and petrochemicals. Robust infrastructure development, particularly in urban water supply and wastewater treatment, creates steady demand for pumps and conveyors powered by inverter duty motors. The strong automotive and textile clusters in Gujarat also contribute to adoption. West India’s strategic location, coupled with its expanding industrial base, positions it as a critical growth region for the market.
East India
East India accounts for approximately 14% of the India inverter duty motor market in 2024, supported mainly by pulp and paper, cement, and mining activities. States such as Odisha, West Bengal, and Jharkhand drive demand through resource-intensive industries. The region’s growing focus on power generation and steel manufacturing requires efficient and durable motors. Although adoption lags behind other regions due to slower industrialization, government investments in infrastructure and industrial corridors are changing the outlook. East India presents emerging opportunities for inverter duty motor suppliers as modernization initiatives gain momentum.
Market Segmentations:
By Construction Material
- Cast Iron
- Laminated Steel
- Aluminum
By Application
- Pumps
- Fans
- Conveyors
- Extruders
- Others
By End User Industry
- Chemicals
- Oil & Gas
- Metals & Mining
- Pulp & Paper
- Food & Beverage
- Pharmaceuticals
- Textile Processing
- Cement
- Others
By Geography
- North India
- South India
- West India
- East India
Competitive Landscape
The competitive landscape of the India inverter duty motor market is characterized by the presence of global leaders and strong domestic manufacturers competing across industrial applications. Key players such as Regal Rexnord, ABB Ltd., Siemens AG, General Electric Company (GE), Nidec Motor Corporation, Rockwell Automation, Inc., and Havells India Ltd. dominate through broad product portfolios, advanced motor technologies, and established distribution networks. Global companies focus on high-efficiency designs, digital integration, and industry-specific solutions, while domestic firms emphasize cost-effective products tailored for local industries. Strategic partnerships, capacity expansions, and technological innovations remain central to competition. Increasing demand from chemicals, oil and gas, and cement industries encourages players to strengthen after-sales support and localized production. Rising government focus on energy efficiency regulations and industrial modernization further intensifies competition, as suppliers race to deliver motors aligned with IE2 and IE3 standards. Continuous product development and customer-centric service strategies define success in this competitive environment.
Key Player Analysis
- Regal Beloit Corporation (now Regal Rexnord)
- ABB Ltd.
- Siemens AG
- General Electric Company (GE)
- Nidec Motor Corporation
- Rockwell Automation, Inc.
- Havells India Ltd.
Recent Developments
- In May 2025, the European Union implemented new energy efficiency regulations, mandating the use of inverter duty motors in specific applications to reduce energy consumption and carbon emissions. This policy change is expected to drive market growth and boost demand for energy-efficient motor solutions (European Commission press release, 2025).
- In January 2024, ABB and Schneider Electric formed a strategic partnership to collaborate on developing and marketing integrated power conversion solutions. This collaboration combines ABB's expertise in power conversion technology with Schneider Electric's strength in electrical distribution and automation systems (ABB press release, 2024).
- In August 2023, Bosch commenced production of 800-volt powertrain components, including inverters and electric motors, enhancing electric vehicle charging speed and efficiency. Leveraging silicon carbide technology, these components deliver increased range and compact design, with a German automaker already adopting the new electric motor's core components.
- In March 2023, Siemens Energy announced the launch of its new multilevel converter technology, which enables higher power density and efficiency for inverter duty motors. This innovation reduces energy losses and enhances overall system performance (Siemens Energy press release, 2023).
Report Coverage
The research report offers an in-depth analysis based on Construction Material, Application, End User Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand steadily with rising industrial automation and smart manufacturing adoption.
- Energy efficiency regulations will drive higher demand for IE2 and IE3 class inverter duty motors.
- Increasing investment in water and wastewater treatment projects will strengthen pump-related applications.
- Oil, gas, and petrochemical industries will continue to be major end users of inverter duty motors.
- Digital monitoring and IoT integration will gain traction for predictive maintenance and performance optimization.
- Domestic manufacturers will enhance cost-effective solutions to serve small and medium enterprises.
- Growing cement, metals, and mining activities will boost demand for heavy-duty cast iron motors.
- Pharmaceutical and food processing sectors will adopt motors to support precise and continuous operations.
- Regional growth will be strongest in North and South India due to industrial clusters and infrastructure expansion.
- Strategic collaborations and capacity expansions will define competitive strategies among leading players.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for India Inverter Duty Motor market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the India Inverter Duty Motor market projected to grow between 2025 and 2032?
Which India Inverter Duty Motor market segment held the largest share in 2024?
What are the primary factors fueling the growth of the India Inverter Duty Motor market?
Who are the leading companies in the India Inverter Duty Motor market?
Which region commanded the largest share of the India Inverter Duty Motor market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 India Inverter Duty Motor Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global India Inverter Duty Motor Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 74.13 million → 2032: USD 146.95 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 India Inverter Duty Motor Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. India Inverter Duty Motor Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 India Inverter Duty Motor Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 India Inverter Duty Motor Market Drivers
- 3.3 India Inverter Duty Motor Market Restraints & Challenges
- 3.4 India Inverter Duty Motor Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 India Inverter Duty Motor Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 India Inverter Duty Motor Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, India Inverter Duty Motor category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 India Inverter Duty Motor Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. India Inverter Duty Motor Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the India Inverter Duty Motor market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 India Inverter Duty Motor Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 India Inverter Duty Motor Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 India Inverter Duty Motor Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in India Inverter Duty Motor (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New India Inverter Duty Motor Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global India Inverter Duty Motor Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America India Inverter Duty Motor Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe India Inverter Duty Motor Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific India Inverter Duty Motor Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America India Inverter Duty Motor Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East India Inverter Duty Motor Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa India Inverter Duty Motor Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. India Inverter Duty Motor Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
