
Market Overview:
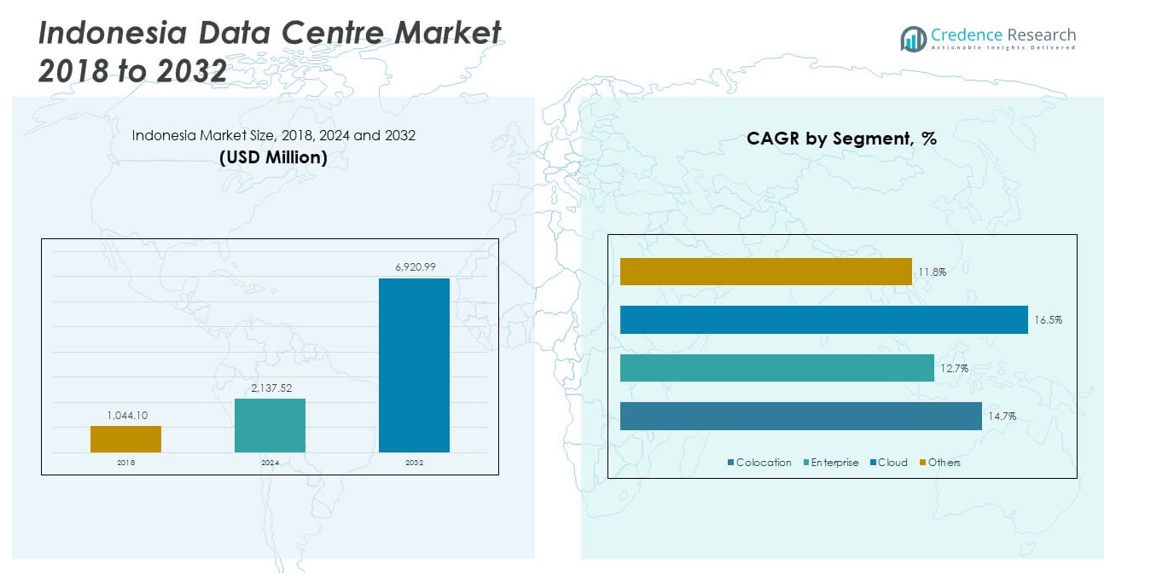
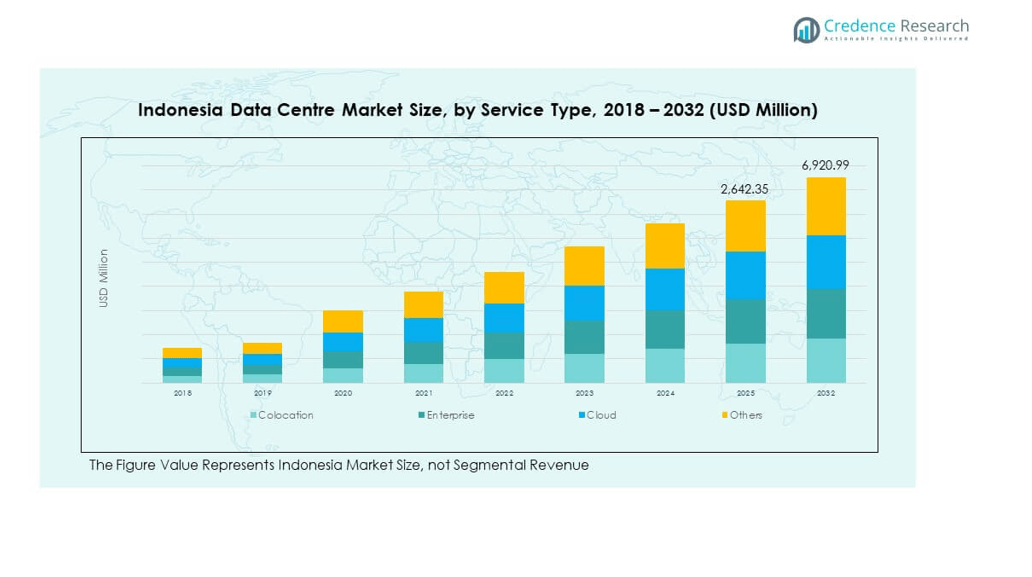
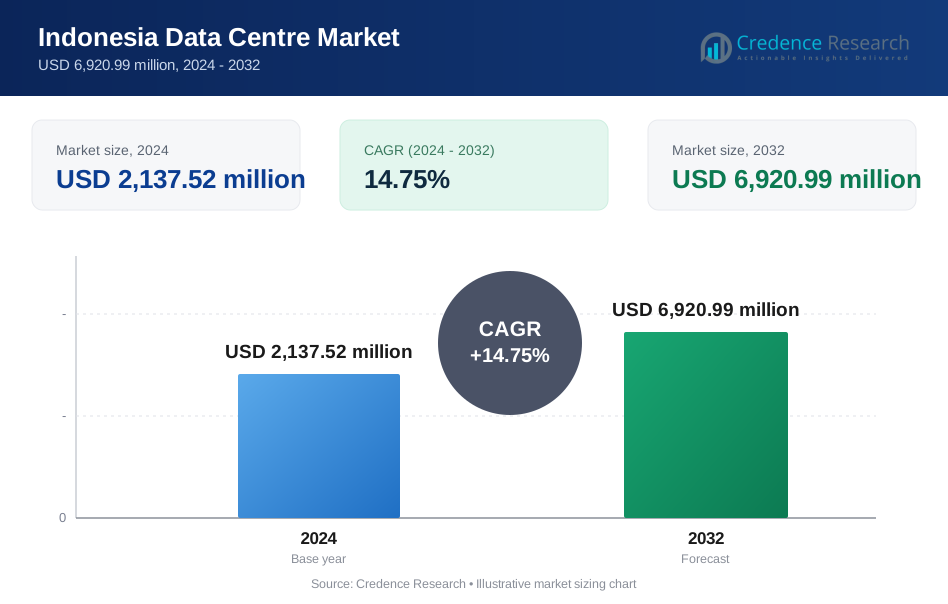
The Indonesia Data Centre Market size was valued at USD 1,044.10 million in 2018 to USD 2,137.52 million in 2024 and is anticipated to reach USD 6,920.99 million by 2032, at a CAGR of 14.75% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Indonesia Data Centre Market Size 2024 | USD 2,137.52 million |
| Indonesia Data Centre Market CAGR | 14.75% |
| Indonesia Data Centre Market Size 2032 | USD 6,920.99 million |
The market is expanding rapidly due to increasing internet penetration, rising demand for cloud-based services, and government initiatives promoting digital transformation. Strong growth in e-commerce, fintech, and content streaming industries further drives data processing and storage needs. Companies are investing in energy-efficient infrastructure, edge computing, and high-security solutions to support critical workloads. The rising focus on cybersecurity, along with the entry of global cloud providers, strengthens Indonesia’s position as a data hub in Southeast Asia.
Geographically, Jakarta remains the dominant hub due to its advanced infrastructure, high connectivity, and concentration of enterprises. Secondary cities such as Surabaya, Bandung, and Medan are emerging as attractive locations driven by growing industrial activities, improved connectivity, and regional digital expansion. International players are increasingly collaborating with local firms to expand capacity across these regions. This regional distribution is fostering balanced growth and enabling Indonesia to become a critical digital economy enabler in Southeast Asia.
Market Insights:
- The Indonesia Data Centre Market was valued at USD 1,044.10 million in 2018, reached USD 2,137.52 million in 2024, and is projected to hit USD 6,920.99 million by 2032, growing at a CAGR of 14.75%.
- Jakarta led with 65% share in 2024, driven by advanced connectivity and enterprise concentration, followed by Surabaya at 15% with industrial demand, and Bandung at 10% supported by start-ups and education networks.
- Medan, with 6% share, is the fastest-growing region, driven by trade, logistics, and expanding digital services.
- By service type, colocation services accounted for the largest portion with around 42% share in 2024, supported by demand for secure hosting and scalability.
- Cloud services followed with about 31% share in 2024, reflecting strong adoption by digital-first industries and enterprises moving toward hybrid and multi-cloud environments.
Market Drivers:
Rising Digital Transformation Across Enterprises and Public Sector:
The Indonesia Data Centre Market is expanding rapidly with enterprises and government institutions accelerating digital adoption. Organizations are modernizing IT infrastructures to support cloud migration and advanced analytics. This creates higher demand for storage capacity, efficient networks, and data security. Government initiatives focused on smart cities and e-governance also strengthen infrastructure needs. Businesses seek agility and reliability through colocation and cloud services. Large-scale digitization efforts across finance, retail, and healthcare further drive capacity expansion. It creates continuous growth opportunities for service providers in Indonesia.
- For instance, Abbott Laboratories reported increase in US medical device sales in H1 2025 based on advancements in medical devices facilitating integration of digital health, showing tangible growth from technology adoption in healthcare.
Rapid Growth in E-Commerce, Fintech, and Streaming Services:
The rise of digital-first industries is reshaping Indonesia’s data infrastructure demand. E-commerce platforms require robust systems for transaction handling, customer analytics, and logistics optimization. Fintech firms drive adoption of secure and scalable platforms to manage mobile payments and digital banking solutions. Streaming and online entertainment services create exponential data traffic. Providers are investing in high-bandwidth and low-latency solutions to meet consumer expectations. This trend accelerates the need for local data centres to improve efficiency and reduce reliance on foreign infrastructure. It supports a resilient ecosystem for Indonesia’s digital economy.
- For instance, Medtronic’s MiniMed™ 780G system achieved double-digit growth driven by AI-powered personalized automated insulin delivery, demonstrating the growing impact of high-throughput digital health technologies and data analytics in real-time care management.
Strong Demand for Cloud-Based Solutions and Edge Computing Adoption:
Cloud adoption is gaining traction across enterprises of all sizes in Indonesia. Companies seek flexible and scalable platforms to manage unpredictable workloads. The Indonesia Data Centre Market benefits from this transition as demand for hybrid and multi-cloud environments rises. Edge computing adoption further fuels growth by supporting real-time data processing close to end-users. Enterprises in manufacturing, retail, and telecom deploy edge solutions to optimize performance. Service providers enhance facilities with advanced connectivity and computing capacity. These advancements accelerate the adoption of modernized architectures that enhance reliability and scalability.
Government Support for Digital Infrastructure and Policy Initiatives:
National policies emphasize digitalization and encourage investments in critical ICT infrastructure. Government incentives for data sovereignty and compliance drive construction of local facilities. Regulatory requirements push companies to store and process data within Indonesia. This strengthens the domestic market by attracting global hyperscale operators. Public-private partnerships enhance sector growth through funding and infrastructure modernization. It builds investor confidence and accelerates entry of international service providers. Such strategic initiatives make Indonesia an attractive regional hub for digital services and data hosting.
Market Trends:
Expansion of Hyperscale Data Centres and Global Cloud Provider Entry:
Global hyperscale companies are investing in Indonesia to establish large-scale facilities. Their entry reflects the country’s growing digital economy and regional strategic value. These investments improve access to high-performance computing resources. The Indonesia Data Centre Market benefits from the enhanced capacity and advanced infrastructure offered by these players. Local providers are also collaborating with global firms to strengthen their market presence. The rise of hyperscale facilities addresses growing cloud and AI-driven workloads. It accelerates Indonesia’s role as a regional hub for Southeast Asia’s digital services.
- For instance, Dexcom’s integration of new AI features and enhanced connectivity in 2025 alongside partnerships with Omnipod®5 in multiple countries reflect the global collaborative ecosystem driving infrastructure demands for AI-enabled health devices.
Focus on Renewable Energy and Sustainable Infrastructure Development:
Sustainability is emerging as a critical trend shaping Indonesia’s data infrastructure strategy. Operators invest in renewable energy solutions to reduce carbon footprints and comply with green policies. Solar, wind, and hybrid power sources are increasingly integrated into facility design. The Indonesia Data Centre Market is witnessing strong interest in energy-efficient cooling and power distribution. These efforts support global ESG goals and appeal to environmentally conscious investors. Green certifications are becoming a competitive differentiator for providers. It ensures long-term operational efficiency and sustainability of large-scale operations.
- For instance, in November 2024, Omron Healthcare received FDA De Novo authorization for new home blood pressure monitors featuring AI-powered atrial fibrillation detection. This innovation is a significant step in digital health, enabling early detection of AFib during routine blood pressure checks.
Adoption of Artificial Intelligence and Automation in Data Centres:
AI-driven solutions are being adopted to enhance efficiency in Indonesian facilities. Operators deploy predictive analytics for cooling, energy management, and fault detection. Automation improves capacity planning and workload distribution across multiple systems. The Indonesia Data Centre Market is advancing toward intelligent infrastructure with reduced human intervention. This trend lowers costs while improving reliability and performance. AI-based monitoring enhances security by detecting anomalies in real time. It positions the market for advanced digital infrastructure aligned with global best practices.
Development of Secondary Data Centre Hubs Beyond Jakarta:
Jakarta remains dominant, but new hubs are emerging in Surabaya, Bandung, and Medan. These regions attract investments due to industrial development, improving connectivity, and regional demand. The Indonesia Data Centre Market benefits from diversification, reducing risks linked to overconcentration in one city. Enterprises in secondary hubs gain access to advanced digital infrastructure locally. This distribution helps reduce latency and improves service availability. Regional expansion encourages balanced growth and supports digital inclusion. It creates new opportunities for local and international service providers.
Market Challenges Analysis:
High Energy Costs, Infrastructure Limitations, and Power Reliability Concerns:
Data centres are energy-intensive, and Indonesia faces challenges in ensuring affordable and stable electricity. The Indonesia Data Centre Market requires consistent power supply to meet uptime standards. High operating costs linked to power and cooling infrastructure limit smaller players. Many regions still lack advanced grid capabilities, creating dependence on diesel backup systems. These constraints increase costs and affect long-term sustainability. Energy efficiency technologies are necessary but require significant investment. Providers must balance expansion with operational cost management and energy optimization.
Regulatory Complexity, Security Risks, and Skilled Workforce Shortage:
Strict regulations on data sovereignty and compliance can create barriers for international firms. The Indonesia Data Centre Market is also challenged by cybersecurity risks due to rising digital threats. Providers must ensure advanced protection against breaches, adding to operational complexity. A shortage of skilled professionals in IT and facility management further slows expansion. Talent gaps limit innovation and operational excellence in many regions. It drives dependence on foreign expertise, increasing project costs. Providers need long-term strategies for workforce training and capacity building.
Market Opportunities:
Rising Digital Adoption Across Enterprises and Regional Growth Prospects:
Digital transformation in enterprises offers significant opportunities for infrastructure providers. The Indonesia Data Centre Market is positioned to benefit from increasing adoption of hybrid cloud, IoT, and 5G applications. Emerging business hubs beyond Jakarta create strong potential for localized data hosting. Regional development ensures improved service delivery and reduced latency. Enterprises seek trusted partners for compliance, security, and scalable solutions. It strengthens the opportunity for domestic and global providers to expand.
Sustainability, Renewable Integration, and Growing Hyperscale Demand:
Green initiatives create opportunities for providers to differentiate through eco-friendly infrastructure. The Indonesia Data Centre Market is witnessing rising interest in renewable energy and energy-efficient systems. Hyperscale providers drive demand for large-scale, advanced facilities. Providers aligning with sustainability and high-capacity requirements gain competitive advantage. The convergence of digital growth and green priorities creates a long-term market opportunity. It positions Indonesia as a sustainable hub for data services in the region.
Market Segmentation Analysis:
By Service Type
Colocation services dominate demand as enterprises seek secure and scalable hosting solutions. Enterprise data centres follow, supporting businesses with tailored infrastructure and compliance needs. Cloud services are expanding rapidly, driven by digital-first industries and adoption of hybrid environments. Other services, including managed hosting, contribute to market diversity. The Indonesia Data Centre Market leverages these segments to address varied enterprise requirements.
- For instance, Withings launched Withings Intelligence in early 2025, delivering 24/7 AI-powered insights and clinical cardiologist reviews within 24 hours, highlighting cloud-based health data processing reflecting the rising demand for hybrid cloud and AI services.
By Type of Infrastructure
IT infrastructure forms the backbone, covering servers, storage, and networking equipment. Electrical infrastructure, including power systems and backup solutions, is critical to uptime and efficiency. Mechanical infrastructure such as cooling systems ensures operational stability in high-density environments. Other infrastructure components also add value by supporting sustainability goals. Each layer reinforces the market’s ability to deliver reliable digital services.
- For instance, AliveCor’s Kardia 12L ECG System, powered by AI, demonstrated performance parity with hospital-grade ECGs in January 2025, showing the critical role of integrated IT and medical device infrastructure in delivering high-assurance health data in clinical settings.
By Tier Type
Tier 3 facilities hold the largest share, balancing cost efficiency and redundancy. Tier 4 centres are growing steadily, appealing to enterprises requiring high resilience. Tier 2 and Tier 1 facilities serve smaller businesses with moderate needs. The Indonesia Data Centre Market adapts to varying levels of reliability demanded by different user groups.
By End User
BFSI leads demand, supported by digital banking and fintech expansion. Telecom and IT remain strong contributors due to cloud and connectivity growth. Media and entertainment, along with e-commerce, generate high data volumes requiring scalable solutions. Government and healthcare also invest heavily to modernize services. Other sectors contribute by adopting secure and localized infrastructure.
Segmentation:
By Service Type
- Colocation
- Enterprise
- Cloud
- Others
By Type of Infrastructure
- IT Infrastructure
- Electrical Infrastructure
- Mechanical Infrastructure
- Others
By Tier Type
- Tier 1
- Tier 2
- Tier 3
- Tier 4
By End User
- BFSI
- Telecom & IT
- Media & Entertainment
- E-Commerce
- Government & Healthcare
- Others
By Country
- Indonesia (country-wise revenue, service type, infrastructure, tier type, and end user)
Regional Analysis:
Jakarta: The Core Hub of Growth
Jakarta dominates the Indonesia Data Centre Market with a share of nearly 65%. The city benefits from robust connectivity, advanced infrastructure, and concentration of corporate headquarters. It attracts global hyperscale providers seeking a strategic entry point into Southeast Asia. High enterprise adoption of cloud, AI, and digital platforms strengthens its position. The government’s Smart City projects further stimulate demand for data infrastructure. It remains the central hub where investments continue to flow for colocation, cloud, and managed services.
Emerging Secondary Hubs: Surabaya, Bandung, and Medan
Surabaya holds close to 15% of the market, supported by its industrial base and rising regional enterprises. Bandung contributes nearly 10% through strong education networks, start-up ecosystems, and growing digital adoption. Medan accounts for about 6% as it leverages regional trade and logistics demand. The Indonesia Data Centre Market in these secondary hubs benefits from lower latency, localized services, and diversification from Jakarta’s concentration. It ensures enterprises gain improved accessibility while service providers expand their geographic footprint. These hubs are becoming attractive alternatives for new infrastructure development.
Future Regional Expansion and Balanced Growth
Other regions, including smaller cities and provinces, collectively represent around 4% of the market. Their contribution is expected to grow with ongoing improvements in connectivity, digital inclusion, and regional investments. The Indonesia Data Centre Market sees this expansion as critical for balancing infrastructure across the country. Service providers view regional growth as an opportunity to serve untapped enterprises and local governments. Demand for localized hosting and secure data management is increasing steadily. It strengthens Indonesia’s role as a scalable and inclusive digital economy.
Key Player Analysis:
- IDC Indonesia
- Telkom Indonesia (NeutraDC)
- ST Telemedia Global Data Centres
- EdgeConneX
- Keppel & Salim Group
- Princeton Digital Group (PDG)
- DayOne-INA
Competitive Analysis:
The Indonesia Data Centre Market is characterized by intense competition among global hyperscale providers and domestic players. International firms expand through large-scale investments, partnerships, and localized compliance strategies. Local operators strengthen positions by offering colocation, cloud services, and customized solutions tailored to regional enterprises. It benefits from collaborations that integrate advanced technologies such as edge computing, AI, and green energy. Companies compete by building energy-efficient facilities and ensuring compliance with data sovereignty regulations. Growing demand across industries enhances opportunities, creating a highly dynamic and competitive landscape.
Recent Developments:
- In July 2025, Omron Healthcare Singapore partnered with bolttech and QBE to launch the Premium Care subscription plan in Singapore, combining health monitoring with embedded insurance protection. This plan offers personalized health insights and cardiovascular protection to OMRON device users.
- In June 2025, Abbott Laboratories collaborated with Beta Bionics to integrate Beta Bionics’ iLet Bionic Pancreas with Abbott’s sensor technology. Abbott also partnered with the Department of Health in Abu Dhabi to support local pharmaceutical manufacturing, highlighting the company’s expansion in diabetes care and pharmaceutical capabilities.
- Medtronic advanced its partnership with Abbott by submitting FDA clearance applications in April 2025 for an interoperable insulin pump that will work exclusively with Abbott’s continuous glucose monitoring (CGM) platform. This collaboration expands the integration of Abbott’s CGM technology with Medtronic’s smart insulin delivery systems.
- A&D Medical integrated its cellular-enabled weight scale and blood pressure monitor with Impilo’s remote patient monitoring solution in January 2025, enhancing real-time data transmission and remote healthcare management capabilities.
Report Coverage:
The research report offers an in-depth analysis based on service type, infrastructure, tier, and end-user segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Hyperscale expansions will position Indonesia as a central hub in Southeast Asia’s digital ecosystem.
- Hybrid cloud adoption by enterprises will intensify demand for flexible and scalable services.
- Surabaya, Bandung, and Medan will emerge as alternative hubs beyond Jakarta.
- Edge computing will enable faster and more efficient deployment of latency-sensitive applications.
- Sustainability initiatives with renewable energy integration will drive greener infrastructure.
- Policies on data sovereignty will strengthen local compliance and attract global providers.
- Rising e-commerce, fintech, and digital entertainment sectors will boost data capacity needs.
- AI-driven systems will enhance operational efficiency, automation, and predictive management.
- Regional collaborations and global partnerships will improve competitiveness and service diversity.
- Ongoing digital transformation will secure long-term growth and infrastructure resilience.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Indonesia Data Center Market?
What factors are driving the growth of the Indonesia Data Center Market?
What are the key segments within the Indonesia Data Center Market?
What are some challenges faced by the Indonesia Data Center Market?
Which regions are emerging in the Indonesia Data Center Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Indonesia Data Centre Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Indonesia Data Centre Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,137.52 million → 2032: USD 6,920.99 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Indonesia Data Centre Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Indonesia Data Centre Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Indonesia Data Centre Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Indonesia Data Centre Market Drivers
- 3.3 Indonesia Data Centre Market Restraints & Challenges
- 3.4 Indonesia Data Centre Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Indonesia Data Centre Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Indonesia Data Centre Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Indonesia Data Centre category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Indonesia Data Centre Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Indonesia Data Centre Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Indonesia Data Centre market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Indonesia Data Centre Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Indonesia Data Centre Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Indonesia Data Centre Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Indonesia Data Centre (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Indonesia Data Centre Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Indonesia Data Centre Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Indonesia Data Centre Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Indonesia Data Centre Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Indonesia Data Centre Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Indonesia Data Centre Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Indonesia Data Centre Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Indonesia Data Centre Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Indonesia Data Centre Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
