
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Indonesia Processed Beef Product Market Size 2023 | USD 318.37 million |
| Indonesia Processed Beef Product Market, CAGR | 4.91% |
| Indonesia Processed Beef Product Market Size 2032 | USD 491.04 million |
Market Overview:
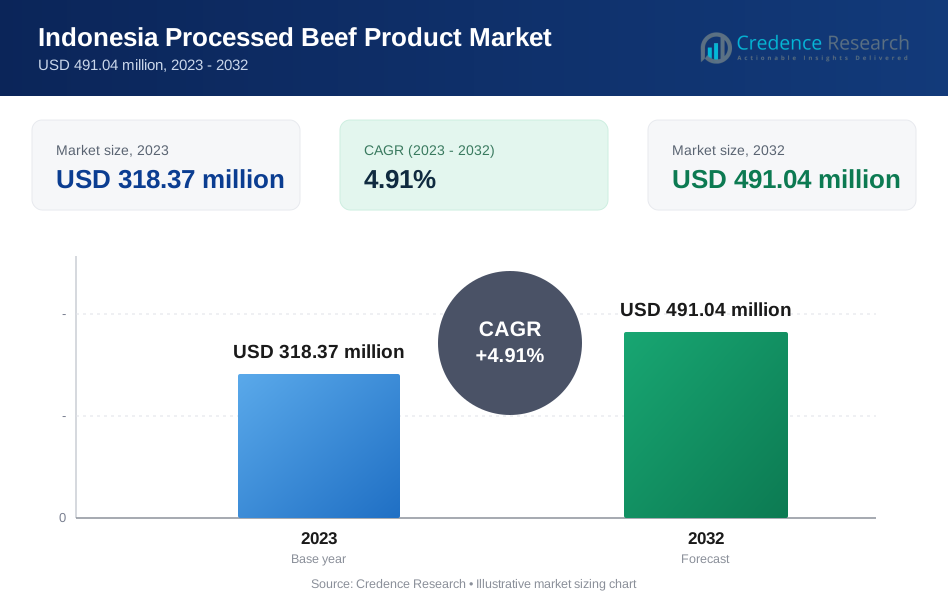
Indonesia Processed Beef Product Market size was valued at USD 318.37 million in 2023 and is anticipated to reach USD 491.04 million by 2032, at a CAGR of 4.91% during the forecast period (2023-2032).
The Indonesia processed beef product market is expanding rapidly due to evolving consumer preferences and the increasing adoption of convenience foods. The growing urban workforce and hectic lifestyles have driven demand for ready-to-eat (RTE), frozen, and processed meat products, particularly in metropolitan areas. Furthermore, rising disposable incomes are enabling consumers to opt for premium processed beef products, including sausages, deli meats, and marinated beef items. The rapid expansion of modern retail channels, such as supermarkets, hypermarkets, and e-commerce grocery platforms, has enhanced accessibility to these products, driving sales growth. Additionally, government initiatives aimed at strengthening domestic beef production, coupled with investments in advanced meat processing infrastructure, are expected to improve local supply and reduce reliance on imports. However, import dependency remains a challenge, as Indonesia sources a substantial portion of its beef from Australia and Brazil, making the market vulnerable to price fluctuations and global supply chain disruptions.
The Jakarta metropolitan area dominates the market, benefiting from a highly urbanized consumer base, strong retail presence, and well-established cold chain logistics. The region’s large working population, coupled with increasing demand for quick-service restaurants (QSRs) and food delivery services, continues to fuel the processed beef sector. Beyond Jakarta, West Java, East Java, and Bali represent high-growth regions, driven by urban expansion, tourism, and a flourishing hospitality industry. The tourism boom in Bali, in particular, has led to increased consumption of premium and specialty processed beef products in hotels, restaurants, and resorts. Meanwhile, Sumatra and Sulawesi are emerging as key growth markets, propelled by rising consumer purchasing power and improving retail infrastructure. The expansion of supermarkets and online grocery platforms in these areas is improving product availability, further accelerating market penetration. However, rural regions still face logistical and infrastructural challenges, particularly in cold storage and transportation, which hinder widespread distribution.
Market Insights:
- The Indonesia processed beef product market was valued at USD 318.37 million in 2023 and is projected to reach USD 491.04 million by 2032, growing at a CAGR of 4.91% during the forecast period.
- Rising demand for ready-to-eat (RTE) and frozen beef products is driven by urbanization, a growing workforce, and changing consumer lifestyles, particularly in metropolitan areas.
- The expansion of modern retail and e-commerce platforms has significantly improved accessibility to processed beef, with supermarkets, hypermarkets, and online grocery platforms playing a key role in market growth.
- Government initiatives and investments in domestic beef production and meat processing infrastructure aim to reduce reliance on imports, though import dependency remains a challenge due to sourcing from Australia and Brazil.
- The Jakarta metropolitan area dominates the market, benefiting from strong retail presence, a high urban population, and well-established cold chain logistics, while West Java, East Java, and Bali are emerging as key growth regions.
- Challenges such as price volatility, regulatory hurdles, and cold chain infrastructure limitations impact market expansion, particularly in rural areas and secondary cities.
- Premiumization of processed beef products is increasing, with rising demand for organic, halal-certified, and gourmet beef options, particularly in the foodservice and high-end retail segments.
Market Drivers:
Rising Demand for Convenience and Ready-to-Eat Products
The increasing preference for ready-to-eat (RTE) and processed meat products is a major driver of Indonesia's processed beef product market. Changing consumer lifestyles, driven by urbanization and a growing working population, have led to a surge in demand for convenient meal solutions that require minimal preparation. . For instance, a significant portion of consumers in Indonesia now favors frozen beef patties, sausages, and marinated cuts as they cater to busy schedules while providing high-protein meal options. Processed beef products, including frozen beef patties, sausages, canned beef, and marinated cuts, cater to busy consumers seeking quick and high-protein meal options. Additionally, the rapid growth of quick-service restaurants (QSRs), online food delivery services, and modern retail outlets has further accelerated the consumption of processed beef products across the country.
Expansion of Modern Retail and E-Commerce Platforms
The proliferation of supermarkets, hypermarkets, and e-commerce grocery platforms has significantly improved the accessibility and availability of processed beef products. Traditional wet markets remain a dominant distribution channel in Indonesia, but modern retail formats are rapidly gaining traction, particularly in urban and semi-urban areas. Supermarkets and convenience stores are increasingly offering branded and packaged processed beef products, which cater to a growing segment of consumers looking for quality assurance, extended shelf life, and convenience. Additionally, the rise of digital grocery shopping platforms has enabled consumers to purchase processed beef products online, contributing to sustained market growth. For example, many processed meat companies are implementing automated processing machines with enhanced hygiene controls to ensure safer production processes. The expansion of cold chain logistics and last-mile delivery services has further supported the e-commerce segment, ensuring the safe and efficient distribution of temperature-sensitive meat products.
Increasing Disposable Incomes and Changing Dietary Preferences
Indonesia’s rising middle-class population and increasing disposable incomes have contributed to a shift in dietary habits, with consumers showing a growing preference for high-protein and value-added meat products. As incomes rise, consumers are willing to spend more on premium processed beef products, including organic, halal-certified, and gourmet beef options. Additionally, global exposure through digital media and international travel has influenced consumer preferences, leading to increased demand for Western-style processed meat products such as deli meats, beef jerky, and burger patties. The foodservice sector, including casual dining chains, fast-food restaurants, and premium steak houses, is also witnessing higher demand for processed beef, further driving market expansion. For instance, the popularity of fast-food chains like McDonald's and KFC has risen significantly among the middle class, highlighting a shift towards convenience-oriented dining options.
Government Support and Investment in Meat Processing Infrastructure
The Indonesian government has implemented various policies and initiatives to boost domestic beef production and meat processing capabilities. Efforts to reduce the country’s reliance on imported beef have led to increased investments in local cattle farming, feedlot expansion, and modern meat processing facilities. Government-backed infrastructure projects, including cold storage development and improved transportation networks, are supporting the growth of the processed beef market. For instance, the Indonesian government is targeting beef self-sufficiency by 2026, with plans to develop cattle farms in regions such as Sulawesi and Kalimantan. This initiative includes a blue cattle breeding project from Belgium aimed at enhancing local cattle populations, which is expected to significantly contribute to domestic beef production. Additionally, regulatory measures such as strict halal certification requirements and food safety standards have encouraged producers to adopt advanced processing technologies and quality control measures. However, challenges remain, particularly in beef import dependency and fluctuating raw material costs, which continue to impact market stability. Nonetheless, ongoing government and private sector investments are expected to strengthen domestic beef processing capabilities and support long-term market growth.
Market Trends:
Growing Preference for Premium and Value-Added Processed Beef
Consumers in Indonesia are increasingly gravitating toward premium and value-added processed beef products, driven by rising disposable incomes and evolving dietary habits. The demand for organic, grass-fed, and preservative-free processed beef has gained traction, particularly among health-conscious and affluent consumers. Additionally, the market is witnessing a shift toward flavored and marinated beef products, such as spiced beef cuts, smoked beef, and gourmet burger patties, which cater to consumers seeking enhanced taste and convenience. Food manufacturers are responding to this trend by launching innovative products that appeal to changing consumer preferences, including artisanal-style beef sausages, nitrate-free deli meats, and protein-enriched beef snacks. For instance, companies like PT Japfa Comfeed Indonesia Tbk have shifted their focus to premium segments, offering products such as Tokusen Wagyu Beef to cater to affluent consumers seeking high-quality meat options.
Expansion of Halal-Certified Processed Beef Offerings
As a predominantly Muslim country, Indonesia has a strong demand for halal-certified processed beef products, with certification playing a crucial role in consumer purchasing decisions. The expansion of halal-compliant meat processing facilities and stringent regulatory oversight has encouraged both local and international players to invest in certified production processes. Major food manufacturers and retailers are emphasizing halal labeling and transparency in sourcing to build consumer trust. For instance, according to data from the Halal Product Assurance Organizing Agency (BPJPH), over 3.4 million products in Indonesia have been certified as halal from October 2019 to December 2023. Additionally, Indonesia’s position as a key player in the global halal food market has led to increased exports of processed halal beef to other Southeast Asian and Middle Eastern countries. This trend is expected to strengthen further, supported by government initiatives aimed at positioning Indonesia as a hub for halal food production and exports.
Rising Influence of Plant-Based and Alternative Protein Products
While processed beef remains a staple in Indonesian diets, the growing popularity of plant-based meat alternatives is beginning to shape market dynamics. Urban consumers, particularly younger demographics, are exploring flexitarian diets that incorporate both traditional beef products and plant-based protein alternatives. Food manufacturers are responding by developing hybrid meat products that blend beef with plant-based ingredients to cater to evolving consumer preferences. International and domestic brands are increasingly introducing meat substitutes, such as plant-based beef patties and soy-based beef jerky, which are gaining acceptance in niche markets. For example, in November 2022, Meatless Kingdom launched its Dendeng Manis Asap Plant Based snack, which mimics a traditional dried meat delicacy but uses plant-based ingredients. Although this trend is still in its early stages, it presents opportunities for industry players to diversify their product portfolios.
Integration of Smart Packaging and Cold Chain Innovations
Technological advancements in smart packaging and cold chain logistics are transforming the processed beef market in Indonesia. Manufacturers are adopting vacuum-sealed, modified atmosphere, and resealable packaging to extend product shelf life and maintain quality. Smart packaging solutions, such as QR codes for traceability and freshness indicators, are becoming more prevalent as consumers demand greater transparency in sourcing and storage conditions. Furthermore, improvements in cold chain infrastructure, particularly in secondary cities and rural areas, are enabling wider market penetration. For example, companies are implementing real-time temperature monitoring systems that help minimize spoilage during transportation, ensuring that processed beef products reach consumers in optimal condition. Investments in automated storage systems and temperature-controlled distribution networks are helping to reduce food wastage and improve supply chain efficiency, further supporting the growth of the processed beef sector in Indonesia.
Market Challenges Analysis:
High Dependence on Beef Imports and Price Volatility
One of the primary challenges facing the Indonesia processed beef product market is its significant reliance on imported beef, particularly from countries such as Australia, Brazil, and the United States. Domestic beef production remains insufficient to meet growing consumer demand, making the market highly vulnerable to fluctuations in global beef prices, trade restrictions, and currency exchange rates. Rising import costs and supply chain disruptions can lead to increased retail prices, affecting affordability for consumers and profitability for businesses. Additionally, government efforts to promote local cattle farming have yet to bridge the demand-supply gap, posing long-term sustainability concerns for the industry.
Regulatory Hurdles and Infrastructure Limitations
Stringent halal certification requirements, food safety regulations, and import restrictions create operational challenges for market players, particularly small and medium-sized enterprises (SMEs). Compliance with Indonesia’s strict halal standards necessitates additional investments in certified processing facilities, supply chain transparency, and regulatory approvals, which can be costly and time-consuming. Furthermore, inadequate cold chain infrastructure, especially in rural areas and secondary cities, limits market expansion and contributes to product spoilage risks. The lack of efficient refrigerated transport systems and storage facilities affects distribution efficiency, preventing processed beef products from reaching a broader consumer base. Addressing these infrastructure gaps will be crucial for the market’s long-term growth and competitiveness.
Market Opportunities:
Indonesia has a significant opportunity to enhance domestic beef production and processing infrastructure, reducing reliance on imports and improving market stability. Investments in cattle farming, feedlot expansion, and advanced meat processing technologies can strengthen local supply chains and support sustainable industry growth. Government initiatives promoting self-sufficiency in beef production, along with incentives for private sector investments, create a favorable environment for local producers to expand their operations. Additionally, the development of modern slaughterhouses and halal-certified processing facilities will enable companies to cater not only to domestic demand but also to growing export markets in Southeast Asia and the Middle East, where halal-certified processed beef is in high demand.
The increasing preference for high-quality, value-added processed beef products presents a lucrative opportunity for market players. The growing middle-class consumer base is driving demand for premium and gourmet beef options, including grass-fed, organic, and preservative-free products. Additionally, the rising popularity of protein-enriched and functional meat products, such as fortified beef snacks and hybrid meat-plant protein products, offers new growth avenues. Expanding distribution through e-commerce platforms and modern retail chains further enhances accessibility, allowing brands to reach urban consumers seeking convenience-oriented, ready-to-cook, and ready-to-eat beef options. By capitalizing on these evolving consumer preferences, market players can differentiate their offerings and capture a larger share of Indonesia’s dynamic processed beef market.
Market Segmentation Analysis:
The Indonesia processed beef product market is segmented by product, type, end-user, packaging, and distribution channel, each playing a crucial role in shaping industry dynamics and consumer demand.
By Product
The market is divided into cured processed beef, uncured processed beef, and others. Cured processed beef, which includes smoked and salted meat products, dominates the segment due to its extended shelf life and strong consumer preference for preserved meat options. Uncured processed beef is gaining traction among health-conscious consumers seeking products with minimal additives.
By Type
The demand for beef meat and mechanically recovered meat is rising, with burgers and sausages experiencing strong growth due to their popularity in quick-service restaurants (QSRs) and modern retail outlets. Skin, bones, ligaments, and tendons are primarily used in processed meat formulations, offering cost-effective options for manufacturers.
By End-User
The commercial/institutional segment, including restaurants, hotels, and catering services, holds a significant share due to high-volume consumption. The household/consumer segment is expanding, driven by the increasing preference for convenience-based and ready-to-cook beef products.
By Packaging
Fresh meat packaging remains dominant, while vacuum packaging and modified atmosphere packaging (MAP) are gaining popularity due to their ability to extend product shelf life and maintain quality. Innovations in sustainable and eco-friendly packaging solutions are also emerging.
By Distribution Channel
Retail channels, including supermarkets and hypermarkets, lead sales, while food service outlets drive bulk demand. E-commerce is expanding rapidly, providing consumers with greater accessibility to processed beef products through digital grocery platforms and home delivery services.
Segmentation:
By Product
- Cured Processed
- Uncured Processed
- Others
By Type
- Beef meat
- Mechanically recovered meat
- Burgers/sausages
- Skin, bones, ligaments and tendons
- Others
By End-user
- Commercial/Institutional
- Household/Consumers
By Packaging
- Fresh Meat Packaging
- Vaccum Packaging
- Modified Atmosphere packaging
By Distribution Channel
- Retail
- Food Services
- E-Commerce
Regional Analysis:
Jakarta Metropolitan Area: Dominant Market with High Consumption
The Jakarta metropolitan area accounts for the largest share of the Indonesia processed beef product market, contributing approximately 35-40% of total market sales. As the country’s economic hub, Jakarta has a high concentration of modern retail outlets, quick-service restaurants (QSRs), and premium grocery chains, making it the primary driver of demand for processed beef products. The region’s affluent and urban population exhibits strong preferences for ready-to-eat (RTE) beef products, deli meats, and premium beef options, contributing to sustained market growth. Additionally, the rise of e-commerce grocery platforms and the expansion of cold chain logistics have enhanced consumer accessibility, further reinforcing Jakarta’s position as the key demand center.
Java Region: Expanding Retail and Foodservice Sector
Regions outside Jakarta, particularly West Java and East Java, collectively represent around 30-35% of the market, driven by growing urbanization and the expansion of modern supermarkets and convenience stores. Cities such as Bandung, Surabaya, and Semarang are experiencing a surge in demand for processed beef, fueled by a rising middle-class population and an increasing number of fast-food chains and casual dining establishments. Additionally, Bali, a major tourist destination, has emerged as a key market for premium and specialty processed beef products, with hotels and high-end restaurants catering to both domestic and international visitors. The foodservice industry in these regions is a major contributor to processed beef consumption, with growing investment in hospitality and catering services further boosting demand.
Sumatra and Sulawesi: Emerging Growth Markets
Sumatra and Sulawesi, together contributing 15-20% of total market sales, are emerging as important growth regions due to increasing consumer purchasing power and expanding retail infrastructure. Key cities such as Medan, Palembang, and Makassar are witnessing rising demand for packaged and frozen beef products, supported by the growing presence of modern retail chains and improved cold storage facilities. The expansion of supermarkets and online grocery platforms in these regions has further facilitated market penetration. Additionally, government efforts to enhance transportation networks and cold chain logistics are expected to strengthen distribution channels, making processed beef more accessible in these growing markets.
Rural Areas and Eastern Indonesia: Market Expansion Challenges
Despite overall market growth, rural areas and Eastern Indonesia account for a smaller share, estimated at 10-15%, due to limited cold storage infrastructure and distribution networks. Challenges such as high logistics costs, inadequate refrigerated transport, and lower disposable incomes have hindered widespread adoption of processed beef products. However, ongoing investments in supply chain improvements, rural retail expansion, and government-backed infrastructure projects are expected to drive gradual market penetration. As affordability improves and distribution networks strengthen, these regions could offer untapped opportunities for future growth in the processed beef sector.
Key Player Analysis:
- JBS SA
- National Beef Packing Company, LLC
- American Foods Group, LLC.
- Agri Beef Co.
- Perdue Farms Inc.
- Tyson Foods, Inc
- Strauss Brands LLC
- Cargill, Incorporated
- Central Valley Meat
- Danish Crown A/S
- JS Ol Meat Co., Ltd
- Sunnong Life Co.,Ltd
- Company 13
- Company 14
Competitive Analysis:
The Indonesia processed beef product market is characterized by the presence of both domestic and international players, competing on factors such as product quality, pricing, distribution reach, and halal certification compliance. Leading market participants include local meat processing companies, multinational food corporations, and specialized halal beef producers, each leveraging their strengths to capture market share. Key players such as Japfa, and Belfoods dominate the domestic segment, benefiting from strong brand recognition and extensive distribution networks across supermarkets, convenience stores, and e-commerce platforms. For instance, So Good Food has established a strong presence in the domestic segment by focusing on high-quality processed meat products and utilizing extensive distribution networks across supermarkets and e-commerce platforms. Multinational companies, including CP Foods and NH Foods, compete by introducing premium, value-added, and Western-style beef products tailored to Indonesia’s growing middle-class consumer base. The increasing demand for ready-to-eat and frozen beef products has intensified competition, prompting companies to invest in innovative product formulations, packaging technology, and supply chain enhancements to strengthen their market position. Strategic partnerships and expansions in retail and foodservice sectors further drive competitive differentiation.
Recent Developments:
- Asiabeef Biofarmaannounced a strategic partnership with Agropecuaria 31 from Brazil on September 17, 2024. This collaboration aims to enhance Indonesia's dairy and meat production capabilities, with Brazil set to export 100,000 tropical dairy cattle to Indonesia.
- ADM(Archer Daniels Midland Company) has reached an agreement to acquire PT Trouw Nutrition Indonesia, a subsidiary of Nutreco, on December 2023.. This acquisition is expected to strengthen ADM's position in the animal nutrition sector by enhancing its premix production capabilities across Indonesia.
- On February 6, 2025, Cargill announced it had taken full control of SJC Bionergia. This acquisition highlights Cargill's continued expansion efforts in various agricultural sectors and aligns with their strategy to enhance sustainability practices.
Market Concentration & Characteristics:
The Indonesia processed beef product market exhibits a moderate to high market concentration, with a mix of large-scale domestic producers, multinational food companies, and regional players competing for market share. Leading brands such as So Good Food, Japfa, and Belfoods dominate the market due to their established distribution networks, extensive product portfolios, and compliance with strict halal regulations. While a few key players hold significant market share, new entrants and smaller regional processors are increasingly emerging, particularly in niche segments like premium halal-certified and organic processed beef products. The market is characterized by strong consumer demand for convenience, affordability, and quality assurance, driving innovation in ready-to-eat, frozen, and value-added beef products. Additionally, modern retail expansion and e-commerce growth are reshaping the competitive landscape, allowing more brands to reach consumers beyond traditional wet markets. Investments in cold chain logistics and supply chain efficiency are further strengthening market dynamics and accessibility.
Report Coverage:
The research report offers an in-depth analysis based on By Product, By Type, By End-user, By Packaging and By Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Indonesia processed beef product market is projected to grow steadily due to increasing urbanization, rising disposable incomes, and evolving consumer preferences.
- Demand for ready-to-eat and frozen beef products will continue to rise, driven by busy lifestyles and the need for convenience.
- Consumers are shifting towards premium and value-added processed beef, including organic, preservative-free, and gourmet options.
- Strengthened halal certification regulations and Indonesia’s positioning as a global halal food hub will drive exports and domestic market growth.
- The expansion of modern retail chains and e-commerce platforms will improve accessibility and market penetration.
- Advances in processing technology, smart packaging, and cold chain logistics will enhance product quality, shelf life, and supply efficiency.
- Competition will intensify, with major players expanding through acquisitions and new entrants focusing on niche segments.
- The growing popularity of plant-based and hybrid beef products may impact traditional processed beef demand.
- Government efforts to boost domestic cattle farming and reduce import dependency will strengthen local supply chains.
- Infrastructure challenges and price volatility in beef imports may pose risks to long-term market stability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Indonesia Processed Beef Product Market?
What factors are driving the growth of the Indonesia Processed Beef Product Market?
What are some challenges faced by the Indonesia Processed Beef Product Market?
Which region dominates the Indonesia Processed Beef Product Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Indonesia Processed Beef Product Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Indonesia Processed Beef Product Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 318.37 million → 2032: USD 491.04 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Indonesia Processed Beef Product Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Indonesia Processed Beef Product Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Indonesia Processed Beef Product Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Indonesia Processed Beef Product Market Drivers
- 3.3 Indonesia Processed Beef Product Market Restraints & Challenges
- 3.4 Indonesia Processed Beef Product Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Indonesia Processed Beef Product Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Indonesia Processed Beef Product Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Indonesia Processed Beef Product category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Indonesia Processed Beef Product Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Indonesia Processed Beef Product Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Indonesia Processed Beef Product market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Indonesia Processed Beef Product Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Indonesia Processed Beef Product Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Indonesia Processed Beef Product Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Indonesia Processed Beef Product (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Indonesia Processed Beef Product Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Indonesia Processed Beef Product Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Indonesia Processed Beef Product Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Indonesia Processed Beef Product Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Indonesia Processed Beef Product Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Indonesia Processed Beef Product Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Indonesia Processed Beef Product Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Indonesia Processed Beef Product Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Indonesia Processed Beef Product Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
