
Market Overview
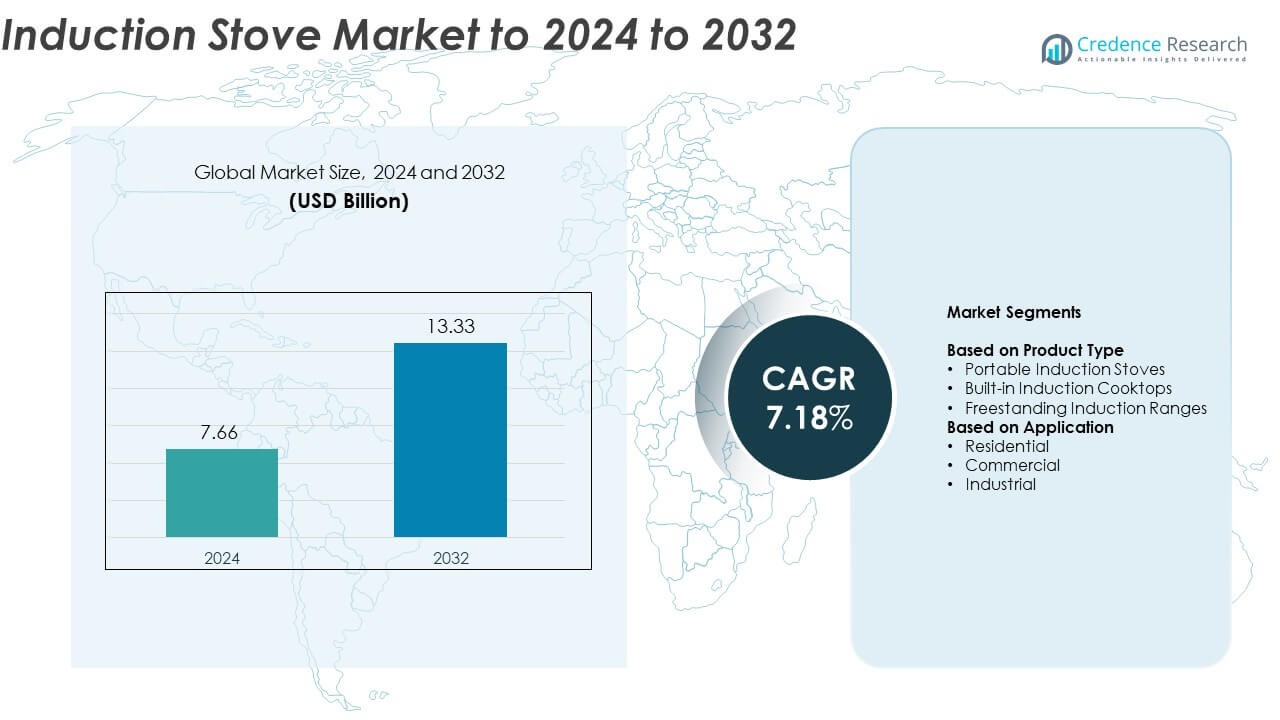
The Induction Stove Market size was valued at USD 7.66 Billion in 2024 and is anticipated to reach USD 13.33 Billion by 2032, at a CAGR of 7.18% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Induction Stove Market Size 2024 | USD 7.66 Billion |
| Induction Stove Market, CAGR | 7.18% |
| Induction Stove Market Size 2032 | USD 13.33 Billion |
Leading players such as LG Electronics, Philips Electronics, Haier Inc., Whirlpool Corporation, Robert Bosch GmbH, Electrolux AB, Miele & Cie. KG, Samsung, Fisher & Paykel Appliances Holdings Ltd., Midea, Panasonic Malaysia Sdn Bhd., and Daewoo Electronics Corporation are shaping the global induction stove market through innovation and design excellence. These companies focus on energy efficiency, user-friendly features, and connectivity integration to enhance performance and convenience. Asia Pacific leads the global market with a 43.6% share in 2024, followed by Europe with 28.3% and North America with 26.7%, driven by strong urbanization and technology adoption.
Market Insights
- The global induction stove market was valued at USD 7.66 billion in 2024 and is projected to reach USD 13.33 billion by 2032, growing at a CAGR of 7.18%.
- Rising demand for energy-efficient and eco-friendly cooking appliances is driving market expansion, supported by government initiatives promoting clean energy usage.
- The growing trend of smart kitchens and integration of IoT-enabled induction cooktops are enhancing convenience and user experience.
- The market is highly competitive, with players investing in innovation, design, and smart connectivity to strengthen their global footprint.
- Asia Pacific leads with a 43.6% share in 2024, followed by Europe at 28.3% and North America at 26.7%, while the built-in induction cooktops segment dominates with 55.9% share due to its compact and modern design appeal.
Market Segmentation Analysis:
By Product Type
The built-in induction cooktops segment dominates the global market, accounting for nearly 55.9% share in 2024. This leadership is driven by increasing consumer preference for sleek, space-saving kitchen designs and advanced cooking technologies. Built-in models offer seamless integration, enhanced energy efficiency, and features like touch sensors, timer settings, and automatic shut-off. Rising adoption in modern residential and commercial kitchens supports strong growth. Manufacturers are focusing on multi-zone configurations and smart connectivity, aligning with demand for efficient and sustainable cooking solutions worldwide.
- For instance, Miele’s PowerFlex zones deliver up to 7.3 kW booster output.
By Application
The residential segment leads the induction stove market, holding approximately 62.4% share in 2024. Growth in this segment is fueled by rising urbanization, increasing awareness of energy-efficient appliances, and a growing shift toward eco-friendly cooking methods. Consumers favor induction stoves for faster heating, precise temperature control, and safety compared to conventional gas stoves. Expanding smart home ecosystems and government programs promoting clean household energy further drive residential adoption. The segment continues to strengthen with innovations in compact and multi-burner product designs.
- For instance, IKEA’s LAGAN hob provides two zones at 2000 W and 1200 W.
Key Growth Drivers
Rising Demand for Energy-Efficient Cooking Solutions
The global shift toward energy efficiency is a major factor driving the induction stove market. Induction technology offers faster heating and reduced energy wastage compared to traditional gas or electric stoves. Governments promoting low-emission appliances and increasing electricity access in developing regions further support adoption. Consumers are increasingly favoring induction stoves for their precision, safety, and sustainability benefits, aligning with green building and smart home initiatives.
- For instance, GE Profile boils one quart in 101 seconds using a 3,700 W element.
Urbanization and Modern Kitchen Integration
Rapid urbanization and growing adoption of modular kitchens have fueled demand for built-in and portable induction stoves. Compact designs and aesthetic appeal make these appliances ideal for urban households with limited space. Rising disposable incomes and a growing middle-class population in emerging economies drive premium appliance purchases. Manufacturers are developing models with modern features like touch panels, Wi-Fi connectivity, and automatic power adjustment, enhancing convenience and user experience.
- For instance, Samsung launched Anyplace Induction with sheet-coil heating and AI Cook Manager at CES 2024.
Technological Advancements in Smart Cooking Systems
Advancements in sensor technology and IoT integration have transformed the induction stove market landscape. Smart induction stoves now feature adaptive heat control, app-based monitoring, and connectivity with virtual assistants. These innovations improve energy optimization and safety, attracting tech-savvy consumers globally. Increasing collaboration between appliance manufacturers and smart home ecosystem providers strengthens market expansion, enabling tailored cooking experiences and real-time energy management.
Key Trends & Opportunities
Growing Penetration of Smart Home Appliances
The increasing adoption of smart homes offers significant opportunities for induction stove manufacturers. Integration with AI and IoT platforms allows users to control cooking appliances remotely and customize settings for energy savings. The rise of connected kitchen ecosystems and digital lifestyle preferences encourages demand for advanced induction models equipped with voice control and predictive maintenance features.
- For instance, KitchenAid Temp Cook adds voice control and 120–400 °F presets across five zones.
Sustainability and Eco-Friendly Product Innovation
Manufacturers are focusing on developing induction stoves using recyclable materials and eco-friendly packaging. Energy-efficient components and sustainable production processes help reduce carbon footprints. Consumers are showing preference for brands emphasizing environmental responsibility and long-term cost savings. This trend supports a growing niche for green-certified kitchen appliances, driving sustainable innovation in the market.
- For instance, BSH has produced CO₂-neutral since 2020 and targets 300 GWh energy savings by 2030.
Key Challenges
High Initial Cost and Installation Barriers
Despite long-term energy savings, the high upfront cost of induction stoves remains a key challenge. Installation often requires compatible cookware and stable electrical infrastructure, limiting adoption in price-sensitive regions. The absence of standardized voltage systems and limited awareness in rural markets also hinder growth, especially in developing economies.
Competition from Conventional Cooking Technologies
The strong presence of gas and electric cooktops continues to challenge market penetration for induction stoves. Consumers in regions with low electricity access or higher power tariffs prefer traditional methods. Additionally, the perception of limited compatibility with existing cookware and maintenance concerns restricts widespread acceptance, particularly in cost-driven markets.
Regional Analysis
North America
North America holds nearly 26.7% share of the global induction stove market in 2024. The region’s growth is driven by increasing adoption of smart and energy-efficient kitchen appliances across households and restaurants. Consumers prefer induction technology for its faster cooking time, precision, and safety. The United States dominates due to strong awareness of sustainable living and high disposable income levels. Key market players are introducing Wi-Fi-enabled and app-controlled induction models to enhance convenience. Government initiatives supporting energy-efficient home appliances further strengthen market expansion across the region.
Europe
Europe accounts for about 28.3% share in 2024, supported by growing environmental awareness and strict energy efficiency regulations. Countries such as Germany, France, and the United Kingdom are leading adopters of induction stoves due to their advanced kitchen infrastructure and preference for clean cooking technologies. The region’s focus on reducing greenhouse gas emissions is driving the replacement of gas-based systems. Increasing consumer preference for premium built-in cooktops and compact designs aligns with modern kitchen trends. Rapid innovation and expansion of sustainable product portfolios by European manufacturers boost market growth.
Asia Pacific
Asia Pacific dominates the global induction stove market, capturing around 43.6% share in 2024. Rapid urbanization, rising household incomes, and expanding middle-class populations in China, India, and Japan are fueling demand. Consumers are shifting toward induction stoves for energy efficiency and safety advantages. Strong domestic manufacturing and product affordability further support adoption. Growing awareness of clean cooking and electrification initiatives by regional governments also play a crucial role. The availability of localized designs and multi-burner configurations continues to attract a wide consumer base across diverse income groups.
Latin America
Latin America represents approximately 8.4% share of the induction stove market in 2024. Brazil and Mexico are the key contributors, driven by increasing awareness of efficient cooking methods and modern home trends. Expanding urban populations and rising electricity access in rural areas encourage the adoption of induction appliances. However, higher product costs and limited consumer knowledge in lower-income segments pose challenges. Retail partnerships and product demonstrations are helping manufacturers boost brand visibility. The region is gradually transitioning toward energy-saving appliances, supported by ongoing economic recovery and improved import policies.
Middle East & Africa
The Middle East & Africa region holds nearly 6.1% share of the induction stove market in 2024. Market growth is supported by the rising adoption of premium kitchen appliances in urban centers and hospitality sectors. The United Arab Emirates, Saudi Arabia, and South Africa lead regional demand, driven by lifestyle modernization and energy efficiency initiatives. However, slower electricity infrastructure development in rural zones limits wider adoption. Global manufacturers are expanding distribution networks and introducing region-specific product lines to strengthen their presence, contributing to steady market growth across this region.
Market Segmentations:
By Product Type
- Portable Induction Stoves
- Built-in Induction Cooktops
- Freestanding Induction Ranges
By Application
- Residential
- Commercial
- Industrial
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The induction stove market features strong competition among major players such as LG Electronics, Philips Electronics, Haier Inc., Whirlpool Corporation, Robert Bosch GmbH, Electrolux AB, Miele & Cie. KG, Samsung, Fisher & Paykel Appliances Holdings Ltd., Midea, Panasonic Malaysia Sdn Bhd., and Daewoo Electronics Corporation. These companies compete through product innovation, technological advancement, and design efficiency to enhance cooking convenience and energy optimization. The market is witnessing a surge in smart induction cooktops with Wi-Fi connectivity, touch controls, and safety sensors. Manufacturers are investing in R&D to develop durable, energy-efficient, and eco-friendly models that cater to modern kitchen trends. Strategic partnerships with retailers and e-commerce platforms are helping to expand distribution networks. Companies are also focusing on sustainable manufacturing practices and region-specific product customization to strengthen brand loyalty and penetrate emerging markets. Continuous innovation in automation and smart cooking solutions remains central to maintaining a competitive edge globally.
Key Player Analysis
- LG Electronics
- Philips Electronics
- Haier Inc.
- Whirlpool Corporation
- Robert Bosch GmbH
- Electrolux AB
- Miele & Cie. KG
- Samsung
- Fisher & Paykel Appliances Holdings Ltd.
- Midea
- Panasonic Malaysia Sdn Bhd.
- Daewoo Electronics Corporation
Recent Developments
- In 2025, Haier Inc. Launched Series 4 and ID Series 6 smart induction hobs. Focus on pro-grade control and app features.
- In 2025, Samsung Unveiled Extractor Induction Hob for Europe at IFA 2025. Ventilation built into the cooktop.
- In 2025, Robert Bosch GmbH Introduced induction cooktops with integrated ventilation at IFA. XL Flex Zones and matte finish.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The induction stove market will continue to expand due to rising demand for energy-efficient appliances.
- Smart connectivity and IoT integration will enhance user convenience and operational efficiency.
- Manufacturers will focus on compact and modular designs to suit modern urban kitchens.
- Government initiatives promoting clean energy will drive adoption in developing regions.
- Growing consumer preference for eco-friendly and recyclable materials will influence product innovation.
- Online retail platforms will play a key role in expanding product accessibility and awareness.
- Technological advancements will lead to faster heating and better temperature precision.
- Increasing electrification in rural areas will create new growth opportunities for manufacturers.
- Premium induction stoves with AI-based controls will gain popularity among tech-savvy consumers.
- Competitive pricing strategies and regional manufacturing expansion will support long-term market growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Induction Stove Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Induction Stove Market projected to grow between 2025 and 2032?
Which Induction Stove Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Induction Stove Market?
Who are the leading companies in the Induction Stove Market?
Which region commanded the largest share of the Induction Stove Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7.66 billion → 2032: USD 13.33 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Induction Stove Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Induction Stove Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Induction Stove Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Induction Stove Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Induction Stove Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Induction Stove Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Induction Stove Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Induction Stove Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7.66 billion → 2032: USD 13.33 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Induction Stove Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Induction Stove Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Induction Stove Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Induction Stove Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

