
Market Overview:
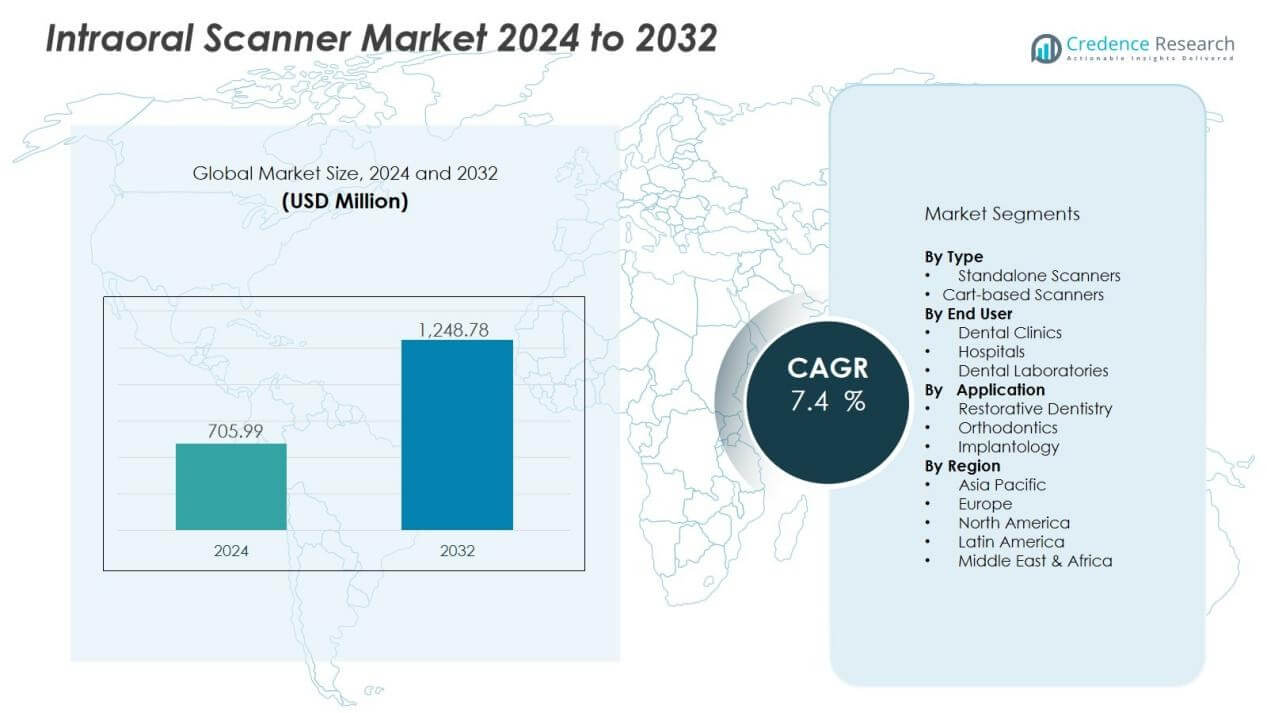
The intraoral scanner marketsize was valued at USD 705.99 million in 2024 and is anticipated to reach USD 1,248.78 million by 2032, at a CAGR of 7.4 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Intraoral Scanner Market Size 2024 | USD 705.99 Million |
| Intraoral Scanner Market, CAGR | 7.4% |
| Intraoral Scanner Market Size 2032 | USD 1,248.78 Million |
Growth in the intraoral scanner market is fueled by several drivers. Rising awareness of advanced dental imaging, increasing demand for cosmetic dentistry, and the need for time-efficient procedures are shaping demand. Technological advancements such as AI integration, enhanced 3D imaging, and user-friendly devices are further supporting adoption. In addition, the growing number of dental practices seeking to streamline operations and improve patient satisfaction continues to boost market momentum.
Regionally, North America holds a significant share due to advanced healthcare infrastructure, high adoption of digital technologies, and presence of leading manufacturers. Europe follows with strong uptake supported by rising cosmetic dental procedures and favorable reimbursement policies. Asia-Pacific is projected to record the fastest growth, driven by expanding healthcare access, growing dental tourism, and increasing investment in modern dental equipment in countries such as China and India.
Market Insights:
- The intraoral scanner market was valued at USD 705.99 million in 2024 and is expected to reach USD 1,248.78 million by 2032, growing at a CAGR of 7.4%.
- Rising demand for digital dentistry and patient comfort is driving adoption, replacing traditional impressions with accurate and faster scanning methods.
- Cosmetic and restorative dentistry applications, including crowns, bridges, implants, and aligners, are fueling consistent demand for scanners.
- Technological advancements such as AI integration, wireless models, and enhanced 3D imaging are improving workflow efficiency and diagnosis.
- Expanding dental infrastructure, higher healthcare spending, and awareness initiatives are strengthening adoption across clinics and hospitals.
- North America led the market with 38% share in 2024, supported by advanced healthcare systems and strong presence of manufacturers.
- Europe held 29% share in 2024 with Germany, France, and the U.K. driving growth through digital workflows and supportive healthcare policies.
- Asia-Pacific accounted for 23% share in 2024 and is projected to grow fastest, supported by dental tourism, healthcare investment, and rising awareness.
Market Drivers:
Rising Demand for Digital Dentistry and Patient Comfort:
The intraoral scanner market is expanding due to the growing shift toward digital dentistry. Dentists are replacing traditional impression methods with scanners that provide accuracy, speed, and patient comfort. Patients benefit from less invasive procedures, reducing discomfort and anxiety during treatments. It enables dental professionals to deliver improved clinical outcomes, which strengthens adoption across clinics and hospitals.
- For instance, 3Shape’s TRIOS 6 intraoral scanner, launched in 2025, offers up to 110% higher resolution than previous models, and weighs only 10.8 ounces, making it both highly accurate and comfortable for use in patient procedures.
Increasing Adoption in Cosmetic and Restorative Dentistry:
The growing interest in cosmetic and restorative dental procedures is boosting demand for intraoral scanners. These devices support precise imaging for crowns, bridges, implants, and aligners. Dentists value the accuracy and detail offered by scanners, ensuring better treatment planning and outcomes. The intraoral scanner market benefits from the rising need for aesthetic solutions and personalized care.
- For Instance, Medit's i500 scanner offers scan deviations significantly lower than 93 micrometers across multiple tests, supporting consistency and detail for digital prosthodontics. Its manufacturer-stated accuracy for single crowns is just 5.1 μm (±0.49 μm), and for full arches, it is 21.0 µm (±1.48 µm).
Technological Advancements and Integration of Artificial Intelligence:
Rapid innovation in scanner technology is transforming the market landscape. New models offer enhanced 3D imaging, wireless functionality, and AI-driven tools for faster and more accurate diagnosis. These improvements help dentists improve workflow efficiency and reduce chair time for patients. It creates significant opportunities for practices aiming to upgrade technology and attract more patients.
Expanding Dental Infrastructure and Growing Awareness:
Investment in dental infrastructure worldwide supports wider adoption of intraoral scanners. Expanding dental chains, increased healthcare spending, and greater awareness of oral health contribute to market growth. The intraoral scanner market is also benefiting from training programs that promote digital adoption among professionals. It ensures long-term demand by encouraging new dentists to embrace advanced imaging technologies early in their careers.
Market Trends:
Integration of Advanced Technologies and Enhanced Workflow Efficiency:
The intraoral scanner market is witnessing strong momentum through the integration of advanced technologies. Manufacturers are focusing on AI-powered tools, cloud-based data sharing, and improved software compatibility. These features help streamline workflow, reduce errors, and improve diagnostic accuracy. Dentists benefit from faster chairside procedures and seamless collaboration with dental laboratories. It also supports the trend toward same-day dentistry, where patients can receive faster treatments without multiple visits. Growing demand for precision and efficiency continues to push clinics toward adopting modern scanners with advanced imaging and data management capabilities.
- For Instance, The Align Technology iTero Element 5D Plus intraoral scanner can complete a full-arch scan in as little as 60 seconds with an experienced operator, which enables a significantly faster digital impression process.
Rising Adoption Across Emerging Markets and Growth of Dental Tourism:
The intraoral scanner market is expanding significantly in emerging economies due to improving healthcare infrastructure and rising disposable incomes. Countries in Asia-Pacific and Latin America are experiencing growing adoption, supported by dental tourism and government investment in healthcare modernization. Dental clinics in these regions are embracing scanners to attract international patients seeking cost-effective yet high-quality care. It reflects a global trend where patient expectations align with advanced digital practices. Increasing awareness about oral health and the availability of training for digital tools are also strengthening demand. The combination of affordability and advanced care drives growth across new geographies, expanding the market’s global reach.
- For instance, 3Shape introduced the TRIOS 5 Wireless intraoral scanner in September 2022, featuring ScanAssist intelligent alignment technology for faster scanning and enhanced imaging quality.
Market Challenges Analysis:
Integration of Advanced Technologies and Enhanced Workflow Efficiency:
The intraoral scanner market is witnessing strong momentum through the integration of advanced technologies. Manufacturers are focusing on AI-powered tools, cloud-based data sharing, and improved software compatibility. These features help streamline workflow, reduce errors, and improve diagnostic accuracy. Dentists benefit from faster chairside procedures and seamless collaboration with dental laboratories. It also supports the trend toward same-day dentistry, where patients can receive faster treatments without multiple visits. Growing demand for precision and efficiency continues to push clinics toward adopting modern scanners with advanced imaging and data management capabilities.
Rising Adoption Across Emerging Markets and Growth of Dental Tourism:
The intraoral scanner market is expanding significantly in emerging economies due to improving healthcare infrastructure and rising disposable incomes. Countries in Asia-Pacific and Latin America are experiencing growing adoption, supported by dental tourism and government investment in healthcare modernization. Dental clinics in these regions are embracing scanners to attract international patients seeking cost-effective yet high-quality care. It reflects a global trend where patient expectations align with advanced digital practices. Increasing awareness about oral health and the availability of training for digital tools are also strengthening demand. The combination of affordability and advanced care drives growth across new geographies, expanding the market’s global reach.
Market Opportunities:
Expansion in Emerging Markets and Growth of Dental Tourism:
The intraoral scanner market holds strong opportunities in emerging economies where dental infrastructure is rapidly improving. Rising disposable incomes, growing healthcare investment, and expanding awareness of digital dentistry are fueling adoption. Clinics in Asia-Pacific, Latin America, and the Middle East are increasingly adopting scanners to attract both domestic and international patients. Dental tourism, particularly in countries like India, Thailand, and Mexico, is boosting demand for modern dental equipment. It allows practices to deliver high-quality, cost-effective care that appeals to global patients. These regions are expected to drive significant future growth for the market.
Technological Advancements and Integration with Broader Digital Dentistry Ecosystem:
Continuous innovation creates new opportunities for intraoral scanner adoption across diverse applications. Integration with CAD/CAM systems, 3D printing, and AI-powered diagnostics enhances treatment accuracy and efficiency. The intraoral scanner market benefits from this trend by aligning with the growing demand for same-day dentistry and personalized care. It also supports better collaboration between dental professionals and laboratories through cloud-based platforms. Ongoing product development focused on affordability and portability will further broaden accessibility. These advancements position scanners as essential tools in the future of digital dentistry.
Market Segmentation Analysis:
By Type:
The intraoral scanner market is segmented into standalone and cart-based systems. Standalone scanners dominate due to their portability, ease of use, and growing demand among small and mid-sized dental practices. Cart-based systems maintain relevance in larger clinics and hospitals where advanced features and integration with other devices are critical. It reflects a clear shift toward compact solutions that align with evolving clinical needs.
- For instance, Align Technology's iTero Element Plus, a standalone scanner, reached an installed base of 73,000 units worldwide as of the first quarter of 2022, reflecting its high adoption and operational efficiency in diverse dental settings.
By Application:
Key applications include restorative dentistry, orthodontics, and implantology. Restorative dentistry holds a leading position with strong demand for crowns, bridges, and veneers requiring high precision. Orthodontics is expanding rapidly, supported by growing use of aligners and personalized treatments. Implantology also contributes significantly, with scanners enabling accurate surgical planning and improved patient outcomes. The intraoral scanner market continues to strengthen across these applications by supporting precision and efficiency.
- For instance, Dentsply Sirona’s Primescan achieves a local trueness of 14 μm in single-tooth preparations.
By End-user:
End-users include dental clinics, hospitals, and dental laboratories. Dental clinics represent the largest share due to widespread adoption of digital tools for routine and cosmetic procedures. Hospitals increasingly use scanners to support complex cases and multidisciplinary treatment plans. Laboratories benefit from digital impressions that streamline production and reduce turnaround time. It ensures each end-user segment drives consistent adoption, reinforcing scanners as essential tools in modern dental workflows.
Segmentations:
By Type
- Standalone Scanners
- Cart-based Scanners
By Application
- Restorative Dentistry
- Orthodontics
- Implantology
By End-user
- Dental Clinics
- Hospitals
- Dental Laboratories
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America:
North America accounted for 38% market share in 2024, leading the global intraoral scanner market. The region benefits from advanced healthcare infrastructure, high awareness, and strong presence of key manufacturers. U.S. dental clinics and laboratories are rapidly transitioning to digital workflows, driving consistent demand. It is supported by favorable reimbursement policies and rising demand for cosmetic dentistry. The presence of established players ensures continuous product innovation and training opportunities for professionals. Growth in this region remains steady, backed by patient demand for efficient and comfortable procedures.
Europe:
Europe held 29% market share in 2024, supported by strong adoption across both Western and Eastern countries. The intraoral scanner market in Europe benefits from increasing demand for restorative and cosmetic dental procedures. Countries such as Germany, France, and the U.K. are leading with widespread use of CAD/CAM systems and digital workflows. It is further supported by government-backed healthcare initiatives that promote modern technologies. Dental laboratories in the region are also adopting scanners to improve accuracy and speed of service. The growing preference for advanced dental solutions continues to sustain market expansion across Europe.
Asia-Pacific:
Asia-Pacific captured 23% market share in 2024 and is projected to grow at the fastest pace. The intraoral scanner market in this region benefits from strong healthcare investment and expanding dental infrastructure. China, India, and Japan are driving growth through large patient pools and rising demand for modern dental care. It is supported by growing dental tourism, particularly in cost-competitive markets offering advanced treatments. Increasing disposable incomes and heightened awareness of oral health strengthen adoption in urban centers. Manufacturers are also targeting this region with affordable and portable scanner models to reach a wider customer base.
Key Player Analysis:
- 3Shape AS
- Align Technology Inc.
- Densys Ltd.
- Denterprise International Inc.
- Dentsply Sirona Inc.
- Durr Dental SE
- Envista Holdings Corp.
- GC Corp.
- Glidewell
- Guangdong Launca Medical Device Technology Co. Ltd.
Competitive Analysis:
The intraoral scanner market is highly competitive with leading players driving innovation and adoption. Major companies include 3Shape AS, Align Technology Inc., Densys Ltd., Denterprise International Inc., Dentsply Sirona Inc., Durr Dental SE, Envista Holdings Corp., and GC Corp. These players focus on enhancing scanning accuracy, improving user interfaces, and integrating advanced imaging technologies. It is shaped by continuous product launches, strategic partnerships, and expanding global distribution networks. Companies are also investing in AI-driven software and cloud-based platforms to strengthen workflow efficiency and collaboration. The market rewards firms that can deliver affordability without compromising performance, catering to both advanced clinics and cost-sensitive practices. Strong brand reputation, training support, and after-sales services remain critical competitive factors. With growing demand for digital dentistry, leading players aim to expand their global reach and capture long-term growth opportunities in both developed and emerging regions.
Recent Developments:
- In March 2025, 3Shape AS launched the TRIOS 6 scanner, featuring the TRIOS Dx Plus diagnostic software and Dental Health patient app, transforming the intraoral scanner into a patient-centered diagnostic platform.
- In May 2025, Align Technology Inc. received regulatory approval to launch the 3D-printed Invisalign Palatal Expander System in China for commercial release in the second half of 2025.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application, End-user and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The intraoral scanner market will witness strong adoption with growing demand for digital dentistry.
- Rising focus on patient comfort and faster chairside procedures will drive steady uptake.
- Technological advances such as AI-powered imaging and cloud-based platforms will enhance efficiency.
- Integration with CAD/CAM and 3D printing will expand applications across dental practices and laboratories.
- Growing demand for same-day dentistry solutions will push clinics to invest in advanced scanners.
- Emerging economies will provide significant opportunities supported by rising healthcare investments and dental tourism.
- Manufacturers will prioritize developing affordable, compact, and portable models to reach wider customer bases.
- Greater emphasis on interoperability and secure data handling will improve trust and collaboration in digital workflows.
- Training initiatives for dental professionals will accelerate adoption and strengthen market penetration worldwide.
- The intraoral scanner market will evolve as an essential part of modern dentistry, shaping long-term growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Shift Toward Digital Dentistry and Patient Comfort
Dental professionals are increasingly adopting intraoral scanners to replace traditional impression methods, offering greater accuracy, speed, and a more comfortable experience for patients. This shift is driven by the need for less invasive procedures and improved clinical outcomes, fueling widespread adoption in clinics and hospitals.
Growth in Cosmetic and Restorative Dental Procedures
Rising demand for crowns, bridges, implants, and aligners is boosting the need for precise digital impressions, which intraoral scanners provide. The trend toward personalized and aesthetic dental solutions is driving consistent market growth as practitioners seek tools that enhance treatment planning and outcomes.
Technological Advancements and AI Integration
Continuous innovation, including AI-powered diagnostics, enhanced 3D imaging, and wireless models, is making intraoral scanners more efficient and user-friendly. These advancements streamline workflows, reduce chair time, and improve diagnostic accuracy, encouraging more dental practices to invest in modern scanning solutions.
Expansion of Dental Infrastructure and Awareness
Global investment in dental infrastructure, especially in emerging markets, is increasing access to advanced dental technologies. Awareness campaigns and professional training programs are accelerating the adoption of intraoral scanners, particularly among new dental practitioners.
Rising Dental Tourism and Healthcare Investment in Emerging Markets
Countries in Asia-Pacific and Latin America are experiencing rapid growth in dental tourism and healthcare modernization, prompting clinics to adopt intraoral scanners to attract international patients. This trend is expanding the market’s global reach and driving adoption in cost-competitive regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the intraoral scanner market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the intraoral scanner market projected to grow between 2024 and 2032?
Which intraoral scanner market segment held the largest share in 2024?
What are the primary factors fueling the growth of the intraoral scanner market?
Who are the leading companies in the intraoral scanner market?
Which region commanded the largest share of the intraoral scanner market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Standalone Scanners
- 1.2.2 Cart-based Scanners
- 1.3 By End-user
- 1.3.1 Dental Clinics
- 1.3.2 Hospitals
- 1.3.3 Dental Laboratories
- 1.4 By Application
- 1.4.1 Restorative Dentistry
- 1.4.2 Orthodontics
- 1.4.3 Implantology
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 705.99 million → 2032: USD 1,248.78 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Intraoral Scanner Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Intraoral Scanner Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Intraoral Scanner Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Intraoral Scanner Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Intraoral Scanner Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Intraoral Scanner Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Intraoral Scanner Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Intraoral Scanner Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 705.99 million → 2032: USD 1,248.78 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Intraoral Scanner Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Standalone Scanners
- 12.3.7.2 Cart-based Scanners
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-user - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Dental Clinics
- 12.4.7.2 Hospitals
- 12.4.7.3 Dental Laboratories
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Restorative Dentistry
- 12.5.7.2 Orthodontics
- 12.5.7.3 Implantology
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Intraoral Scanner End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Intraoral Scanner Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Intraoral Scanner Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Intraoral Scanner Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 3Shape AS
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Align Technology Inc.
- 18.4 Densys Ltd.
- 18.5 Denterprise International Inc.
- 18.6 Dentsply Sirona Inc.
- 18.7 Durr Dental SE
- 18.8 Envista Holdings Corp.
- 18.9 GC Corp.
- 18.10 Glidewell
- 18.11 Guangdong Launca Medical Device Technology Co. Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

