
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Italy Managed Services Market Size 2023 | USD 10,273.25 million |
| IItaly Managed Services Market, CAGR | 5.79% |
| Italy Managed Services Market Size 2032 | USD 17,048.34 million |
Market Overview
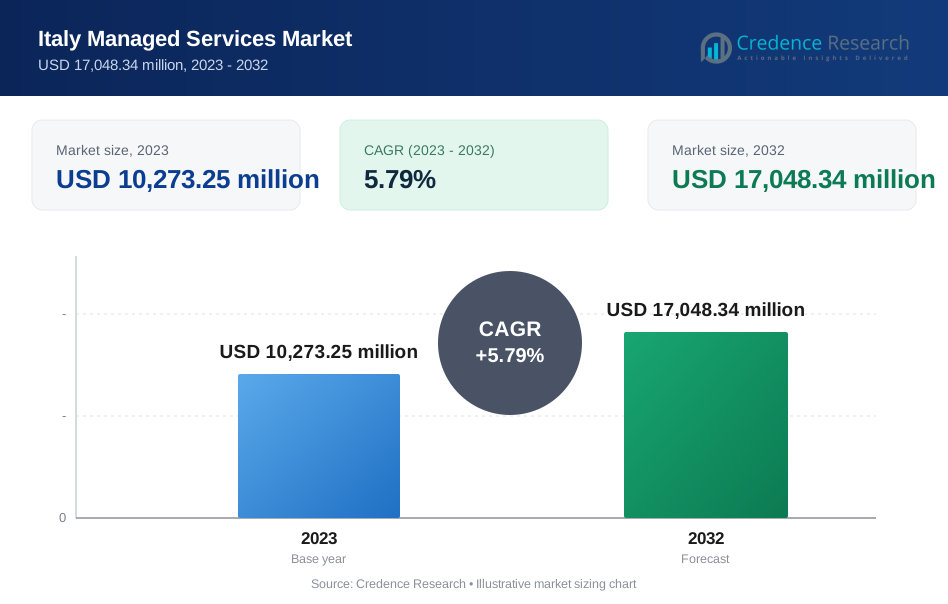
The Italy Managed Services Market is expected to grow from USD 10,273.25 million in 2023 to USD 17,048.34 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.79%.
The Italy Managed Services market is driven by the increasing demand for IT outsourcing as businesses seek cost-effective and efficient solutions to manage their infrastructure and operations. As digital transformation accelerates across industries, organizations are increasingly relying on managed service providers (MSPs) for cloud computing, cybersecurity, data management, and network services. Additionally, the growing adoption of advanced technologies like artificial intelligence (AI), machine learning (ML), and automation is pushing businesses to outsource specialized services to MSPs with expertise in these areas. The shift towards remote and hybrid work environments is also contributing to the demand for managed services to ensure seamless IT operations and support. Furthermore, the need for enhanced security measures in the face of rising cyber threats is compelling organizations to leverage the expertise of MSPs, fueling market growth. These factors, combined with a growing focus on scalability and flexibility, are shaping the future of Italy's Managed Services market.
Italy's Managed Services market is driven by regional differences, with Northern Italy, including cities like Milan, Turin, and Venice, seeing the highest demand due to its strong industrial and financial sectors. Southern Italy, including Naples, Palermo, and Bari, is gradually increasing its adoption of managed services, particularly in sectors like healthcare and small businesses. Central Italy, with hubs such as Rome and Florence, also shows notable growth, especially in government and tourism-related services. Key players in the market include global giants like IBM Corporation, Accenture, Microsoft, and Google, which provide a wide range of IT infrastructure, cloud, and security solutions. Local companies such as Zettagrid Italy, Sintra Digital Business, and Techlane are also gaining traction by offering specialized services tailored to the regional needs of businesses. These key players are enhancing the digital transformation journey across various industries in Italy through innovative and reliable managed services.
Market Insights
- The Italy Managed Services market is valued at USD 10,273.25 million in 2023 and is expected to reach USD 17,048.34 million by 2032, growing at a CAGR of 5.79%.
- Increasing demand for IT outsourcing and cost-effective solutions is a key driver in the market.
- The shift towards cloud-based services and hybrid IT solutions is driving substantial growth in the sector.
- Adoption of artificial intelligence (AI) and automation tools by managed service providers is a key trend.
- Cybersecurity concerns and the rising frequency of data breaches are pushing businesses toward managed security services.
- The competitive landscape is shaped by global players like IBM, Accenture, and Microsoft, alongside regional players such as Zettagrid Italy and Techlane.
- Regional demand varies, with Northern Italy seeing the highest adoption, while Southern and Central regions are witnessing gradual growth in managed service adoption.
Market Drivers
Increasing Demand for IT Outsourcing
One of the primary drivers of the Italy Managed Services market is the growing demand for IT outsourcing. As businesses face the challenge of maintaining and upgrading their IT infrastructure, many are turning to managed service providers (MSPs) to reduce operational costs and improve efficiency. Outsourcing IT functions such as cloud services, network management, and data storage allows organizations to focus on their core competencies while benefiting from the expertise and resources of MSPs. This shift is expected to continue as companies increasingly look for scalable and flexible solutions to meet their IT needs.
Digital Transformation and Technological Advancements
The ongoing digital transformation across various industries is another significant driver of the managed services market in Italy. As organizations adopt new technologies like cloud computing, big data, and artificial intelligence (AI), they require specialized support and expertise. For instance, Italy's Recovery and Resilience Plan (PNRR) includes significant investments in digital initiatives to accelerate the adoption of emerging technologies. Managed service providers offer the technical knowledge needed to integrate these technologies effectively, enabling businesses to stay competitive and innovative. The rising demand for automation and digitalization in industries such as manufacturing, finance, and retail is further accelerating the need for managed services.
Shift Toward Remote and Hybrid Work Models
The global shift to remote and hybrid work models has had a significant impact on the demand for managed services in Italy. With employees working from various locations, businesses need reliable IT infrastructure and support to ensure smooth operations. For instance, a study by Indeed found that the share of job advertisements in Italy offering remote and hybrid work options has significantly increased since the pandemic. Managed service providers are crucial in enabling remote work by offering services like secure cloud access, virtual collaboration tools, and continuous IT monitoring. As remote and hybrid work models become permanent fixtures, the reliance on MSPs for IT management and support is expected to increase, further driving market growth.
Rising Cybersecurity Threats
The increasing frequency and sophistication of cyberattacks are driving the demand for managed security services in Italy. With businesses handling sensitive data and operating in highly regulated environments, the need for robust cybersecurity measures has never been more critical. Managed service providers offer advanced threat detection, data protection, and compliance management services, which help organizations mitigate risks and ensure business continuity. As cyber threats evolve, the reliance on MSPs to safeguard digital assets and networks will continue to grow.
Market Trends
Increased Adoption of Cloud-Based Managed Services
A key trend in the Italy Managed Services market is the growing adoption of cloud-based solutions. As businesses move towards digital transformation, cloud computing offers greater flexibility, scalability, and cost efficiency. Managed service providers (MSPs) are capitalizing on this shift by offering tailored cloud services, including cloud infrastructure management, cloud security, and cloud storage. The demand for hybrid and multi-cloud environments is also rising as companies seek to optimize their IT resources. This trend is expected to accelerate as more organizations recognize the advantages of leveraging cloud technologies for their operations.
Integration of Artificial Intelligence and Automation
The integration of artificial intelligence (AI) and automation is another prominent trend shaping the managed services landscape in Italy. MSPs are incorporating AI-powered tools to enhance service delivery, streamline processes, and provide predictive analytics. For instance, the Italian Ministry of Economic Development's National AI Strategy outlines significant investments to foster AI research and innovation, aiming to enhance the competitiveness of Italian enterprises. Automation helps businesses reduce manual tasks, improve efficiency, and mitigate human errors, especially in areas such as IT monitoring, system updates, and data analysis. As AI continues to evolve, its role in managed services will expand, driving further market growth and offering businesses more advanced and intelligent IT solutions.
Emphasis on Cybersecurity Services
With the increasing prevalence of cyber threats, there is a growing focus on cybersecurity services within the Italy Managed Services market. Companies are becoming more aware of the risks associated with data breaches, ransomware, and other cyberattacks, leading to an increased reliance on MSPs to safeguard their networks. Managed security services such as threat detection, vulnerability assessments, and incident response are gaining traction. As businesses navigate the complexities of cybersecurity, the demand for specialized expertise in this area is expected to rise, further fueling the market's expansion.
Focus on Industry-Specific Solutions
Another emerging trend is the growing demand for industry-specific managed services. MSPs are increasingly offering customized solutions tailored to the unique needs of different sectors, including healthcare, finance, manufacturing, and retail. By providing specialized services such as regulatory compliance support, data privacy management, and sector-specific IT infrastructure, managed service providers can better address the distinct challenges faced by businesses in these industries. This trend is likely to continue as organizations seek more targeted and relevant solutions to meet their operational and regulatory requirements.
Market Challenges Analysis
Talent Shortage and Skill Gaps
One of the primary challenges facing the Italy Managed Services market is the shortage of skilled IT professionals. As businesses increasingly rely on managed service providers (MSPs) for complex IT solutions, the demand for professionals with expertise in cloud computing, cybersecurity, and artificial intelligence (AI) is rising. However, there is a significant gap in the availability of qualified talent to meet this demand. This shortage of skilled workers can result in delays in service delivery, higher recruitment costs, and difficulty in maintaining service quality. To address this, MSPs must invest in talent acquisition and training programs, which can strain resources and affect profitability. The talent shortage may also hinder the ability of MSPs to scale rapidly in line with growing market demand.
Data Privacy and Regulatory Compliance Challenges
Another challenge for the Italy Managed Services market revolves around the complex regulatory environment, particularly in terms of data privacy and compliance. Italy, being part of the European Union, is subject to stringent data protection laws, such as the General Data Protection Regulation (GDPR). As managed service providers handle sensitive business and customer data, they must navigate the evolving landscape of privacy laws and ensure compliance with these regulations. For instance, the Italian Data Protection Code, which integrates the GDPR, imposes strict requirements on data handling and protection. Failure to meet compliance standards can result in hefty fines and reputational damage. Furthermore, managing cross-border data flow while adhering to local regulations presents an additional layer of complexity for MSPs. This regulatory burden requires continuous investment in compliance processes, technologies, and expertise, which can challenge the profitability and scalability of managed services in the market.
Market Opportunities
Expansion of Cloud and Hybrid IT Solutions
One of the most significant opportunities in the Italy Managed Services market lies in the growing demand for cloud and hybrid IT solutions. As businesses continue to embrace digital transformation, they seek more flexible, scalable, and cost-effective IT infrastructures. Managed service providers (MSPs) can capitalize on this shift by offering tailored cloud services, including cloud storage, cloud migration, and hybrid cloud management. The increasing adoption of multi-cloud strategies by businesses further opens up opportunities for MSPs to deliver customized solutions that optimize performance, enhance security, and ensure business continuity. By offering cloud-based managed services, MSPs can tap into a broad customer base that includes small and medium-sized enterprises (SMEs) and large corporations seeking to modernize their IT operations.
Growth in Cybersecurity Services and Industry-Specific Solutions
Another promising opportunity is the rising demand for managed cybersecurity services. With the increasing frequency of cyberattacks and the growing complexity of IT environments, businesses are turning to MSPs to bolster their security measures. Managed security services, such as threat monitoring, incident response, and vulnerability assessments, offer significant growth potential for MSPs in Italy. Additionally, there is an emerging demand for industry-specific solutions, as businesses seek managed services tailored to their unique operational and regulatory requirements. By offering specialized services for sectors like healthcare, finance, and manufacturing, MSPs can differentiate themselves in the competitive market, build long-term client relationships, and capture a larger share of the market. These opportunities, driven by the need for advanced security and tailored IT solutions, are expected to drive significant growth in the managed services market in Italy.
Market Segmentation Analysis:
By Service Type:
The Italy Managed Services market is segmented into various service types, each addressing different business needs. The Managed IT Infrastructure & Data Center segment is one of the largest, as businesses require robust and efficient IT infrastructures to support their growing operations. Providers in this segment manage everything from servers and storage to data centers, ensuring that clients have reliable systems in place. The Managed Network segment focuses on network management, offering services like network monitoring, optimization, and troubleshooting to ensure smooth business operations. Similarly, Managed Communication & Collaboration services cater to organizations seeking enhanced communication platforms, including unified communications, email systems, and collaboration tools. The Managed Information segment involves managing data, analytics, and business intelligence, empowering businesses to make informed decisions. The Managed Security segment is increasingly critical due to rising cyber threats, offering services like threat detection and vulnerability management. The Others segment includes additional services like IT consulting and cloud management, which complement the core offerings.
By Deployment Type:
The deployment type of managed services plays a crucial role in determining the service delivery model. The On-premise deployment type remains popular among businesses that require greater control over their IT systems and prefer to manage resources in-house. This deployment type is typically seen in larger enterprises or sectors with high security and regulatory requirements. On the other hand, the Cloud deployment type is rapidly gaining traction as businesses increasingly migrate their IT operations to the cloud. Cloud-based managed services offer flexibility, scalability, and cost efficiency, making them an attractive option for small to medium-sized enterprises (SMEs) and businesses aiming to reduce their infrastructure costs. With cloud adoption continuing to grow, the demand for cloud-based managed services is expected to rise, driving innovation and competition in the Italian market. As businesses continue to seek more agile and cost-effective IT solutions, the cloud deployment segment is poised to experience significant growth.
Segments:
Based on Service Type:
- Managed IT Infrastructure & Data Center
- Managed Network
- Managed Communication & Collaboration
- Managed Information
- Managed Security
- Others
Based on Deployment Type:
- On-premise
- Cloud
Based on Enterprise Size:
- Large Enterprises
- SME’s
Based on End User:
- IT & Telecom
- BFSI
- Manufacturing
- Retail
- Government
- Others
Based on the Geography:
- Northern Italy
- Milan
- Turin
- Venice
- Southern Italy
- Naples
- Palermo
- Bari
Regional Analysis
Northern Italy
Northern Italy holds the largest market share, accounting for approximately 60% of the overall market. This is primarily due to the presence of major economic hubs such as Milan, Turin, and Venice. Milan, being Italy's financial and business center, is a key driver of demand for managed IT services, with many large enterprises and multinational corporations requiring robust IT infrastructure and advanced technology solutions. Turin and Venice, with their thriving manufacturing and tourism industries, also contribute significantly to the demand for managed services, particularly in areas like managed network services and IT infrastructure management.
Southern Italy
In contrast, Southern Italy represents a smaller yet growing segment of the managed services market, capturing around 20% of the overall market share. Cities like Naples, Palermo, and Bari are seeing increased adoption of managed services as businesses in these regions begin to modernize their IT operations. While Southern Italy has historically lagged behind in terms of digital adoption, the region is gradually catching up, particularly in sectors like healthcare, education, and small-to-medium enterprises (SMEs). Managed security and cloud-based services are experiencing the most significant growth in this area, as local businesses prioritize cybersecurity and scalability to compete with their Northern counterparts.
Central Italy
Central Italy, including cities like Rome and Florence, holds a market share of approximately 15%. Rome, as the capital city, is home to numerous government agencies, international organizations, and large enterprises that rely heavily on managed IT and security services. Florence, known for its tourism and cultural heritage, also contributes to the demand for managed communication and collaboration services, as businesses in the tourism industry require seamless operations for managing customer interactions and bookings. While Central Italy's market share is smaller compared to Northern Italy, it remains a key area for the adoption of managed services, especially in sectors focused on digital transformation.
Key Player Analysis
- IBM Corporation
- Accenture
- Microsoft Corporation
- Zettagrid Italy
- Cisco Systems Inc.
- Infosys
- Capgemini
- Sintra Digital Business
- Techlane
- GM Servizi SRL
- Agile Lab
- Google LLC
- HCLTech
- Ericsson
- Others
Competitive Analysis
The Italy Managed Services market is highly competitive, with a mix of global and regional players providing diverse solutions. Leading players such as IBM Corporation, Accenture, Microsoft Corporation, Zettagrid Italy, Cisco Systems Inc., Infosys, Capgemini, Sintra Digital Business, Techlane, GM Servizi SRL, Agile Lab, Google LLC, HCLTech, and Ericsson dominate the market through their broad service portfolios, including cloud computing, IT infrastructure management, network solutions, and cybersecurity services. These players emphasize scalability, reliability, and advanced technologies like cloud computing, AI, and cybersecurity to meet the growing demand for digital transformation in businesses. For instance, a report by the International Trade Administration highlighted that global companies are leveraging their extensive resources to offer comprehensive managed services in Italy. Regional players, on the other hand, focus on offering customized solutions tailored to the specific needs of local industries and smaller businesses. They often provide more agile and flexible services, focusing on cloud management, network optimization, and cybersecurity, which are critical to Italy’s unique market demands. These regional companies capitalize on their deep understanding of the local business environment and their ability to offer personalized customer service. As the market continues to evolve, the competition is intensifying, with companies focusing on innovation, cost-efficiency, and customer-centric approaches. The growing adoption of cloud and hybrid IT solutions, along with the increasing need for managed security services, is shaping the strategies of both global and local players, resulting in an increasingly dynamic and competitive market.
Recent Developments
- In January 2024, Accenture acquired NaviSite to strengthen its managed services offerings, particularly in application and infrastructure management. The acquisition will enhance Accenture’s ability to assist US and Canadian clients in modernizing their digital infrastructure, focusing on AI, cloud, and data-driven solutions for digital transformation.
- In September 2024, TCS launched two AI-powered cybersecurity solutions - Managed Detection and Response (MDR) and Secure Cloud Foundation - in collaboration with Google Cloud. The MDR service was intended to offer continuous, managed threat detection and response, while Secure Cloud Foundation aimed to enhance cloud security posture and governance across hybrid environments. Both solutions leverage Google Cloud’s security tools to provide proactive enterprise protection.
- In June 2024, DXC Technology and Dell partnered to establish Enterprise Intelligence Services (EIS). This service aimed to improve managed services by combining artificial intelligence, data analytics, and cloud technology. EIS’s multi-cloud strategy was expected to help organizations streamline operations, make smarter decisions, and improve customer experiences, proving DXC’s position as the leader in managed multi-cloud solutions.
- In October 2023, technology services provider Logicalis launched an Intelligent Connectivity suite that includes solutions such as SASE, SSE, SD-WAN, and Private 5G powered by Cisco Systems, Inc. This will enable Logicalis customers to access digitally managed services developed using Cisco technology and supported by the Logicalis Digital Fabric Platform.
- In September 2023, communications & technology solution provider Cloud5 Communications launched its new managed services division. The division is designed to support the IT-related requirements & challenges in various markets, such as the hospitality industry, student housing, and senior living, among others. This division will assist consumers in efficiently managing IT operations, technology infrastructures, and security.
- In May 2023, Alfar Capital and Walter Capital Partners completed the acquisition of MSP Corp, a managed IT service provider in Canada. The MSP Corp would merge with Groupe Access, an MSP of IT and cybersecurity solutions. The acquisition would help company to deliver cutting-edge solutions and strengthen its position in Canada.
- In January 2023, Rackspace Technology, a multi-cloud technology solutions provider, launched Rackspace Technology Modern Operations, a managed service for public cloud for customers across Azure, AWS, and GCP. The service will provide benefits including 24x7x365 managed support, cloud expertise, cloud resiliency, and innovation with cloud services which help the company’s customers manage complex cloud environments.
Market Concentration & Characteristics
The Italy Managed Services market exhibits a moderate level of concentration, with a combination of global giants and regional players competing for market share. While global companies, with their extensive resources and broad service portfolios, dominate the market, local firms are increasingly carving out niches by offering specialized solutions tailored to the unique needs of the Italian market. The presence of both large-scale and smaller service providers fosters a competitive environment that encourages innovation and flexibility. The characteristics of the market are shaped by the growing demand for cloud computing, cybersecurity services, and digital transformation solutions. Businesses in Italy are increasingly outsourcing their IT operations to managed service providers (MSPs) in order to reduce costs, improve operational efficiency, and enhance security. As a result, MSPs in Italy are focusing on offering scalable, flexible, and cost-effective solutions, with an emphasis on customer-centric services. Additionally, the market is marked by a high degree of technological advancement, with a strong push toward automation, AI-driven services, and data analytics. These characteristics are attracting both multinational corporations and local SMEs that are seeking to modernize their IT infrastructure and embrace digitalization. The competitive landscape continues to evolve as companies prioritize innovation and adapt to the changing needs of their clients.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Deployment Type, Enterprise Size, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Italy Managed Services market is expected to continue growing, driven by the increasing adoption of cloud and hybrid IT solutions.
- Rising cybersecurity threats will lead to a growing demand for managed security services and advanced threat detection solutions.
- Businesses will increasingly outsource IT functions to focus on core operations and achieve cost efficiency.
- AI and automation technologies will become more integrated into managed services, improving operational efficiency and service delivery.
- The demand for industry-specific managed services will rise as businesses seek tailored solutions for sectors such as healthcare, finance, and manufacturing.
- The shift to remote work will further drive the adoption of managed communication and collaboration services.
- Managed services will play a critical role in supporting digital transformation initiatives across industries in Italy.
- Cloud service providers will enhance their offerings with more scalable and flexible solutions to cater to businesses of all sizes.
- Small and medium-sized enterprises (SMEs) will increasingly adopt managed services to benefit from cost-effective, enterprise-level IT solutions.
- As Italy embraces the Internet of Things (IoT), managed services will support the management of interconnected devices and data security.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Demand for IT Outsourcing
Italian businesses are seeking to reduce operational costs and improve efficiency by outsourcing IT functions such as cloud services, network management, and data storage to managed service providers, allowing them to focus on core competencies.
Acceleration of Digital Transformation
The adoption of advanced technologies like cloud computing, AI, and automation is driving organizations to rely on managed service providers for specialized expertise, supporting Italy’s national digital initiatives and industry modernization.
Shift Toward Remote and Hybrid Work
The rise of remote and hybrid work models in Italy has increased the need for reliable IT infrastructure and support, with managed service providers enabling secure cloud access, collaboration tools, and continuous IT monitoring.
Rising Cybersecurity Threats
With the growing frequency and sophistication of cyberattacks, Italian organizations are turning to managed security services for advanced threat detection, data protection, and compliance management, fueling demand for specialized MSP expertise.
Regional Economic and Sectoral Growth
Northern Italy’s strong industrial and financial sectors, along with increasing adoption in Southern and Central regions, are driving regional demand for managed services, particularly in manufacturing, finance, government, and healthcare.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Italy Managed Services market?
What factors are driving the growth of the Italy Managed Services market?
What are the key segments within the Italy Managed Services market?
What are some challenges faced by the Italy Managed Services market?
Who are the major players in the Italy Managed Services market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 IT & Telecom
- 1.2.2 BFSI
- 1.2.3 Manufacturing
- 1.2.4 Retail
- 1.2.5 Government
- 1.2.6 Others
- 1.3 By Service Type
- 1.3.1 Managed IT Infrastructure & Data Center
- 1.3.2 Managed Network
- 1.3.3 Managed Communication & Collaboration
- 1.3.4 Managed Information
- 1.3.5 Managed Security
- 1.3.6 Others
- 1.4 By Deployment Type
- 1.4.1 On-premise
- 1.4.2 Cloud
- 1.5 By Enterprise Size
- 1.5.1 Large Enterprises
- 1.5.2 SMEs
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 10,273.25 million → 2032: USD 17,048.34 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Italy Managed Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Italy Managed Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Italy Managed Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Italy Managed Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Italy Managed Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Italy Managed Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Italy Managed Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Italy Managed Services Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 10,273.25 million → 2032: USD 17,048.34 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Italy Managed Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Base-Year Market Share, 2023
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 IT & Telecom
- 12.3.6.2 BFSI
- 12.3.6.3 Manufacturing
- 12.3.6.4 Retail
- 12.3.6.5 Government
- 12.3.6.6 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Service Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Base-Year Market Share, 2023
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Managed IT Infrastructure & Data Center
- 12.4.6.2 Managed Network
- 12.4.6.3 Managed Communication & Collaboration
- 12.4.6.4 Managed Information
- 12.4.6.5 Managed Security
- 12.4.6.6 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Base-Year Market Share, 2023
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 On-premise
- 12.5.6.2 Cloud
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Enterprise Size - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Base-Year Market Share, 2023
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Large Enterprises
- 12.6.6.2 SMEs
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Italy Managed Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Italy Managed Services Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Italy Managed Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2023-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Italy Managed Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 IBM Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Accenture
- 18.4 Microsoft Corporation
- 18.5 Cisco Systems Inc.
- 18.6 Zettagrid Italy
- 18.7 Capgemini
- 18.8 Sintra Digital Business
- 18.9 Techlane
- 18.10 Google LLC
- 18.11 HCLTech
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

