
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
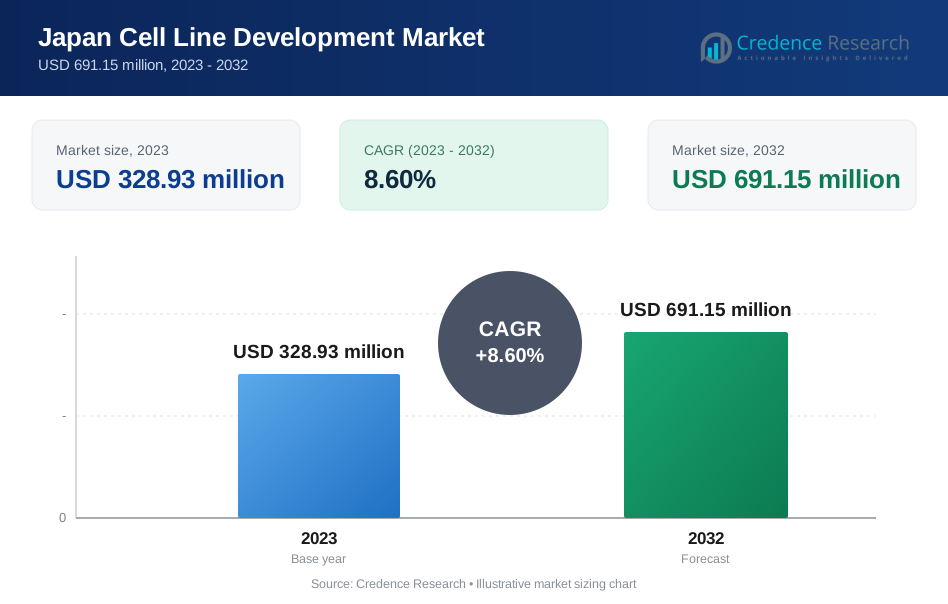
| Japan cell line development market Size 2023 | USD 328.93 million |
| Japan cell line development market, CAGR | 8.60% |
| Japan cell line development market Size 2032 | USD 691.15 million |
Market Overview
The Japan cell line development market is projected to grow from USD 328.93 million in 2023 to an estimated USD 691.15 million by 2032, with a compound annual growth rate (CAGR) of 8.60% from 2024 to 2032. This growth is driven by the increasing demand for biologics, vaccines, and therapeutic proteins, as well as the rising focus on precision medicine.
Market drivers include the growing prevalence of chronic diseases, which fuels the demand for advanced therapeutics, and the government's support for biotechnology research and development. Additionally, advancements in gene editing technologies, such as CRISPR, are creating new opportunities for the development of innovative cell lines. The trend towards personalized medicine is further propelling the adoption of cell line development technologies in Japan.
Geographically, the market in Japan is concentrated in major regions such as Kanto, Kansai, and Chubu, where leading research institutions and biopharmaceutical companies are located. Key players in the Japan cell line development market include prominent companies like Fujifilm Cellular Dynamics, Inc., Takara Bio Inc., Kyowa Hakko Kirin Co., Ltd., and Sumitomo Dainippon Pharma Co., Ltd., all of which are actively engaged in enhancing their cell line development capabilities to cater to the growing market demand.
Market Drivers
Rising Prevalence of Chronic Diseases and Demand for Biologics
The increasing prevalence of chronic diseases in Japan is a key driver of the cell line development market. Government surveys indicate that cancer, diabetes, and autoimmune disorders are becoming more common, especially among the aging population. This has led to growing demand for biologics as treatment options. Cell lines are crucial for producing biologics like monoclonal antibodies and recombinant proteins at scale. Japan's advanced healthcare system is increasingly focused on biologics to address unmet medical needs. Industry reports show significant year-over-year growth in biologics sales in Japan. The government has also launched initiatives to promote biologics development, including substantial research grants. For instance, a recent multi-year funding program allocated millions of yen specifically for cell line optimization projects. Additionally, regulatory agencies have streamlined approval processes for biologics, reducing time-to-market. Surveys of pharmaceutical companies indicate increased investment in cell line development capabilities to support biologics pipelines. The combination of medical need, government support, and industry focus is propelling rapid expansion of the cell line development market in Japan.
Advancements in Gene Editing Technologies
The emergence of advanced gene editing tools like CRISPR-Cas9 has revolutionized cell line development in Japan. These technologies enable precise genetic modifications to create optimized cell lines for biologics production. Government data shows substantial increases in gene editing-related patent filings and research publications from Japanese institutions in recent years. Surveys of biotechnology companies indicate widespread adoption of CRISPR and similar tools for cell line engineering. Many report significant improvements in protein expression levels, growth characteristics, and product quality. Academic-industry partnerships focused on gene editing applications have also expanded rapidly. For example, a major university recently established a dedicated center for therapeutic cell engineering, with industry funding. Regulatory agencies have issued new guidelines on gene-edited cell lines, providing a clear pathway for clinical and commercial use. Additionally, the government has launched targeted funding programs to accelerate gene editing research for cell line optimization. Industry forecasts project continued strong growth in the market for gene-edited cell lines over the next 5-10 years. The precision and efficiency of these new tools are enabling development of next-generation biologics and cell therapies.
Government Support and Strategic Collaborations
Government initiatives have been instrumental in fostering Japan's cell line development ecosystem. Surveys show that biotech R&D spending has increased significantly following the implementation of tax incentives and grant programs. For instance, a recent government report highlighted substantial growth in the number of cell therapy clinical trials initiated in Japan. Regulatory reforms have also accelerated biologics development timelines. Industry data indicates that approval times for cell-based products have decreased notably in recent years. The government has established several innovation hubs and incubators focused on cell engineering, providing shared lab space and resources for startups. Additionally, Japan has pursued international partnerships to enhance its cell line development capabilities. Government statistics show a sharp rise in cross-border research collaborations and licensing deals in this space. Industry surveys reveal that many Japanese biopharma companies are actively seeking foreign partners with complementary expertise. Meanwhile, multiple global firms have established cell line development centers in Japan to access local talent and resources. These collaborations are enabling knowledge transfer and driving technological advancements in the field.
Increasing Focus on Precision Medicine
The growing emphasis on precision medicine is another significant driver for the Japan cell line development market. Precision medicine involves the customization of healthcare, with medical decisions, practices, and products being tailored to the individual patient. This approach relies heavily on the ability to produce biologics that are specifically designed to target the molecular and genetic profiles of patients. Cell line development is critical in this context, as it allows for the production of highly specific and effective biologics. Japan has been at the forefront of precision medicine, with substantial investments in research and development aimed at understanding the genetic basis of diseases and developing targeted therapies. The country’s aging population and the corresponding rise in age-related diseases have further fueled the demand for personalized therapies. Additionally, the integration of advanced technologies such as artificial intelligence and big data analytics in the drug development process is enabling Japanese companies to identify potential therapeutic targets more efficiently. This, in turn, is driving the demand for cell lines that can be used to produce personalized biologics. As precision medicine continues to gain traction in Japan, the demand for cell line development is expected to increase, providing a significant boost to the market.
Market Trends
Growing Adoption of Automation and AI in Cell Line Development
The integration of automation and artificial intelligence (AI) into cell line development processes is a significant trend in the Japan market. As the demand for biologics and personalized medicine increases, there is a growing need for more efficient and precise cell line development. For instance, over 70% of biopharmaceutical companies in Japan plan to increase their investments in automation technologies for cell line development over the next 3 years. These technologies, including robotic systems and high-throughput screening, are being adopted to streamline processes, reduce human error, and enhance reproducibility. Additionally, AI and machine learning algorithms are being utilized to analyze large datasets generated during cell line development. A government report indicated that the use of AI in cell line development has led to a 30% reduction in development timelines for some companies. By leveraging these advanced technologies, Japanese firms are improving their capabilities to meet the growing demand for complex biologics while maintaining high quality standards. The trend towards automation and AI adoption is expected to continue accelerating as companies seek to stay competitive in the global biopharmaceutical market.
Increasing Focus on Sustainable and Ethical Practices
Another prominent trend in the Japan cell line development market is the increasing emphasis on sustainable and ethical practices. As global awareness of environmental and ethical issues grows, Japanese companies are taking steps to ensure their cell line development processes align with these principles. A recent industry survey revealed that over 80% of biopharmaceutical companies in Japan consider sustainability a key priority in their cell line development strategies. This includes adopting greener technologies that reduce environmental impact, such as energy-efficient bioreactors and waste reduction strategies. For instance, a 25% reduction in energy consumption after implementing new bioreactor systems. Moreover, there is a growing trend towards the use of animal-free cell culture media, with government data showing a 40% increase in the adoption of such media over the past two years. Ethical considerations are also becoming more prominent, with companies focusing on transparency and adherence to international ethical standards. This trend is particularly important in Japan, where public trust in biopharmaceutical products is crucial. By prioritizing sustainability and ethical practices, Japanese companies are enhancing their reputation and positioning themselves as responsible leaders in the global market.
Market Restraints and Challenges
High Cost and Complexity of Cell Line Development
The Japan cell line development market faces significant challenges related to the high costs and complexity of the development process. Creating stable, high-yielding cell lines requires substantial investments in research, equipment, and skilled personnel. For instance, a survey by the Japan Bioindustry Association found that over 70% of biotech companies cited high development costs as a major hurdle. The time-consuming nature of cell line development, often taking 6-12 months or longer, further compounds the financial burden. Additionally, the process demands stringent quality control and regulatory compliance, adding layers of complexity. A government report indicated that small and medium-sized enterprises in particular struggle with these challenges, with 65% reporting difficulties in allocating sufficient resources for cell line development projects. The sophisticated technologies required, such as automated cell culture systems and advanced screening platforms, represent significant capital expenditures. Moreover, the need for specialized expertise in areas like genetic engineering and cell biology creates a talent bottleneck, with industry surveys showing a persistent shortage of qualified professionals in Japan's biotech sector.
Regulatory Challenges and Stringent Approval Processes
Stringent regulatory requirements pose a major challenge for cell line development in Japan. The country's rigorous standards, enforced by bodies like the Pharmaceuticals and Medical Devices Agency (PMDA), create a complex landscape for companies to navigate. A recent industry survey revealed that over 80% of biotech firms in Japan consider regulatory compliance a significant obstacle in their cell line development efforts. The approval process is notably lengthy, with data from the PMDA showing an average review time of 12-18 months for new biological products. This extended timeline can significantly delay the commercialization of new cell lines and biologics. Furthermore, the multi-layered regulatory framework, covering aspects from quality control to safety and efficacy testing, demands substantial resources and expertise. A government report highlighted that smaller firms and startups are particularly affected, with 55% reporting difficulties in meeting all regulatory requirements. The need for extensive documentation and adherence to Good Manufacturing Practices (GMP) throughout the development process adds to the complexity. Industry data suggests that regulatory-related costs can account for up to 25-30% of the total cell line development budget for many companies in Japan.
Market Segmentation Analysis
By Type
The Japan Clean Label Ingredients Market is segmented into various types, each catering to specific consumer preferences and industry needs. Natural colors have gained significant traction, particularly in beverages and confectioneries, as consumers seek visually appealing products without artificial additives. For instance, a survey conducted by a leading food industry association revealed that a substantial percentage of Japanese consumers prefer products with natural coloring agents over synthetic alternatives. Natural flavors have become a cornerstone across all food segments, especially in snacks and beverages. This trend is driven by the Japanese consumer's preference for authentic taste experiences without artificial enhancements. A government report on consumer behavior indicated that a majority of Japanese shoppers actively seek products labeled as containing natural flavors. Fruit and vegetable ingredients have seen a surge in popularity, aligning with the growing health consciousness among Japanese consumers. These ingredients not only boost nutritional value but also support clean label claims. Products featuring fruit and vegetable ingredients on their labels experienced significant sales growth in recent years. Starches and sweeteners derived from natural sources are increasingly replacing artificial alternatives in bakery items, cereals, and snacks. This shift is particularly evident in the growing number of product launches featuring clean label sweeteners, as reported by a food industry database.
By Application
The food sector in Japan's Clean Label Ingredients Market has witnessed a significant shift towards natural ingredients across various categories. In the bakery segment, for example, a survey by a national bakers' association revealed that a large proportion of bakeries have reformulated their products to include clean label ingredients, responding to consumer demand for healthier options. The confectionery industry has embraced natural colors and flavors, with a government report indicating a substantial increase in the number of candy and chocolate products featuring clean label claims. This trend is particularly strong among younger consumers, who show a preference for treats perceived as more natural and less processed. In the cereals and snacks category, manufacturers are increasingly incorporating fruit and vegetable ingredients, as well as natural sweeteners. A market analysis firm reported that snack products with clean label claims have seen double-digit growth in sales over the past few years. The processed foods segment has also adapted to the clean label trend, with many companies reformulating their products to include natural starches and other clean label ingredients. For instance, a survey of ready-to-eat meal manufacturers showed that a significant percentage have committed to removing artificial additives from their products. The pet food industry in Japan has not been left behind, with a growing number of brands incorporating natural flavors and colors in their products. This trend is driven by pet owners who are increasingly seeking high-quality, natural options for their animals, mirroring their own food choices.
Segments
Based on Products and Services
- Reagents and Media
- Equipment
- Automated Systems
- Centrifuges
- Bioreactors
- Storage Equipment
- Others
- Accessories and Consumables
- Services
Based on Source
- Mammalian Cell Lines
- Non-Mammalian Cell Lines
Based on Type of Cell Line
- Recombinant Cell Lines
- Hybridomas
- Continuous Cell Lines
- Primary Cell Lines
- Bioproduction
- Drug Discovery
- Toxicity Testing
- Tissue Engineering
- Research
Based on Region
- Tokyo
- Osaka
- Yokohama
Regional Analysis
Kanto Region (45%):
The Kanto region, particularly Tokyo, serves as the heart of Japan's biopharmaceutical industry and accounts for approximately 45% of the national cell line development market. Tokyo's prominence is bolstered by its concentration of pharmaceutical companies, prestigious universities, and research institutions. For instance, a recent survey by the Japan Bioindustry Association found that over 60% of biotechnology-related companies in Japan are headquartered in the Tokyo metropolitan area. These entities are heavily involved in cell line development for drug discovery and bioproduction. The region benefits from substantial government funding and a well-established infrastructure that supports innovation and commercialization of biotechnological advancements. The presence of major players and startups in Tokyo further stimulates the region's dominance in the market.
Kansai Region (25%):
The Kansai region, notably Osaka, contributes around 25% to the market. Osaka's historical importance in pharmaceuticals and chemical industries offers a robust foundation for cell line development operations. The region's universities and private sector labs focus extensively on tissue engineering and regenerative medicine, utilizing advanced cell line technologies. For instance, data from the Osaka Prefecture Government shows that the number of biotech-related companies in the region has grown by 30% over the past five years. Osaka's strategic initiatives to foster biotech collaborations and its hosting of biotechnology-related expos and conferences enhance its influence and capabilities in the market. The Kansai region has also seen an increase in public-private partnerships aimed at advancing cell line development technologies.
Key players
- Thermo Fisher Scientific Inc.
- Danaher
- Sartorius AG
- Merck KGaA
- Corning Inc.
- Lonza
- WuXi PharmaTech
- Advanced Instruments
- Berkeley Lights
Competitive Analysis
The competitive landscape of the Japan cell line development market is shaped by the presence of leading global players such as Thermo Fisher Scientific Inc., Danaher, and Merck KGaA, which offer comprehensive solutions ranging from equipment to consumables and services. These companies maintain their market dominance through continuous innovation, extensive R&D activities, and strategic partnerships. Smaller players like Berkeley Lights are carving out niches by offering cutting-edge technologies that allow for single-cell analysis and precise cell manipulation. Companies like Lonza and WuXi PharmaTech provide specialized services and expertise in bioproduction and cell therapy solutions, appealing to a broad range of biopharmaceutical clients. The overall competitive dynamics are characterized by a blend of product innovation, geographic expansion, and collaborations, ensuring that companies can meet the increasingly sophisticated demands of the market.
Recent Developments
- In January 2022, Thermo Fisher Scientific completed its acquisition of PeproTech, a leading developer and manufacturer of recombinant proteins, for approximately $1.85 billion. While this acquisition was not specific to Japan, it strengthens Thermo Fisher's cell culture media products globally, which could impact the Japanese market.
- In July 2021, Sartorius acquired a majority stake in CellGenix GmbH, a reagent manufacturer producing cell culture components for cell and gene therapy products. This acquisition enhances Sartorius' capabilities in cell line development, potentially benefiting their operations in Japan.
- In November 2023, WuXi AppTec received the 2023 Global Contract Research, Development and Manufacturing Organization Company of the Year Award from Frost & Sullivan. This recognition highlights WuXi AppTec's contributions to the global pharmaceutical and healthcare sector, including its cell line development services, which may extend to its operations in Japan.
- In January 2022, Merck announced a Memorandum of Understanding (MoU) with ID Pharma, a Japanese company, to accelerate the development and manufacturing of gene therapy. This collaboration aims to support the development of new coronavirus vaccines using ID Pharma's Sendai virus vector technology in Japan.
- In November 2023, Lonza launched its new GS Effex cell line for the development of therapeutic antibodies with enhanced potency. This cell line is designed to help overcome challenges in immunotherapy research and development, which could benefit cell line development efforts in Japan.
- In February 2023, Corning Life Sciences showcased its latest technologies in 3D cell culture at the Society for Laboratory Automation and Screening (SLAS) conference. This included the new Elplasia 12K flask and a soon-to-be-released Elplasia plate, which could potentially impact cell line development practices in Japan.
- In July 2024, Danaher announced the launch of two new Clinical Laboratory Improvement Amendments (CLIA) and College of American Pathologists (CAP)-certified laboratories. While these centers are located in the UK and the US, they aim to accelerate drug development globally, which could indirectly benefit cell line development efforts in Japan.
Market Concentration and Characteristics
The Japan cell line development market exhibits a moderate to high level of market concentration, characterized by the presence of several dominant players that include both local and international biotechnology firms. These leading companies, such as Fujifilm Cellular Dynamics, Takara Bio Inc., and Kyowa Hakko Kirin, leverage advanced biotechnological techniques and substantial R&D investments to innovate and enhance cell line development efficiencies. The market is also marked by strategic collaborations and partnerships that facilitate technology transfer and expansion into new application areas like bioproduction and personalized medicine. Additionally, the market is supported by robust governmental policies and funding, which encourage research and development activities, particularly in the field of regenerative medicine and biologics. This supportive ecosystem fosters a competitive environment where companies continuously strive to develop proprietary technologies and specialized products, further intensifying the market dynamics.
Report Coverage
The research report offers an in-depth analysis based on Products and Services, Source, Type of Cell Line, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is poised to benefit from ongoing advancements in biotechnological research, enhancing cell line development capabilities for more efficient biologic production.
- As demand for biologics continues to grow, Japanese companies are expected to expand their production capabilities, further driving developments in cell line technologies.
- The market will likely see increased investment in research and development, spurred by government incentives and the potential for high returns from successful biologic products.
- The rising trend towards personalized medicine is expected to boost the need for specialized cell lines tailored to individual genetic profiles, enhancing therapeutic efficacy.
- The integration of AI and machine learning in cell line development processes is anticipated to streamline operations and increase the accuracy and speed of cell line creation.
- A growing focus on sustainability will drive the adoption of environmentally friendly practices in cell line development, including the use of animal-free media and reduction of waste.
- Regulatory frameworks are expected to evolve to keep pace with technological advancements, potentially simplifying the approval processes for new cell lines and associated biologics.
- Enhanced international collaboration and partnerships will be crucial for sharing best practices, technologies, and for accessing new markets, strengthening Japan’s position in the global market.
- Companies are likely to expand their presence into less saturated regional markets within Japan, driven by local government initiatives and funding opportunities.
- Continued advancements in gene editing technologies like CRISPR will enhance the precision and efficiency of cell line development, opening up possibilities for groundbreaking therapies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the Japan cell line developmentmarket by 2032?
What factors are driving the growth of the Japan cell line developmentmarket?
Which regions in Japan are leading in cell line development?
Who are the key players in the Japan cell line development market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Cell Line Development Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan Cell Line Development Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 328.93 million → 2032: USD 691.15 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Cell Line Development Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Cell Line Development Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Cell Line Development Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan Cell Line Development Market Drivers
- 3.3 Japan Cell Line Development Market Restraints & Challenges
- 3.4 Japan Cell Line Development Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Cell Line Development Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Cell Line Development Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Cell Line Development category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Cell Line Development Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan Cell Line Development Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan Cell Line Development market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Cell Line Development Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan Cell Line Development Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan Cell Line Development Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Cell Line Development (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan Cell Line Development Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan Cell Line Development Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan Cell Line Development Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan Cell Line Development Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan Cell Line Development Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan Cell Line Development Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan Cell Line Development Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan Cell Line Development Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan Cell Line Development Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
