
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
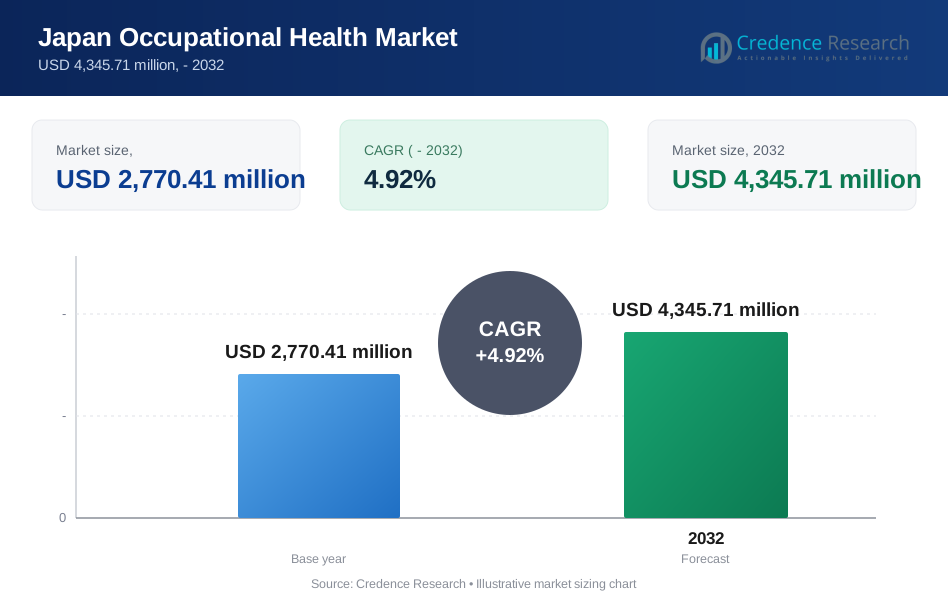
| Japan Occupational Health Market Size 2023 | USD 2,770.41 Million |
| Japan Occupational Health Market, CAGR | 4.92% |
| Japan Occupational Health Market Size 2032 | USD 4,345.71 Million |
Market Overview
The Japan Occupational Health Market is projected to grow from USD 2,770.41 million in 2023 to an estimated USD 4,345.71 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.92% from 2024 to 2032. This steady growth is driven by the increasing focus on workplace safety, regulatory mandates for occupational health and safety standards, and rising awareness among employers about the benefits of employee well-being programs.
Market drivers include the aging workforce in Japan, which necessitates enhanced occupational health measures to address age-related challenges and ensure productivity. Additionally, the adoption of innovative technologies such as wearable health monitoring devices and data analytics tools is transforming workplace health management. Trends like personalized health solutions and remote health monitoring are gaining traction, fueled by advancements in digital health and telemedicine. These factors collectively contribute to improved health outcomes and reduced absenteeism, further propelling market growth.
Geographically, the market's growth is concentrated in urban and industrialized regions, including Tokyo, Osaka, and Nagoya, due to higher employment rates and stringent compliance standards in these areas. Key players in the Japan Occupational Health market include prominent firms such as SOMPO Health Support, Nichii Gakkan, and Japan Industrial Safety & Health Association, which focus on providing comprehensive health services and tailored solutions to meet diverse industry needs.
Market Drivers
Aging Workforce and Workplace Adaptations
Japan's rapidly aging population is one of the most significant factors driving the occupational health market. With over 28% of its population aged 65 or older, Japan faces a growing proportion of older workers in its labor force. For instance, as of 2017, the country had an old-age dependency ratio exceeding 50 elderly individuals for every 100 working-age persons, a figure projected to rise to 79 by 2050. This demographic shift necessitates tailored workplace health solutions that address age-related challenges such as chronic illnesses, musculoskeletal disorders, and declining physical capabilities. Consequently, employers increasingly invest in preventive measures, ergonomic workplace designs, and health monitoring programs to maintain productivity and reduce healthcare costs associated with aging employees. As a result, demand for specialized occupational health services continues to rise.
Stringent Government Regulations and Compliance Standards
The Japanese government enforces strict occupational health and safety regulations to ensure worker well-being and minimize workplace hazards. Regulatory frameworks like the Industrial Safety and Health Act mandate routine health check-ups, mental health assessments, and the implementation of safety management systems in workplaces. These requirements compel organizations to adopt comprehensive occupational health services and technologies. For example, government initiatives that provide subsidies for health promotion programs have heightened employer awareness regarding workplace safety and employee well-being, further driving demand for specialized health services. Additionally, campaigns aimed at reducing work-related stress have also accelerated market growth.
Technological Advancements and Digital Transformation
Technological innovation plays a pivotal role in transforming the occupational health landscape in Japan. The adoption of wearable devices, such as fitness trackers and health monitoring sensors, enables real-time tracking of employees' physical conditions. For instance, these technologies allow employers to identify potential health risks early and implement preventive interventions effectively. Furthermore, digital health platforms and telemedicine solutions facilitate remote health consultations, which are particularly beneficial for industries with remote or decentralized workforces. The integration of artificial intelligence (AI) and data analytics in occupational health management enhances predictive capabilities, enabling employers to anticipate and mitigate workplace risks effectively.
Growing Awareness of Mental Health and Wellness
The increasing emphasis on mental health and wellness in the workplace is a critical driver of the Japan occupational health market. High levels of work-related stress, known locally as "karoshi" (death due to overwork), have drawn attention to the importance of mental well-being. Employers are now implementing programs focused on stress management, employee assistance, and mental health counseling to address these challenges. Awareness campaigns and corporate wellness initiatives promote a culture of holistic health, integrating both physical and psychological well-being. This shift reflects a broader societal recognition of the importance of mental health in ensuring workforce sustainability and productivity.
Market Trends
Integration of Digital Health Solutions and Wearable Technology
The adoption of digital health technologies is revolutionizing the Japan occupational health market. Employers are increasingly incorporating wearable devices, such as fitness trackers, heart rate monitors, and posture-correcting devices, to monitor employees’ physical health in real time. These devices provide actionable insights, allowing early detection of health risks like fatigue, stress, or cardiovascular irregularities. For instance, companies like Rakuten have established dedicated wellness teams that focus on both physical and mental health, implementing initiatives such as stretching exercises during company meetings and wellness surveys to assess employee health concerns. This proactive approach has resulted in increased participation in health-related activities, with about 400 employees attending online events aimed at raising health awareness, demonstrating a commitment to maintaining healthy minds and bodies among their workforce. Digital platforms powered by artificial intelligence (AI) and data analytics are also gaining traction, offering predictive insights into workplace health trends and enabling targeted interventions. Telemedicine solutions further enhance access to occupational health services, especially for remote or decentralized workplaces, providing employees with virtual consultations and continuous health monitoring. This technological transformation not only ensures compliance with regulatory health mandates but also optimizes workplace productivity by preventing health-related disruptions.
Emphasis on Holistic Employee Wellness Programs
In response to growing concerns over work-life balance, mental health, and workplace stress, employers are adopting holistic wellness programs that address both physical and psychological well-being. This trend is driven by societal awareness of "karoshi" (death from overwork) and the need to prevent burnout among employees. Programs focusing on mindfulness, stress reduction, and resilience training are being integrated alongside traditional health assessments.For example, in 2021, there were over 2,300 applications for worker’s compensation due to mental health disorders, highlighting the urgent need for effective mental wellness strategies in the workplace. Companies are responding by integrating stress management workshops and counseling services into their policies, aiming to foster environments that prioritize employee well-being and reduce the stigma surrounding mental health issues. Additionally, organizations are providing personalized wellness plans that include nutritional guidance, fitness regimens, and mental health counseling to cater to diverse employee needs. AIG Japan exemplifies a comprehensive approach to health management by promoting regular medical check-ups and stress assessments. Their initiatives have led to a notable improvement in employee engagement metrics and a decrease in absenteeism rates, showcasing how structured health programs can enhance workplace productivity while supporting individual health needs.The introduction of flexible work schedules and initiatives to promote a healthier work environment reflects a shift towards fostering sustainable workplace cultures. These trends highlight the evolving focus of occupational health from reactive medical care to proactive and preventive wellness strategies.
Market Restraints and Challenges
High Costs of Implementation and Limited Budget Allocations
One of the primary restraints in the Japan occupational health market is the high cost associated with implementing comprehensive occupational health programs. Advanced technologies such as wearable health devices, AI-powered health analytics, and telemedicine platforms require significant upfront investment. Small and medium-sized enterprises (SMEs), which constitute a substantial portion of Japan's economy, often face financial constraints, limiting their ability to adopt such solutions. Additionally, ongoing costs for maintenance, employee training, and periodic upgrades further strain budgets. Despite government subsidies and incentives, the financial burden of establishing and sustaining robust occupational health systems remains a significant challenge for many organizations.
Cultural Stigma Around Mental Health and Resistance to Change
Cultural attitudes toward mental health and workplace wellness pose another critical challenge in the Japan occupational health market. Despite growing awareness, mental health issues are still stigmatized in some sectors, deterring employees from openly seeking help or participating in wellness programs. Employers may also face resistance when attempting to introduce new health initiatives, as some traditional industries prioritize productivity over employee well-being. Furthermore, the reluctance to adopt digital health solutions among older employees or organizations unfamiliar with advanced technologies adds to the challenge. This resistance to change can slow the adoption of innovative occupational health practices and impede the market's overall growth trajectory.
Market Segmentation Analysis
By Type
The Japan occupational health market is broadly segmented into products and services. The services segment dominates the market, driven by the increasing demand for health monitoring, wellness programs, and regulatory compliance support. Products, including safety equipment and health aids, complement services by ensuring workplace safety and preventive health management.
By product
The product segment of the Japan Occupational Health market includes a range of solutions designed to enhance workplace safety and employee well-being. Personal Protective Equipment (PPE), such as helmets, gloves, and protective clothing, holds a significant market share due to stringent safety regulations in industries like manufacturing and construction. Safety Signage plays a critical role in visual safety communication, ensuring adherence to workplace standards. First Aid Kits maintain consistent demand across sectors for prompt treatment of minor injuries. The growing focus on preventing musculoskeletal disorders drives the adoption of Ergonomic Furniture and Equipment. Additionally, Respiratory Protection Equipment is essential in sectors such as mining, oil and gas, and healthcare, addressing the need to safeguard workers from airborne contaminants and occupational hazards.
Segments
Based on Type
- Product
- Services
Based on Product
- Personal Protective Equipment (PPE)
- Safety Signage
- First Aid Kits
- Ergonomic Furniture and Equipment
- Respiratory Protection Equipment
Based on Service
- Pre-Employment Health Screening
- Health Surveillance and Monitoring
- Health Risk Assessment
- Health Promotion and Wellness Programs
- Vaccination and Immunization Services
Based on Vertical
- Manufacturing and Construction
- Healthcare
- Oil and Gas and Mining
Based on Enterprise Size
- Large Enterprises
- SMEs
Based on Region
- Tokyo
- Osaka
- Nagoya
Regional Analysis
Kanto Region (40%):
The Kanto region, which includes Tokyo, Yokohama, and surrounding metropolitan areas, accounts for the largest market share, contributing approximately 40% of the total market. This dominance is attributed to the high concentration of industries, corporate headquarters, and urbanized populations. Businesses in this region heavily invest in occupational health solutions to comply with strict safety regulations and address employee wellness in diverse sectors like manufacturing, finance, and services. The region also leads in adopting advanced technologies such as telemedicine and wearable health devices, reflecting its progressive approach to workplace health.
Kansai Region (25%):
The Kansai region, including Osaka, Kyoto, and Kobe, holds around 25% of the market share. This region is characterized by a strong industrial base, particularly in manufacturing and construction. Companies here prioritize health surveillance and the use of protective equipment to meet regulatory standards. The Kansai region also shows growing interest in mental health and wellness programs, driven by the increasing awareness of work-life balance among employees and employers.
Key players
- Yokowo Co., Ltd.
- KIOXIA Holdings Corporation
- Daifuku
- Daicel Corporation
- Others
Competitive Analysis
The Japan Occupational Health market is characterized by a mix of established players and emerging companies, competing across diverse segments like products, services, and technology solutions. Key players such as Yokowo Co., Ltd., KIOXIA Holdings Corporation, Daifuku, and Daicel Corporation leverage their strong product portfolios and innovative strategies to maintain a competitive edge. Yokowo Co., Ltd. stands out with its diversified product offerings and strategic focus on technological advancements. KIOXIA Holdings Corporation emphasizes data-driven solutions, aligning with trends in digital health. Meanwhile, Daifuku and Daicel Corporation prioritize safety compliance and ergonomic innovations. Smaller and niche players, categorized under "Others," focus on customized solutions for SMEs and specific industries, creating localized competition. The competitive landscape is dynamic, with companies adopting partnerships, product innovation, and digital transformation to meet evolving demands and maintain market relevance.
Recent Developments
- In April 2022, Yokowo established an Occupational Health & Safety Section within its General Affairs Department to enhance measures contributing to employee health and safety. This initiative aims to promote activities across various committees focused on occupational health and safety (OH&S).
- In November 2023, KIOXIA launched a new mental health initiative aimed at improving employee well-being. This program includes regular mental health workshops and access to counseling services, reflecting the company's commitment to fostering a supportive work environment.
- In September 2023, Daifuku introduced a comprehensive wellness program that includes fitness classes, nutritional counseling, and mental health resources. This initiative is designed to address both physical and mental health needs of employees, promoting overall workplace wellness.
- In October 2023, Daicel Corporation announced the implementation of a new telehealth service for employees, allowing them to consult with healthcare professionals remotely. This service aims to improve access to health resources and support employee well-being, particularly in light of ongoing challenges related to work-life balance.
Market Concentration and Characteristics
The Japan Occupational Health market exhibits a moderate market concentration, with a mix of established multinational corporations and local players dominating key segments such as health services, safety products, and digital solutions. Established companies like Yokowo Co., Ltd. and Daicel Corporation hold significant market shares due to their expansive product portfolios and strong industry presence. At the same time, regional and niche players cater to specific needs, particularly for SMEs and localized industries, ensuring a competitive landscape. The market is characterized by stringent regulatory frameworks, a high degree of innovation in health technologies, and a growing emphasis on employee wellness programs. The adoption of digital health tools and personalized solutions further highlights the market's shift toward preventive and holistic health strategies, aligning with Japan’s aging workforce and the rising awareness of workplace well-being.
Report Coverage
The research report offers an in-depth analysis based on Type, Product, Service, Vertical, Enterprise Size and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Japan Occupational Health market is expected to maintain steady growth, driven by increasing regulatory compliance and employer focus on workplace safety and employee well-being.
- The adoption of AI, IoT-enabled wearables, and data analytics will transform occupational health practices, enabling real-time monitoring and predictive risk assessment.
- Employers will increasingly prioritize mental health initiatives, integrating stress management, mindfulness training, and counseling into workplace wellness programs.
- Tailored health programs and ergonomic solutions will expand to meet the needs of Japan’s aging workforce, ensuring sustained productivity and reduced healthcare costs.
- Preventive measures such as pre-employment screening, regular health surveillance, and vaccination services will gain prominence to minimize workplace-related illnesses.
- Small and medium-sized enterprises (SMEs) will gradually adopt affordable occupational health solutions, supported by government incentives and cost-efficient innovations.
- Telemedicine and digital health platforms will play a pivotal role in providing remote consultations and expanding occupational health access across industries.
- While urban areas will dominate, rural and underdeveloped regions will increasingly adopt occupational health solutions due to growing awareness and government support.
- Personalized health solutions tailored to specific industries and enterprise sizes will drive innovation and expand market reach.
- The market will witness a shift towards eco-friendly occupational health products and practices, aligning with global sustainability trends and corporate social responsibility initiatives.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Aging Workforce and Workplace Adaptations
Japan's rapidly aging population is increasing the need for tailored occupational health solutions that address chronic illnesses, musculoskeletal disorders, and declining physical capabilities among older workers. Employers are investing in preventive measures and ergonomic workplace designs to maintain productivity and reduce healthcare costs.
Stringent Government Regulations and Compliance Standards
Strict enforcement of occupational health and safety regulations, such as the Industrial Safety and Health Act, mandates routine health check-ups and mental health assessments, compelling organizations to adopt comprehensive occupational health services and technologies.
Technological Advancements and Digital Transformation
The adoption of wearable health monitoring devices, telemedicine, and AI-powered analytics is transforming workplace health management, enabling real-time monitoring, predictive risk assessment, and remote health consultations, which improve health outcomes and compliance.
Growing Awareness of Mental Health and Wellness
Increased recognition of work-related stress and mental health issues, such as 'karoshi,' is driving employers to implement stress management, counseling, and holistic wellness programs, fostering a culture of well-being and reducing absenteeism.
Urban and Industrial Concentration
The concentration of industries and corporate headquarters in urban regions like Tokyo, Osaka, and Nagoya, combined with higher employment rates and stricter compliance standards, is fueling demand for advanced occupational health solutions in these areas.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Japan Occupational Health market in 2023, and what is the projected size by 2032?
What factors are driving the growth of the Japan Occupational Health market?
Which regions in Japan dominate the Occupational Health market?
What trends are shaping the Japan Occupational Health market?
Who are the key players in the Japan Occupational Health market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Product
- 1.2.2 Services
- 1.3 By Product
- 1.3.1 Personal Protective Equipment (PPE)
- 1.3.2 Safety Signage
- 1.3.3 First Aid Kits
- 1.3.4 Ergonomic Furniture and Equipment
- 1.3.5 Respiratory Protection Equipment
- 1.4 By Service
- 1.4.1 Pre-Employment Health Screening
- 1.4.2 Health Surveillance and Monitoring
- 1.4.3 Health Risk Assessment
- 1.4.4 Health Promotion and Wellness Programs
- 1.4.5 Vaccination and Immunization Services
- 1.5 By Vertical
- 1.5.1 Manufacturing and Construction
- 1.5.2 Healthcare
- 1.5.3 Oil and Gas and Mining
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 2,770.41 million → 2032: USD 4,345.71 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Japan Occupational Health Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Japan Occupational Health Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Japan Occupational Health Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Japan Occupational Health Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Japan Occupational Health Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Japan Occupational Health Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Japan Occupational Health Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Japan Occupational Health Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 2,770.41 million → 2032: USD 4,345.71 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Japan Occupational Health Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Product
- 12.3.7.2 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Personal Protective Equipment (PPE)
- 12.4.7.2 Safety Signage
- 12.4.7.3 First Aid Kits
- 12.4.7.4 Ergonomic Furniture and Equipment
- 12.4.7.5 Respiratory Protection Equipment
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Service - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pre-Employment Health Screening
- 12.5.7.2 Health Surveillance and Monitoring
- 12.5.7.3 Health Risk Assessment
- 12.5.7.4 Health Promotion and Wellness Programs
- 12.5.7.5 Vaccination and Immunization Services
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Vertical - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Manufacturing and Construction
- 12.6.7.2 Healthcare
- 12.6.7.3 Oil and Gas and Mining
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Japan Occupational Health End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Japan Occupational Health Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Japan Occupational Health Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Japan Occupational Health Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Yokowo Co., Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 KIOXIA Holdings Corporation
- 18.4 Daifuku
- 18.5 Daicel Corporation
- 18.6 SOMPO Health Support
- 18.7 Nichii Gakkan
- 18.8 Japan Industrial Safety & Health Association
- 18.9 Hitachi Ltd.
- 18.10 Fujitsu Limited
- 18.11 AIG Japan
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

