
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
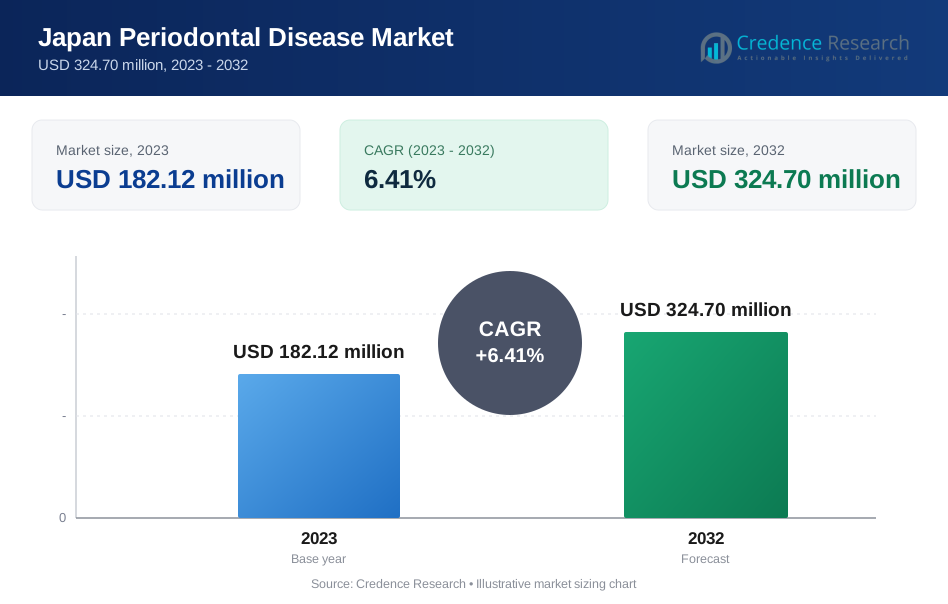
| Japan Periodontal Disease Market Size 2023 | USD 182.12 Million |
| Japan Periodontal Disease Market, CAGR | 6.41% |
| Japan Periodontal Disease Market Size 2032 | USD 324.70 Million |
Market Overview
The Japan Periodontal Disease Market is projected to grow from USD 182.12 million in 2023 to USD 324.70 million by 2032, at a compound annual growth rate (CAGR) of 6.41%.
The Japan periodontal disease market is driven by the rising prevalence of periodontal conditions, an aging population, and increased awareness about oral health. As the elderly population grows, there is a higher incidence of periodontal diseases, which drives demand for diagnostic and therapeutic treatments. Additionally, the adoption of advanced technologies in dental care, such as laser treatments and regenerative therapies, is contributing to market growth. Growing awareness campaigns about the importance of oral hygiene and its links to overall health have also prompted more people to seek treatment. Moreover, the increasing availability of specialized dental clinics and the incorporation of periodontal disease management into routine healthcare services further support market expansion.
The Japan periodontal disease market is characterized by a well-established healthcare infrastructure and a growing awareness of oral health. Key regions such as Kanto, Kansai, and Chubu are seeing significant demand for periodontal care due to the high concentration of healthcare facilities and dental clinics. The country's aging population also contributes to the increasing prevalence of periodontal diseases, creating a steady demand for both surgical and non-surgical treatments. Leading players in the market include major pharmaceutical and dental care companies like DENTSPLY SIRONA Inc., Biolase, Inc., and Yoshida Dental Manufacturing Co., Ltd. These companies are actively involved in the development and distribution of advanced periodontal disease treatments and technologies. Additionally, local clinics and hospitals play a crucial role in providing treatment, with an emphasis on preventive care and innovative therapeutic solutions. The market is expected to expand as technological advancements in periodontal treatments continue to evolve.
Market Insights
- The Japan periodontal disease market was valued at USD 1.2 billion in 2023 and is projected to grow at a CAGR of 5.8% from 2024 to 2032.
- Rising awareness about oral health and the increasing prevalence of periodontal diseases among the aging population are driving market growth.
- The expansion of dental clinics and increasing availability of advanced periodontal treatments are also contributing to market development.
- High treatment costs and limited access to advanced care in rural areas pose significant challenges to market growth.
- The growth of cosmetic dentistry, which includes periodontal care, is a key factor in boosting market demand.
- The Kanto and Kansai regions are the major markets for periodontal disease treatments, with high concentrations of healthcare facilities.
- Technological advancements in periodontal treatments and the development of minimally invasive procedures offer significant growth opportunities in the market.
Market Drivers
Aging Population
Japan’s rapidly aging population is a key driver in the growth of the periodontal disease market. A significant proportion of the population is over the age of 65, making elderly individuals more susceptible to periodontal conditions due to natural aging processes and comorbidities. For instance, the World Health Organization (WHO) reports that Japan has the highest proportion of elderly people globally, with over 28% of its population aged 65 and above. As people age, they are more likely to experience oral health issues, including periodontal disease, which leads to an increased demand for periodontal care. This demographic shift emphasizes the need for both preventive and therapeutic solutions, further fueling market growth.
Increased Awareness
Growing awareness about the importance of oral health and its connection to overall systemic health is another crucial factor driving demand for periodontal treatments in Japan. Research has shown that untreated periodontal disease can contribute to a range of other health conditions, such as heart disease and diabetes. For instance, a study published in the Journal of Clinical Periodontology found a significant association between periodontal disease and cardiovascular conditions. As awareness about these links increases, more individuals are seeking preventive care and early intervention for periodontal issues. Public health campaigns and dental education initiatives have played a significant role in shifting public perception and encouraging proactive dental care.
Favorable Healthcare Policies and Infrastructure
Japan’s strong healthcare infrastructure, supported by government policies, plays a critical role in the growth of the periodontal disease market. Government reimbursement schemes for dental treatments and dental insurance coverage make periodontal care more affordable for the public. For instance, Japan's universal health insurance system covers a wide range of dental treatments, making them accessible to a larger portion of the population. Additionally, Japan boasts a well-developed network of qualified periodontists and dentists, ensuring that patients have access to high-quality care. These favorable healthcare policies and the extensive infrastructure contribute to a robust market environment, promoting the availability of advanced periodontal treatments across the nation.
Technological Advancements
Advancements in dental technology are transforming periodontal care in Japan. The introduction of minimally invasive techniques, such as laser treatments and regenerative therapies, has made treatment more accessible, effective, and less painful for patients. These technologies enable quicker recovery times and more precise interventions, which have contributed to a growing preference for professional periodontal care over traditional methods. As these innovations continue to evolve, they are expected to drive further growth in the market, as patients and dental professionals increasingly embrace cutting-edge treatments.
Market Trends
Aging Population and Increased Awareness
Japan’s rapidly aging population is one of the primary drivers of the periodontal disease market. Older individuals are more susceptible to periodontal conditions due to weakened immune systems, decreased salivation, and reduced ability to maintain proper oral hygiene, all of which increase the risk of developing oral diseases. As Japan’s elderly population grows, the demand for periodontal care services continues to rise. In parallel, there is a growing public awareness of the connection between oral health and overall systemic health, which is boosting the demand for preventive and therapeutic treatments. Educational campaigns, media coverage, and public health initiatives have made the link between oral health and chronic conditions like heart disease and diabetes more widely understood. This heightened awareness has prompted more individuals to seek professional care for prevention, early detection, and treatment of periodontal disease, driving further market growth.
Technological Advancements, Healthcare Policies, and Lifestyle Factors
Technological advancements are also playing a significant role in the evolution of periodontal care in Japan. The development of advanced dental technologies, such as laser therapy and platelet-rich plasma (PRP) treatments, is improving the efficacy and accessibility of periodontal treatments. For instance, the use of laser-assisted periodontal therapy has been shown to significantly reduce treatment times and improve patient outcomes. Minimally invasive procedures are gaining popularity due to their shorter recovery times and reduced discomfort, making patients more inclined to opt for treatment. Furthermore, government policies supporting healthcare and reimbursement schemes for dental treatments have made periodontal care more affordable and accessible, encouraging patients to seek timely care. Japan's well-established healthcare infrastructure, including a network of skilled periodontists and dentists, ensures that patients receive high-quality care, which is another key factor driving market growth. Additionally, lifestyle factors such as smoking, poor oral hygiene, and unhealthy diets contribute to the prevalence of periodontal disease. Addressing these factors through public health initiatives and promoting healthier lifestyle choices can help mitigate the disease's impact. As more people become aware of the importance of maintaining good oral hygiene, the demand for periodontal treatments is likely to continue increasing, further bolstering the market.
Market Challenges Analysis
Aging Population and Healthcare Costs
While Japan’s aging population increases the demand for periodontal care, it also presents significant challenges. Elderly individuals often have multiple health conditions, which complicate treatment and require specialized care. Age-related factors, such as weakened immune systems and decreased oral hygiene, further exacerbate periodontal disease, making effective treatment more difficult. Additionally, the financial burden of treating elderly patients, particularly those with complex medical histories, can be considerable. Despite government support, healthcare costs, including dental care, can be high, and insurance coverage for periodontal treatments varies. This disparity in coverage may lead to financial stress for patients, making it difficult for some to access necessary care. These challenges highlight the need for comprehensive healthcare solutions that address both the clinical complexities and financial barriers associated with aging and periodontal disease treatment.
Patient Compliance, Early Detection, and Limited Access
Patient compliance remains a major challenge in managing periodontal disease, particularly when it comes to long-term maintenance. Factors such as busy lifestyles, fear of dental procedures, and a lack of awareness about the importance of consistent care can hinder adherence to treatment plans. Even though awareness of periodontal disease is growing, early detection and prevention are still critical to mitigating its impact. For instance, a study found that compliance with supportive periodontal therapy (SPT) is generally poor, with only 32% of patients fully adhering to their treatment plans. Encouraging regular dental check-ups and promoting better oral hygiene habits are essential in reducing the severity of the disease. Moreover, while Japan’s healthcare infrastructure is strong, access to specialized periodontal care can be limited, especially in rural areas. This geographic disparity often leads to delayed diagnosis and treatment, worsening the condition over time. Cultural and social factors, such as stigma surrounding dental issues, may also prevent individuals from seeking timely care. Overcoming these barriers is crucial for improving overall oral health outcomes and ensuring effective management of periodontal disease across Japan.
Market Opportunities
Expansion of Preventive and Early Intervention Services
One of the key market opportunities for periodontal disease treatment in Japan lies in the expansion of preventive and early intervention services. As awareness about the link between oral health and overall health continues to grow, there is increasing demand for regular check-ups, early detection, and proactive management of periodontal conditions. By promoting routine dental visits and encouraging early intervention, healthcare providers can help prevent the progression of periodontal disease, which is especially important given Japan's aging population. Targeted educational campaigns and partnerships between healthcare providers and government agencies could further boost preventive care adoption, presenting a significant opportunity for the periodontal disease market to grow.
Advancements in Technology and Specialized Treatments
Another opportunity lies in the continued advancement of dental technologies and specialized periodontal treatments. Japan's strong healthcare infrastructure and commitment to innovation create an environment conducive to the adoption of cutting-edge therapies, such as laser treatments, regenerative procedures, and minimally invasive techniques. These innovations not only improve treatment outcomes but also make care more accessible and less painful, appealing to a broader range of patients. Additionally, the growing interest in personalized medicine opens avenues for customized treatment plans, tailored to the individual needs of patients. By embracing these technological advancements, dental professionals in Japan can enhance their service offerings and attract more patients, driving market growth and establishing Japan as a leader in advanced periodontal care.
Market Segmentation Analysis:
By Type:
The Japan periodontal disease market is segmented by type into gingivitis, chronic periodontal disease, aggressive periodontal disease, Type 4, and Type 5. Gingivitis is the most common and mildest form of periodontal disease, typically treated with non-surgical interventions. Chronic periodontal disease, which affects a larger proportion of the population, often requires long-term management and may involve both surgical and non-surgical treatments. Aggressive periodontal disease, less common but more severe, affects younger individuals and demands intensive treatment to prevent tooth loss. Type 4 and Type 5 refer to rarer, more advanced stages of periodontal disease that require specialized care. The treatment approaches for these conditions vary, with chronic and aggressive periodontal disease often requiring a combination of non-surgical and surgical therapies, depending on the severity. The diversity within this segment allows for tailored treatment plans, which contribute to the growth and complexity of the market.
By Application:
The market is also segmented based on application, including non-surgical and surgical treatments. Non-surgical treatments, such as scaling, root planing, and the use of antimicrobial agents, are widely used, especially for milder forms of periodontal disease like gingivitis. These treatments are often sufficient for initial stages, contributing to a large market share. Surgical treatments, on the other hand, are necessary for more advanced stages, including chronic and aggressive periodontal diseases. Procedures like flap surgery, bone grafting, and soft tissue grafts are gaining popularity as patients seek more effective solutions for severe cases. Other emerging applications in this market include advanced laser treatments and regenerative therapies, which offer minimally invasive options with quicker recovery times. These innovative treatments are increasingly sought after, reflecting a shift toward more advanced, patient-friendly care options. As the demand for these specialized treatments grows, they present significant opportunities for the expansion of the periodontal disease market in Japan.
Segments:
Based on Type:
- Gingivitis
- Chronic Periodontal Disease
- Aggressive Periodontal Disease
- Type 4
- Type 5
Based on Application:
- Non-surgical Treatment
- Surgical Treatment
- Application 3
- Application 4
- Application 5
Based on Therapeutics:
- Systematic Antibiotics
- Local Antibiotics
- Therapeutics 3
- Therapeutics 4
- Therapeutics 5
Based on End Users:
- Hospitals
- Dental Clinic
- Dental Academics
- Research Institutes and Others
- End Users 5
Based on Distribution Channel:
- Distribution Channel 1
- Distribution Channel 2
- Distribution Channel 3
- Distribution Channel 4
- Distribution Channel 5
Based on the Geography:
- Kanto Region
- Kansai Region
- Chubu Region
- Kyushu Region
- Other Regions
Regional Analysis
Kanto region
The Kanto region, which includes Tokyo, the capital city of Japan, holds the largest market share in the periodontal disease market. As the most populous and economically developed region, Kanto accounts for a significant proportion of the country's healthcare expenditures, including dental care. The region’s large urban population, high concentration of healthcare facilities, and advanced medical technologies contribute to its dominance in the periodontal disease market. In 2023, Kanto is estimated to hold approximately 40% of the total market share, driven by increased awareness, access to high-quality dental services, and advanced treatment options. The presence of leading dental hospitals and specialized periodontal centers in Tokyo ensures that residents have access to cutting-edge care, fostering demand for both preventive and advanced periodontal treatments. Furthermore, the high-income demographics and a large percentage of elderly individuals within the region further drive the market for periodontal disease management. The growing trend of health-conscious urban populations, combined with strong government and private healthcare infrastructure, positions Kanto as the most lucrative region for periodontal disease care in Japan.
Kansai Region
The Kansai region, which includes Osaka, Kyoto, and Kobe, is the second-largest market for periodontal disease treatment in Japan, holding around 30% of the market share. Known for its rich cultural heritage and high population density, Kansai’s periodontal disease market is fueled by the region’s urbanized nature and a rapidly aging population. Osaka, as the economic hub of the region, has a high demand for both general and specialized dental treatments, contributing significantly to the market’s growth. Despite its smaller population compared to Kanto, Kansai benefits from a robust healthcare infrastructure, including numerous dental clinics, private practices, and hospitals that provide both non-surgical and surgical treatments for periodontal conditions. Moreover, Kansai’s focus on public health initiatives and dental education has led to greater awareness about periodontal disease and its impact on overall health, driving demand for preventive care and early intervention. The growing adoption of innovative treatment options, such as laser therapies and regenerative treatments, further boosts the market in this region. Overall, the Kansai region’s well-developed healthcare sector and aging demographic make it a significant player in the periodontal disease market, with consistent growth expected over the forecast period.
Key Player Analysis
- Bausch Health Companies Inc
- Yoshida Dental Manufacturing Co., Ltd.
- Tokyo International Clinic
- Lyne Laboratories
- WOCKHARDT
- DENTSPLY SIRONA Inc
- 3M
- Amyndas Pharmaceuticals
- Biolase, Inc
- Company 10
- Company 11
- Company 12
- Company 13
- Company 14
Competitive Analysis
The competitive landscape of the Japan periodontal disease market is marked by the presence of several prominent players, each contributing to the growth and development of the industry. Leading companies such as Bausch Health Companies Inc., Yoshida Dental Manufacturing Co., Ltd., Tokyo International Clinic, Lyne Laboratories, WOCKHARDT, DENTSPLY SIRONA Inc., 3M, Amyndas Pharmaceuticals, Biolase, Inc., and others are actively involved in offering a wide range of periodontal disease treatments and therapies. Companies in this market are focusing on technological advancements and product innovations, such as laser therapies, non-surgical treatments, and antibiotic-based solutions, to address the growing demand for effective periodontal disease management. Strategic initiatives, including mergers, acquisitions, and new product launches, have helped businesses strengthen their market presence. The market is also witnessing increased collaboration between manufacturers and dental clinics, ensuring greater accessibility to advanced treatments. Moreover, the shift towards cosmetic dentistry and the growing awareness about oral health are driving the demand for periodontal care. Companies are emphasizing differentiated offerings, such as personalized treatment plans and minimally invasive procedures, to cater to the diverse needs of patients. As the market grows, there is a strong focus on educating consumers and healthcare professionals, further intensifying competition. The continued evolution of dental technologies and an expanding customer base contribute to the competitive intensity within the industry.
Recent Developments
- In September 2023, Bausch Health Companies Inc. and its oral health care division, OraPharma announced plans to team up with the League of United Latin American Citizens (LULAC), the biggest Hispanic group in the U.S. Their goal is to spread awareness about gum disease among Hispanic communities. This collaboration aims to help Hispanics better understand how to detect and treat gum disease.
- In June 2023, Eli Lilly and Company finalized an agreement to acquire DICE Therapeutics, Inc., a renowned biopharmaceutical firm recognized for its groundbreaking DELSCAPE technology platform. This platform is instrumental in creating novel oral therapeutic candidates, such as oral IL-17 inhibitors, which are presently in clinical development. These treatments are designed to target chronic immune-related diseases.
- In March 2023, Haleon initiated the #BetterOralCareNation campaign in Malaysia to enhance oral health practices across the country. The campaign seeks to raise awareness about the importance of oral hygiene and promote better oral care habits among Malaysians.
- In April 2023, Novo Nordisk collaborated with Aspect Biosystems, a company involved in bioprinting biomaterials, for the development of bioprinted tissue therapeutics for obesity and diabetes.
- In March 2022, Biocomposites signed an agreement with Zimmer Biomet to distribute the new genex Bone Graft Substitute. Genex Bone Graft Substitute is a biphasic composite of exceptional purity specifically formulated to balance osteoconductive scaffold strength and persistence in the body to enable the optimal remodeling of bone architecture.
- In February 2022, Envista Holding Corporation formed a strategic partnership with the Spanish Dental Service Organization- Vitaldent Group. This helps the company to become the preferred supplier of dental implants.
Market Concentration & Characteristics
The Japan periodontal disease market exhibits a moderately concentrated structure, with a mix of established players and emerging entities vying for market share. This market is characterized by the increasing adoption of advanced diagnostic tools and treatment methods, which are driven by growing consumer awareness and rising demand for effective oral health solutions. Market participants are strategically focusing on innovation, leveraging minimally invasive techniques and advanced therapeutics to cater to diverse patient needs. The presence of specialized clinics and well-developed healthcare infrastructure further supports the competitive dynamics. Despite the dominance of a few established companies, smaller and regional players are carving out niches by offering tailored solutions and localized services. The market also reflects characteristics of high regulatory oversight, emphasizing quality standards and patient safety, which influence product development and market entry strategies. Collaborations between dental care providers and technology developers are fostering advancements in treatment modalities. Additionally, a noticeable trend is the integration of cosmetic dentistry with periodontal treatments, which broadens the market's appeal. While competition remains robust, a shared emphasis on addressing the growing prevalence of periodontal diseases ensures consistent growth opportunities across the sector. The market's dynamic nature underscores its ability to adapt to evolving consumer and healthcare demands.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Therapeutics, End Users, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market for periodontal disease in Japan is expected to grow steadily due to increased awareness about oral health.
- Advancements in diagnostic technologies will enhance early detection and improve treatment outcomes.
- Rising adoption of minimally invasive and non-surgical treatment options will drive market growth.
- Integration of AI and digital tools in dental practices will streamline procedures and improve patient experiences.
- Collaboration between healthcare providers and technology companies will foster innovation in periodontal care.
- A growing focus on preventive care will encourage the adoption of personalized treatment plans.
- Expansion of cosmetic dentistry will align with periodontal treatments to meet aesthetic and health-related demands.
- Increased government and private sector investment in oral healthcare will support market development.
- The aging population in Japan will lead to higher demand for periodontal disease treatments.
- Regulatory updates emphasizing quality and safety will shape product innovation and market dynamics.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Japan Periodontal Disease market?
What factors are driving the growth of the Japan Periodontal Disease market?
What are the key segments within the Japan Periodontal Disease market?
What are some challenges faced by the Japan Periodontal Disease market?
Who are the major players in the Japan Periodontal Disease market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Periodontal Disease Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan Periodontal Disease Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 182.12 million → 2032: USD 324.70 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Periodontal Disease Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Periodontal Disease Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Periodontal Disease Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan Periodontal Disease Market Drivers
- 3.3 Japan Periodontal Disease Market Restraints & Challenges
- 3.4 Japan Periodontal Disease Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Periodontal Disease Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Periodontal Disease Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Periodontal Disease category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Periodontal Disease Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan Periodontal Disease Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan Periodontal Disease market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Periodontal Disease Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan Periodontal Disease Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan Periodontal Disease Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Periodontal Disease (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan Periodontal Disease Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan Periodontal Disease Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan Periodontal Disease Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan Periodontal Disease Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan Periodontal Disease Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan Periodontal Disease Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan Periodontal Disease Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan Periodontal Disease Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan Periodontal Disease Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
