
Market Overview:
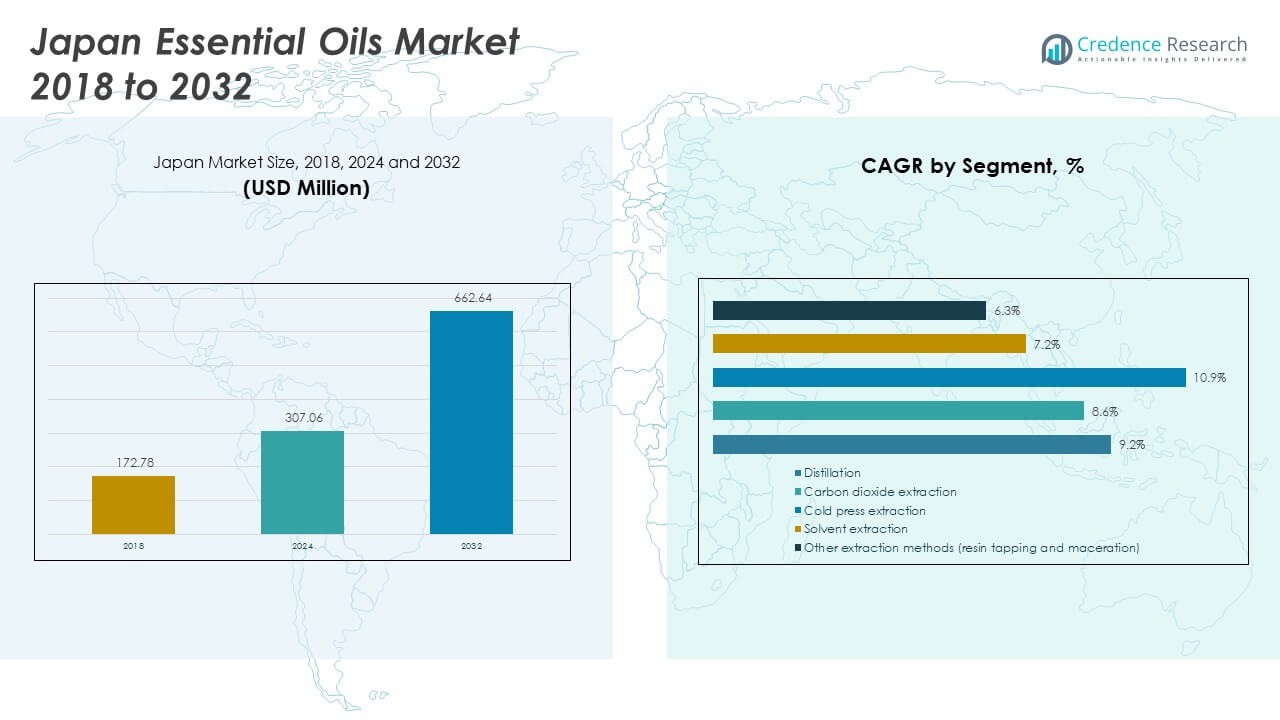
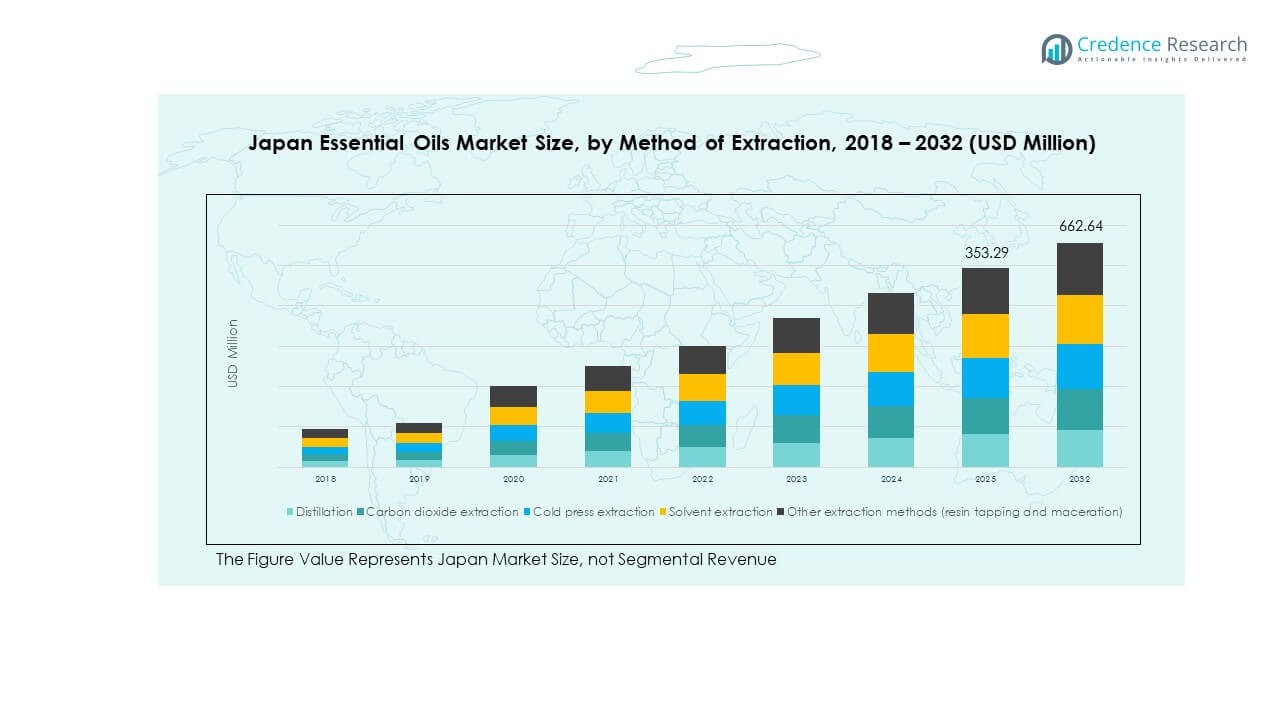
The Japan Wood Essential Oils Market size was valued at USD 172.78 million in 2018 to USD 307.06 million in 2024 and is anticipated to reach USD 662.64 million by 2032, at a CAGR of 9.40% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Japan Wood Essential Oils Market Size 2024 | USD 307.06 Million |
| Japan Wood Essential Oils Market, CAGR | 9.40% |
| Japan Wood Essential Oils Market Size 2032 | USD 662.64 Million |
Growth in the Japan Wood Essential Oils Market is driven by rising consumer demand for natural and sustainable wellness products. Expanding applications in cosmetics, aromatherapy, pharmaceuticals, and personal care are pushing adoption. Increasing awareness of health benefits, combined with Japan’s strong cultural preference for natural remedies, enhances market penetration. Manufacturers are investing in advanced extraction methods to improve oil quality and yield. Rising disposable income and premium product demand also support growth.
Regional growth in the Japan Wood Essential Oils Market reflects Asia-Pacific dominance due to cultural heritage and manufacturing strength. Japan leads with a strong domestic base in personal care and wellness, while China and India are emerging with expanding essential oil exports and rising domestic demand. North America and Europe remain secondary markets, driven by aromatherapy and organic product adoption. Emerging economies in Southeast Asia are beginning to show strong interest due to rising wellness trends and expanding middle-class populations.
Market Insights:
- The Japan Wood Essential Oils Market was USD 172.78 million in 2018, USD 307.06 million in 2024, and is projected to reach USD 662.64 million by 2032, growing at a CAGR of 9.40%.
- North America held a 32% share in 2024, driven by wellness culture and aromatherapy demand; Europe captured 28% with strong cosmetic and pharmaceutical applications; Asia-Pacific followed with 25% due to cultural heritage and rising local production.
- Asia-Pacific is the fastest-growing region, supported by domestic demand in Japan, expanding exports from China and India, and wellness tourism growth in Southeast Asia.
- Distillation accounted for 52% of extraction share in 2024, reflecting its dominance as a cost-effective and widely accepted method.
- Carbon dioxide extraction represented 18% share, gaining traction as a clean, solvent-free process appealing to premium and eco-conscious markets.
Market Drivers:
Rising Demand for Natural Health and Wellness Solutions:
The Japan Wood Essential Oils Market benefits from the increasing preference for natural and plant-based health alternatives. Consumers in Japan value traditional remedies and holistic therapies, creating steady demand. Aromatherapy, stress relief, and mental wellness practices continue to push consumption. Companies focus on clean-label and organic oils to meet stricter consumer expectations. Expansion in wellness tourism also supports usage in spas and therapeutic centers. It is witnessing high adoption in both personal and commercial spaces.
- For instance, Japan Aroma Laboratory Co., Ltd. developed a vacuum-controlled microwave-assisted extraction system for Abies sachalinensis essential oil in Hokkaido that shortens extraction duration and enhances energy efficiency while maintaining oil purity.
Expanding Applications in Cosmetics and Personal Care Industry:
Cosmetics and skincare brands are integrating wood essential oils into their product lines for fragrance, therapeutic, and preservative properties. Demand for eco-friendly and sustainable ingredients aligns with Japanese consumer expectations for safety and purity. Premium beauty segments use essential oils to differentiate offerings. Rising interest in natural perfumes and organic skincare pushes wider adoption. Leading brands in Japan highlight wood essential oils in marketing campaigns to capture health-conscious buyers.
- For instance, Shiseido utilizes an Internet of Things (IoT) skincare service brand called Optune, which was introduced to deliver personalized skincare. The at-home skin analyzer and product dispenser system customizes skincare by analyzing skin conditions and environmental factors in real-time, dispensing one of over 80,000 possible combinations of serums and lotions.
Growing Adoption in Food and Beverage and Pharmaceutical Sectors:
The Japan Wood Essential Oils Market is also supported by use in flavoring agents, nutraceuticals, and herbal supplements. Pharmaceutical industries employ oils for antimicrobial and therapeutic properties. Functional foods and beverages incorporate essential oils to enhance both health benefits and taste. Strong government support for wellness-focused innovations adds momentum. Rising investment in research further drives adoption across new formulations.
Technological Advancements in Extraction Methods:
Innovation in distillation and cold-press extraction boosts oil yield and quality. Advanced technologies help reduce energy consumption and preserve active compounds. Japanese companies invest in modernized facilities to compete globally. Efficiency improvements lower costs and enhance competitiveness. Carbon dioxide extraction and solvent-free processes gain prominence as eco-friendly solutions. It supports scalability and caters to international quality standards, improving Japan’s export potential.
Market Trends:
Rising Popularity of Aromatherapy and Wellness Tourism:
The Japan Wood Essential Oils Market is strongly influenced by the global surge in aromatherapy practices. Spas, wellness retreats, and healthcare centers in Japan integrate essential oils for holistic therapies. Demand grows among younger populations seeking natural stress relief. Tourism-driven consumption adds further momentum as wellness experiences feature essential oils. Expanding wellness culture strengthens long-term adoption.
- For instance, the spa industry in Tokyo has seen increased interest in wellness services incorporating sustainable practices. Some high-end spas have noted growing client demand for natural and ethically-sourced essential oils, including popular scents like cedarwood and sandalwood, reflecting broader consumer preferences in 2024 for eco-friendly wellness products.
Increasing Shift Toward Sustainable and Ethical Sourcing:
Japanese consumers are highly conscious of ethical sourcing and environmental sustainability. Market players emphasize eco-friendly harvesting and transparent supply chains. Certification standards ensure authenticity and quality. Brands highlight sustainable sourcing practices to gain consumer trust. Rising imports of certified organic oils reflect these preferences. It strengthens the brand value of ethical suppliers in the Japanese market.
- For instance, Ryohin Keikaku Co., Ltd. (MUJI) promotes a commitment to sustainable wood procurement, which is part of its broader ESG strategy. The company's initiatives include a focus on using certified wood (such as FSC, PEFC, and SGEC) and ensuring traceability. In practice, this aligns with Japan’s efforts toward legal timber sourcing, like the Clean Wood Act, which promotes sustainable forestry and supports local timber industries.
Expansion of Online Distribution Channels:
E-commerce platforms and direct-to-consumer strategies reshape access to wood essential oils. Online retail offers broader product visibility and competitive pricing. Japanese consumers rely on digital platforms for premium and niche essential oils. Rising mobile commerce further accelerates this trend. Companies optimize digital marketing to capture health-conscious millennials. Subscriptions and bundled wellness kits expand online sales.
Product Innovation with Functional and Premium Blends:
Manufacturers create innovative blends targeting specific health outcomes such as relaxation, immunity, or skincare. Premiumization trends emphasize luxury packaging and customized formulations. Functional blends appeal to younger, urban populations seeking convenience. Japanese brands introduce hybrid offerings combining essential oils with cosmetics or supplements. This innovation diversifies revenue streams and sustains market momentum.
Market Challenges Analysis:
Regulatory Compliance and Quality Standardization Issues:
The Japan Wood Essential Oils Market faces challenges from strict government regulations and varying global standards. Companies must meet rigorous quality, purity, and labeling requirements. Non-compliance risks rejection of imports and damages credibility. Counterfeit and adulterated products add further complexity, affecting consumer trust. Standardization efforts are vital but costly, pushing smaller players at risk.
Price Volatility and Supply Chain Constraints:
Fluctuating raw material costs pose challenges for stable pricing. Climate change, seasonal harvests, and limited sourcing regions disrupt supply reliability. Import dependency raises exposure to currency fluctuations and trade barriers. Smaller producers struggle with scalability and stable raw material access. Global competition for sustainable wood oils increases pressure on Japan’s local suppliers.
Market Opportunities:
Rising Demand for Premium and Organic Oils:
The Japan Wood Essential Oils Market is gaining from premium consumer segments seeking organic and therapeutic oils. High-income groups and wellness-focused customers drive demand for certified natural oils. Brands offering premium, eco-friendly, and ethically sourced oils capture strong loyalty.
Growing Export Potential and Regional Expansion:
Japanese companies have opportunities to expand exports across Asia-Pacific and Western markets. Rising demand in emerging countries creates new distribution channels. Strategic alliances with global cosmetic and pharmaceutical brands enhance international footprint. Investments in export-focused facilities support long-term growth.
Market Segmentation Analysis:
By Type
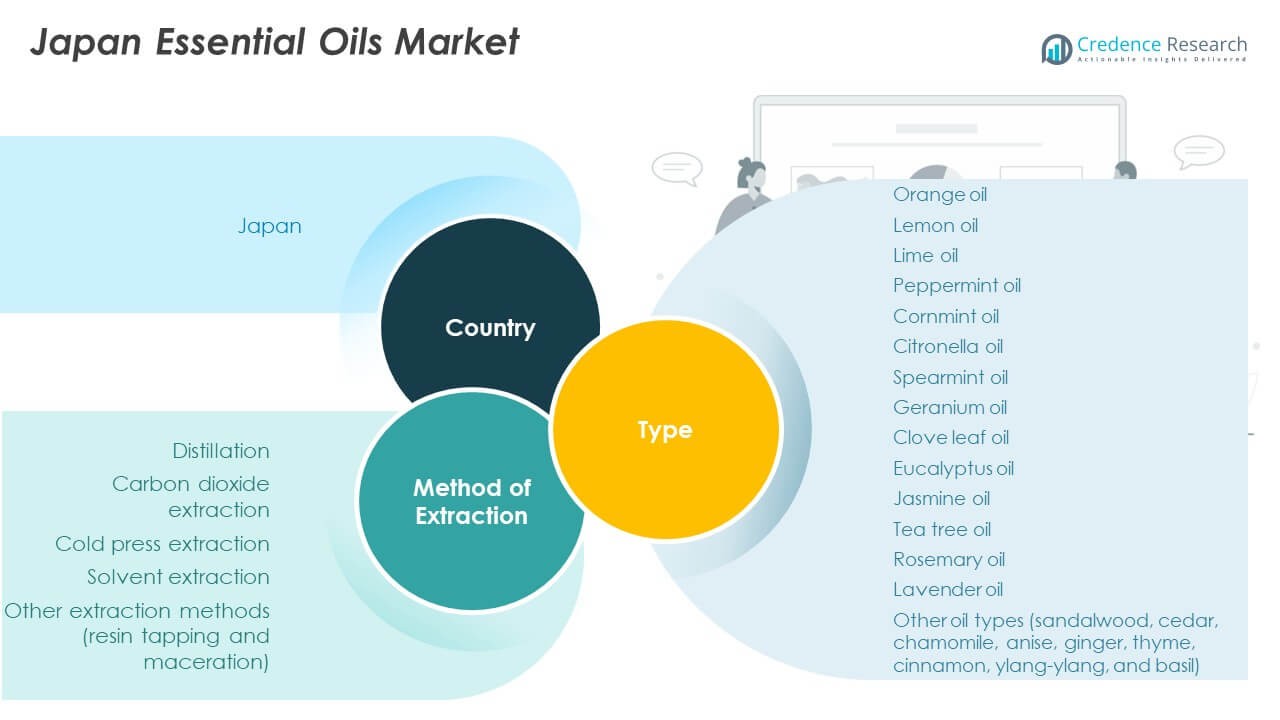
The Japan Wood Essential Oils Market is segmented into citrus oils such as orange and lemon, along with peppermint, lavender, eucalyptus, sandalwood, cedar, and other specialty oils. Citrus oils dominate due to their widespread use in cosmetics, food flavoring, and aromatherapy. Premium oils such as sandalwood and cedar attract strong demand in luxury skincare and wellness products, reinforcing Japan’s preference for high-quality natural ingredients. Lavender and rosemary are popular in therapeutic applications, while peppermint and tea tree oils maintain steady use in personal care and pharmaceutical products.
By Method of Extraction
Distillation holds the leading share due to its efficiency and traditional acceptance in Japan. It remains cost-effective for mass-market citrus oils while maintaining quality. Carbon dioxide extraction and cold press methods are growing, supported by demand for solvent-free and eco-friendly oils. Solvent extraction caters to specialized segments requiring higher yield or unique compounds. Other methods, including resin tapping and maceration, remain niche but serve premium and artisanal markets.
- For instance, he hinoki wood distillation plants use steam distillation to extract wood essential oils prized for their calming properties, optimizing extraction efficiency while ensuring environmental sustainability.
Competitive Landscape within Segments
Companies differentiate by focusing on premium oil categories and advanced extraction processes. Japanese players invest in technology-driven methods to maintain purity and sustainability. Global suppliers’ partner with local distributors to enhance availability and tap into the premium consumer base. The segmentation structure reflects a balance between high-volume citrus oils and niche, high-value wood oils, ensuring long-term market diversity and growth.
Segmentation:
By Type
- Orange Oil
- Lemon Oil
- Lime Oil
- Peppermint Oil
- Cornmint Oil
- Citronella Oil
- Spearmint Oil
- Geranium Oil
- Clove Leaf Oil
- Eucalyptus Oil
- Jasmine Oil
- Tea Tree Oil
- Rosemary Oil
- Lavender Oil
- Other Oils (sandalwood, cedar, chamomile, anise, ginger, thyme, cinnamon, ylang-ylang, basil)
By Method of Extraction
- Distillation
- Carbon Dioxide Extraction
- Cold Press Extraction
- Solvent Extraction
- Other Methods (resin tapping, maceration)
Regional Analysis:
Japan: Core Market Strength (40% share)
The Japan Wood Essential Oils Market dominates the regional landscape with around 40% share in 2024. Strong cultural heritage in natural wellness, advanced cosmetic industries, and premium product positioning drive this lead. Companies leverage strict quality standards and innovative extraction methods to secure consumer trust. Rising demand in aromatherapy, skincare, and pharmaceuticals strengthens domestic consumption. It continues to grow steadily as essential oils become embedded in daily wellness practices.
China and India: Emerging Growth Hubs (35% share combined)
China and India together account for nearly 35% of the regional share, supported by their roles as both producers and consumers. China benefits from expanding cosmetics and food industries, alongside robust export capacity. India leverages its ayurvedic tradition and cost-efficient production to supply domestic and global markets. Urban consumers in both countries are showing increasing preference for organic and premium oils. It highlights their dual role in fueling regional consumption and strengthening supply chains.
Southeast Asia: Expanding Wellness Tourism Demand (15% share)
Southeast Asia, led by Thailand, Indonesia, and Malaysia, holds about 15% share of the market. Growth is driven by wellness tourism, with spas and resorts integrating wood essential oils into therapies. Rising disposable incomes and cultural affinity for natural remedies support demand expansion. Japanese imports are valued for their purity and premium quality, reinforcing brand trust. It positions Southeast Asia as a fast-emerging cluster within the broader Asia-Pacific market.
Key Player Analysis:
- Ogawa & Co., Ltd.
- Wellnesskit Co Ltd
- Yugen Kaisha YS Kikaku
- Aethon International LLP
- Arora Aromatics
- Hetaksh Essential Oils
- EMS International Trading Co Ltd
- MIKI
- Essential Oil Company Japan
- Others
Competitive Analysis:
The Japan Wood Essential Oils Market features intense competition among domestic and global companies. Ogawa & Co., Ltd., Wellnesskit Co Ltd, and Yugen Kaisha YS Kikaku lead with strong local networks and premium portfolios. International players like Arora Aromatics and EMS International Trading Co Ltd compete with wide distribution. Companies emphasize sustainability, organic certifications, and advanced extraction methods to gain share. Differentiation relies on branding, quality assurance, and supply chain transparency. Price competition and innovation define strategic positioning. It demonstrates a fragmented but dynamic competitive structure where niche players thrive alongside established corporations.
Recent Developments:
- In January 2025, Ogawa & Co., Ltd., a comprehensive manufacturer of essential oils, extracts, flavors, and fragrances in Japan, continues to promote the charms of Japan through its products, emphasizing its position as a key player in the essential oils market.
- Hetaksh Essential Oils is a leading B2B supplier of natural essential and carrier oils serving more than 40 countries as of mid-2025 and continues to offer premium products, although no new launches or partnerships specific to Japan were reported at this time.
Report Coverage:
The research report offers an in-depth analysis based on type and method of extraction. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for natural and organic essential oils
- Expansion of aromatherapy in wellness tourism
- Growth of premium and luxury oil segments
- Wider adoption in cosmetics and personal care
- Increasing role in pharmaceuticals and nutraceuticals
- Strong export opportunities in Asia-Pacific and Western markets
- Technological improvements in extraction methods
- Rising consumer focus on sustainability and traceability
- Growth of online and direct-to-consumer channels
- Increasing innovation in functional oil blends

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for Natural and Sustainable Wellness Products
Japanese consumers are increasingly seeking natural, plant-based alternatives for health and wellness, driven by cultural preferences for traditional remedies and holistic therapies. This trend is fueling steady growth in essential oil consumption across personal and commercial spaces.
Expanding Applications in Cosmetics, Personal Care, and Pharmaceuticals
Wood essential oils are being integrated into cosmetics, skincare, and pharmaceutical products for their fragrance, therapeutic, and preservative properties. The demand for eco-friendly and premium ingredients aligns with consumer expectations for safety, purity, and efficacy.
Technological Advancements in Extraction Methods
Manufacturers are investing in advanced extraction technologies such as vacuum-controlled microwave-assisted systems and carbon dioxide extraction. These innovations improve oil yield, purity, and energy efficiency, supporting both quality and sustainability goals.
Growth of Wellness Tourism and Aromatherapy
Japan’s spa and wellness tourism sectors are increasingly incorporating essential oils into their offerings, attracting both domestic and international consumers. The popularity of aromatherapy for stress relief and mental wellness is further boosting market adoption.
Increasing Focus on Sustainability and Ethical Sourcing
Japanese consumers and brands are highly conscious of environmental impact and ethical sourcing. Companies emphasize transparent supply chains, certified organic oils, and sustainable harvesting practices, which enhance brand trust and market differentiation.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Japan Wood Essential Oils Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Japan Wood Essential Oils Market projected to grow between 2025 and 2032?
Which Japan Wood Essential Oils Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Japan Wood Essential Oils Market?
Who are the leading companies in the Japan Wood Essential Oils Market?
Which region commanded the largest share of the Japan Wood Essential Oils Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Orange Oil
- 1.2.2 Lemon Oil
- 1.2.3 Peppermint Oil
- 1.2.4 Eucalyptus Oil
- 1.2.5 Sandalwood Oil
- 1.2.6 Cedar Oil
- 1.2.7 Lavender Oil
- 1.2.8 Other Oils (chamomile, anise, ginger, thyme, cinnamon, ylang-ylang, basil)
- 1.3 By Application
- 1.3.1 Cosmetics & Personal Care
- 1.3.2 Aromatherapy
- 1.3.3 Pharmaceuticals
- 1.3.4 Food & Beverage
- 1.3.5 Wellness Tourism
- 1.4 By Method of Extraction
- 1.4.1 Distillation
- 1.4.2 Carbon Dioxide Extraction
- 1.4.3 Cold Press Extraction
- 1.4.4 Solvent Extraction
- 1.4.5 Other Methods (resin tapping, maceration)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 172.78 million → 2032: USD 662.64 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Japan Wood Essential Oils Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Japan Wood Essential Oils Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Japan Wood Essential Oils Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Japan Wood Essential Oils Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Japan Wood Essential Oils Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Japan Wood Essential Oils Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Japan Wood Essential Oils Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Japan Wood Essential Oils Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 172.78 million → 2032: USD 662.64 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Japan Wood Essential Oils Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Orange Oil
- 12.3.7.2 Lemon Oil
- 12.3.7.3 Peppermint Oil
- 12.3.7.4 Eucalyptus Oil
- 12.3.7.5 Sandalwood Oil
- 12.3.7.6 Cedar Oil
- 12.3.7.7 Lavender Oil
- 12.3.7.8 Other Oils (chamomile, anise, ginger, thyme, cinnamon, ylang-ylang, basil)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cosmetics & Personal Care
- 12.4.7.2 Aromatherapy
- 12.4.7.3 Pharmaceuticals
- 12.4.7.4 Food & Beverage
- 12.4.7.5 Wellness Tourism
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Method of Extraction - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Distillation
- 12.5.7.2 Carbon Dioxide Extraction
- 12.5.7.3 Cold Press Extraction
- 12.5.7.4 Solvent Extraction
- 12.5.7.5 Other Methods (resin tapping, maceration)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Japan Wood Essential Oils End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Japan Wood Essential Oils Geographic Market Outlook, 2018-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2018-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Japan Wood Essential Oils Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Japan Wood Essential Oils Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Ogawa & Co., Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Wellnesskit Co Ltd
- 18.4 Yugen Kaisha YS Kikaku
- 18.5 Aethon International LLP
- 18.6 Arora Aromatics
- 18.7 Hetaksh Essential Oils
- 18.8 EMS International Trading Co Ltd
- 18.9 MIKI
- 18.10 Essential Oil Company Japan
- 18.11 Ryohin Keikaku Co., Ltd. (MUJI)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

