
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Lateral Flow Assay Component Market Size 2024 | USD 388.1 million |
| Lateral Flow Assay Component Market, CAGR | 4.6% |
| Lateral Flow Assay Component Market Size 2032 | USD 556.15 million |
Market Overview:
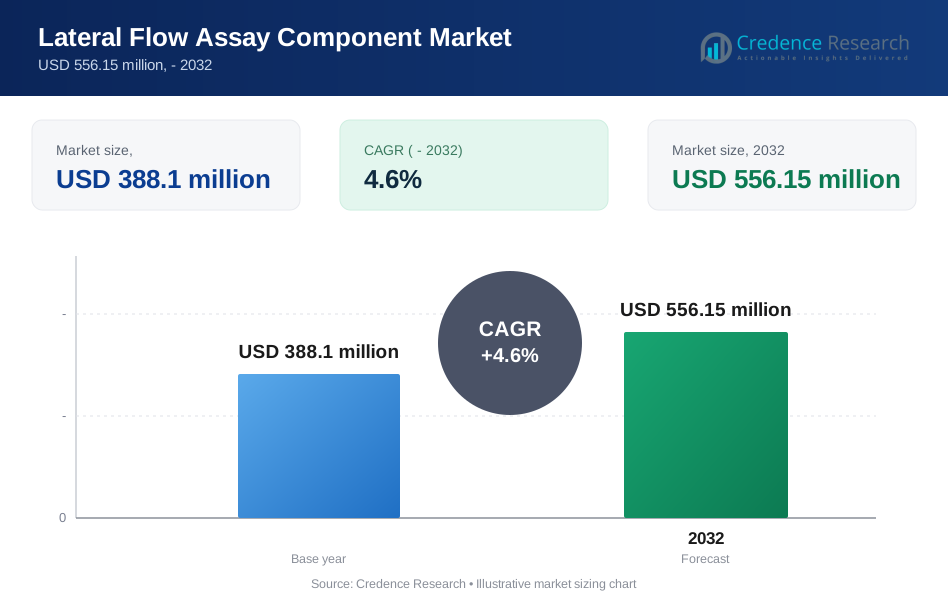
The Lateral Flow Assay Component Market is projected to grow from USD 388.1 million in 2024 to an estimated USD 556.15 million by 2032, with a compound annual growth rate (CAGR) of 4.6% from 2024 to 2032.
Market drivers include the widespread demand for point-of-care testing (POCT), driven by the need for fast and accurate diagnostic solutions, especially in underserved regions. The COVID-19 pandemic significantly accelerated the adoption of lateral flow assay components, highlighting their value in large-scale diagnostic programs. Additionally, rising healthcare expenditure, technological advancements in assay designs, and the increasing prevalence of chronic diseases like diabetes and cardiovascular conditions are key contributors to market growth. Innovations in microfluidics and biosensors are further enhancing the sensitivity and specificity of lateral flow assays, creating opportunities for broader applications in clinical diagnostics, environmental testing, and drug development. These trends underline the pivotal role of lateral flow assays in addressing global health challenges and supporting personalized medicine initiatives.
Regionally, North America dominates the market, accounting for the largest share due to a well-established healthcare infrastructure, robust R&D capabilities, and substantial healthcare spending. In the United States, the growing demand for innovative diagnostic solutions and favorable government policies supporting healthcare advancements further drive market growth. Europe follows closely, with countries such as Germany, the United Kingdom, and France leading the adoption of lateral flow assays, spurred by the increasing prevalence of chronic diseases and government initiatives promoting rapid diagnostics. The Asia-Pacific region is anticipated to witness the fastest growth during the forecast period, fueled by rising healthcare awareness, expanding diagnostic capabilities, and significant investments in healthcare infrastructure in countries like China, India, and Japan. Emerging markets in Latin America and the Middle East & Africa are also showing promise, supported by improving access to healthcare services, growing awareness of early disease detection, and increasing investments in diagnostic technologies by both public and private sectors.
Market Insights:
- The market is projected to grow from USD 388.1 million in 2024 to USD 556.15 million by 2032, with a CAGR of 4.6%, fueled by rising demand for point-of-care testing (POCT).
- Technological advancements in microfluidics and biosensors are significantly enhancing the sensitivity and specificity of lateral flow assays, enabling broader diagnostic applications.
- The COVID-19 pandemic highlighted the importance of lateral flow assays in large-scale diagnostic programs, accelerating their adoption in healthcare systems worldwide.
- North America dominates the market, holding the largest share due to advanced healthcare infrastructure, substantial R&D investments, and high diagnostic awareness.
- The Asia-Pacific region is witnessing the fastest growth, driven by healthcare infrastructure improvements, rising awareness, and significant investments in countries like China and India.
- Growing applications in food safety, environmental testing, and veterinary diagnostics are diversifying market opportunities beyond healthcare.
- Challenges such as supply chain dependencies, limited sensitivity, and regulatory complexities present hurdles but also opportunities for innovation and strategic partnerships.
Market Drivers:
Rising Demand for Point-of-Care Testing (POCT)
The increasing demand for point-of-care testing (POCT) is a primary driver of the lateral flow assay component market. Healthcare providers and consumers alike value the speed, convenience, and portability of these diagnostic tools. For instance, Abbott's BinaxNOW COVID-19 Ag Card provides results in just 15 minutes, making it a critical tool in managing the pandemic. Lateral flow assays are particularly effective in resource-limited settings where access to centralized laboratories may be constrained. They enable rapid decision-making, which is critical in emergencies, outbreak responses, and routine monitoring of chronic conditions. The adoption of these assays in home testing for conditions such as diabetes, infectious diseases, and pregnancy has further fueled market growth, supported by technological advancements enhancing their accuracy and reliability.
Growing Prevalence of Chronic and Infectious Diseases
The rising incidence of chronic and infectious diseases globally has created a significant need for efficient diagnostic tools like lateral flow assays. Chronic conditions such as diabetes, cardiovascular diseases, and cancer require continuous monitoring, and lateral flow assays offer a user-friendly solution for regular testing. For example, Roche's Accu-Chek Guide system is widely used for diabetes management, providing quick and accurate blood glucose readings. The outbreak of COVID-19 demonstrated the critical role these assays play in large-scale screening, surveillance, and early detection. Beyond pandemic applications, the market is driven by increasing awareness of early disease diagnosis and preventive healthcare, with governments and organizations prioritizing investment in diagnostic technologies to mitigate disease burden and healthcare costs.
Technological Advancements Enhancing Performance
Advancements in technology have significantly improved the performance and versatility of lateral flow assays, driving market adoption. Innovations in nanotechnology, biosensors, and microfluidics have enhanced assay sensitivity, specificity, and multiplexing capabilities, allowing for the detection of multiple analytes in a single test. For instance, the use of gold nanoparticles in lateral flow assays has improved the visual detection of test results. These advancements have expanded the scope of lateral flow assays beyond clinical diagnostics to applications in food safety, environmental testing, and veterinary medicine. Moreover, manufacturers are focusing on integrating digital readers and connectivity features, enabling real-time data sharing and remote monitoring, which aligns with the growing trend toward personalized and connected healthcare solutions.
Increased Investments in Research and Development
Growing investments in research and development by public and private entities are fostering innovation in lateral flow assay components. Companies are prioritizing the development of advanced materials such as high-performance membranes, labels, and reagents to improve assay efficiency. For example, Ahlstrom-Munksjö has developed new absorbent and conjugate pads designed for lateral flow immunoassays, enhancing their reliability and consistency. Simultaneously, governments and global health organizations are funding initiatives aimed at enhancing diagnostic accessibility in low-income regions. These investments have resulted in the introduction of cost-effective, robust, and user-friendly lateral flow assay solutions, which cater to both developed and developing markets. The focus on R&D underscores the commitment to addressing unmet diagnostic needs and adapting to emerging health challenges, further driving the market's growth trajectory.
Market Trends:
Shift Toward Multiplexing Capabilities
A prominent trend in the lateral flow assay component market is the development and adoption of multiplexing technologies. These advancements enable the detection of multiple analytes in a single test, providing comprehensive diagnostic insights with minimal effort. For instance, Abingdon Health has developed multiplex lateral flow tests that can simultaneously detect multiple pathogens, significantly enhancing diagnostic efficiency. This trend is particularly evident in applications such as infectious disease diagnostics, where simultaneous testing for multiple pathogens is critical. The integration of multiplexing into lateral flow assays enhances their efficiency and reduces the need for repeat testing, saving time and costs for healthcare providers. This capability is increasingly being utilized in research settings, food safety monitoring, and veterinary diagnostics, further broadening the scope of lateral flow assay applications.
Rising Adoption of Digital and Connected Devices
Digitalization is transforming the lateral flow assay market, with manufacturers incorporating digital readers and connectivity features into their products. For instance, Abbott's BinaxNOW COVID-19 Ag Card Home Test includes a digital reader that allows real-time data collection, interpretation, and sharing. These enhancements allow real-time data collection, interpretation, and sharing, enabling remote patient monitoring and integration with healthcare systems. This trend aligns with the growing emphasis on personalized medicine and telehealth solutions. Digital readers improve the accuracy of test results by eliminating subjective interpretation, while connectivity features enable data tracking and analytics for better disease management. The convergence of lateral flow assays with digital health technologies is fostering innovation and expanding their utility in both clinical and non-clinical settings.
Growing Emphasis on Environmental and Food Safety
The use of lateral flow assays is expanding beyond traditional healthcare applications into areas such as environmental monitoring and food safety. For example, Neogen's Reveal 3-D for Gluten test provides rapid, reliable, and cost-effective solutions for detecting contaminants, pathogens, and allergens in food products and environmental samples. These assays provide rapid, reliable, and cost-effective solutions for detecting contaminants, pathogens, and allergens in food products and environmental samples. With increasing regulatory scrutiny and consumer demand for transparency in food production and safety, industries are adopting lateral flow assays to ensure compliance and maintain quality standards. Similarly, the need for quick and portable testing methods in environmental monitoring is driving the adoption of these assays for water quality assessment, pollution tracking, and detection of hazardous substances.
Focus on Sustainable and Cost-Effective Solutions
Sustainability is emerging as a key trend in the lateral flow assay component market, with manufacturers prioritizing the development of eco-friendly and cost-effective products. Innovations in biodegradable materials, such as cellulose-based membranes, are gaining traction as companies respond to environmental concerns. For instance, companies like Merck are developing cellulose-based membranes for lateral flow assays to reduce environmental impact. Additionally, efforts to streamline manufacturing processes and reduce material waste are helping lower production costs, making these assays more accessible to resource-constrained regions. The focus on sustainability aligns with global initiatives to promote environmentally responsible practices and enhances the market appeal of lateral flow assays across diverse sectors.
Market Challenges Analysis:
Limited Sensitivity and Specificity
One of the primary challenges in the lateral flow assay component market is the inherent limitation in sensitivity and specificity of traditional assays. While lateral flow assays are valued for their simplicity and speed, their diagnostic accuracy can sometimes fall short compared to more advanced laboratory-based methods such as PCR and ELISA. This can result in false positives or negatives, impacting clinical decision-making and eroding user confidence. Addressing this limitation requires ongoing technological advancements and investment in high-performance materials, which can increase production costs and delay market availability.
High Dependence on Raw Material Supply Chains
The production of lateral flow assay components relies heavily on the availability of raw materials such as membranes, labels, and reagents. Disruptions in global supply chains, as observed during the COVID-19 pandemic, can lead to shortages, increased costs, and delays in production. The high dependency on specialized suppliers further compounds the issue, creating vulnerabilities for manufacturers. Developing sustainable and diversified supply chains remains a critical challenge for ensuring market stability and uninterrupted production.
Regulatory and Quality Compliance Barriers
Stringent regulatory requirements for diagnostic devices pose significant challenges for manufacturers in the lateral flow assay component market. Ensuring compliance with regional and international standards requires rigorous testing, documentation, and approval processes, which can be time-consuming and costly. Non-compliance risks include production delays, market entry barriers, and potential recalls, all of which can affect brand reputation and financial performance. Smaller players, in particular, may struggle to navigate these regulatory complexities, limiting their ability to compete.
Competition from Alternative Technologies
The increasing availability of advanced diagnostic technologies, such as molecular diagnostics and next-generation sequencing, poses a competitive challenge for the lateral flow assay market. These technologies offer superior accuracy and versatility, appealing to healthcare providers seeking comprehensive diagnostic solutions. While lateral flow assays remain cost-effective and portable, their reliance on simpler methodologies makes them vulnerable to obsolescence in high-resource settings. Balancing affordability with performance enhancements is critical for maintaining competitiveness in this evolving landscape.
Market Opportunities:
The lateral flow assay component market presents significant opportunities, driven by the growing demand for rapid diagnostic solutions across diverse applications. The increasing prevalence of infectious diseases, coupled with the rising need for point-of-care testing (POCT), offers a lucrative landscape for manufacturers. Emerging markets in regions such as Asia-Pacific, Latin America, and the Middle East & Africa represent untapped potential, where improving healthcare infrastructure and rising awareness of early disease detection are accelerating the adoption of lateral flow assays. Moreover, the affordability and portability of these assays position them as ideal solutions for low-resource settings, enabling their integration into large-scale disease surveillance programs.
Innovations in multiplexing capabilities, digital readers, and connectivity features further enhance market opportunities. The expanding application of lateral flow assays in non-clinical sectors, such as food safety, environmental monitoring, and veterinary diagnostics, widens the market scope. Additionally, the push for sustainable products, including eco-friendly materials and cost-effective manufacturing processes, aligns with global trends, enhancing the market’s appeal. Manufacturers focusing on R&D to improve assay sensitivity and specificity are well-positioned to capture a larger market share. Partnerships with governments, NGOs, and private healthcare providers to deliver diagnostics in underserved regions present another avenue for growth, ensuring accessibility while addressing global health challenges. The lateral flow assay component market is poised for robust expansion, supported by a combination of technological advancements, evolving applications, and geographical diversification.
Market Segmentation Analysis:
The lateral flow assay component market is segmented based on product type, technique, application, end user, and region, catering to diverse industry needs and applications.
By product type, the market includes pads, membranes, lateral flow test strips and readers, and others, with membranes playing a critical role in assay performance by enhancing sensitivity and specificity. The adoption of lateral flow test strips and digital readers is rapidly increasing due to the demand for accurate and connected diagnostic solutions.
By technique, the market is categorized into sandwich assays, multiplex detection assays, and competitive assays. Sandwich assays dominate the segment due to their widespread use in clinical and infectious disease testing. However, multiplex detection assays are gaining traction for their ability to detect multiple analytes simultaneously, especially in advanced healthcare and research settings.
Based on application, the market spans clinical testing, food safety and environment testing, drug development and quality testing, and others. Clinical testing remains the largest application segment, driven by the increasing prevalence of chronic and infectious diseases. Food safety and environmental testing are emerging as high-growth areas due to stringent regulatory requirements and rising awareness about public health.
By end user, the market serves medical device manufacturing companies, contract manufacturing companies, and others, with medical device manufacturers holding the largest share, owing to the high demand for customized assay components.
Segmentation:
By Product Type:
- Pads
- Membranes
- Lateral Flow Test Stripes and Readers
- Others
By Technique:
- Sandwich Assays
- Multiplex Detection Assays
- Competitive Assays
By Application:
- Clinical Testing
- Food Safety and Environment Testing
- Drug Development and Quality Testing
- Others
By End User:
- Medical Device Manufacturing Companies
- Medical Device Contract Manufacturing Companies
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America holds the largest share of the lateral flow assay component market, accounting for approximately 35% of the global market in 2024. The region's dominance is attributed to advanced healthcare infrastructure, high healthcare expenditure, and robust R&D activities. The United States is the primary contributor, driven by a strong demand for point-of-care testing (POCT) and a proactive approach to disease management. Canada also plays a significant role, benefiting from government initiatives promoting early diagnosis and increasing investment in healthcare technology. The prevalence of chronic and infectious diseases in the region further bolsters the adoption of lateral flow assays.
Europe follows closely, capturing around 28% of the market share, with countries such as Germany, the United Kingdom, and France leading the charge. The region’s healthcare systems emphasize rapid diagnostics and preventive healthcare, fostering the adoption of lateral flow assays. Government policies supporting innovation in diagnostic tools and a growing focus on addressing the rising burden of chronic diseases are key drivers. The increasing prevalence of infectious diseases, such as respiratory and sexually transmitted infections, further enhances the demand for lateral flow assay components in Europe.
The Asia-Pacific region is anticipated to witness the fastest growth, holding a current market share of approximately 22%. Rapid urbanization, a growing middle-class population, and increasing healthcare awareness are driving factors. Countries like China, India, and Japan are seeing significant advancements in healthcare infrastructure and diagnostic capabilities. The region’s expanding retail healthcare sector and adoption of e-commerce platforms for diagnostic kits also contribute to market growth. Additionally, the rising prevalence of infectious diseases and government initiatives promoting early disease detection support the adoption of lateral flow assays in this region.
Latin America and the Middle East & Africa collectively account for the remaining 15% of the market share, representing emerging opportunities. In Latin America, Brazil and Mexico lead the market, supported by improving healthcare access and growing investments in diagnostics. In the Middle East & Africa, the market is driven by rising healthcare awareness and efforts to strengthen diagnostic capabilities in low-resource settings. Although these regions face challenges such as limited infrastructure and funding, initiatives by international organizations and partnerships with private players are helping bridge these gaps.
Key Player Analysis:
- Abbott
- Advanced Microdevice Pvt. Ltd
- Ahlstrom-Munksjö
- Ballya Bio
- Danaher Corporation
- DCN Diagnostics
- Merck KGaA
- Nupore Filtration
- PerkinElmer Inc.
- Sartorius Stedim Biotech
Competitive Analysis:
The lateral flow assay component market is moderately fragmented, with a mix of global leaders and regional players competing for market share. Key players such as Abbott Laboratories, Thermo Fisher Scientific Inc., Bio-Rad Laboratories, Inc., Merck KGaA, and F. Hoffmann-La Roche Ltd. dominate the landscape, leveraging robust R&D capabilities, strong product portfolios, and extensive distribution networks. These companies focus on innovation, introducing advanced materials like high-performance membranes and sensitive detection reagents to improve assay efficiency and accuracy. For example, F. Hoffmann-La Roche has launched the SARS-CoV-2 Rapid Antigen Test 2.0, enhancing their product portfolio in infectious disease diagnostics. Regional and emerging players are carving their niche by offering cost-effective solutions tailored to local market needs. Collaborations with healthcare providers, NGOs, and government bodies enable these companies to penetrate underserved regions effectively. Additionally, the rise of digital readers and connectivity features has intensified competition, with companies investing in technology integration to enhance usability and broaden application areas. The market's dynamic nature drives continuous innovation, ensuring a competitive and evolving environment.
Recent Developments:
- In October 2024, Advanced Micro Devices (AMD) announced plans to start mass production of their new MI325X chip in Q4 2024, with next-generation MI350 series chips planned for release in second half of 20252.
- In October 2024, DCN Dx will showcase their miniDxR lateral flow assay reader at MEDICA 2024 in Düsseldorf, Germany. The reader offers customizations for various diagnostic applications and provides accurate results in both visual and fluorescence modes5.
- In October 2024, Sartorius Stedim Biotech reported stabilizing business environment with increased order intake for consumables, particularly noting above-average performance in their advanced therapies portfolio10.
- In July 2024, Merck KGaA reported strong Q2 2024 performance with net sales of EUR 5.352 billion, leading to raised guidance for fiscal 20246.
- In March 2023, PerkinElmer completed the divestiture of its Applied, Food and Enterprise Services businesses to New Mountain Capital, transforming into a focused Life Sciences and Diagnostics company
Market Concentration & Characteristics:
The lateral flow assay component market exhibits a moderately fragmented structure, with a balance of global leaders and regional players. Prominent companies, including Abbott Laboratories, Thermo Fisher Scientific Inc., and F. Hoffmann-La Roche Ltd., hold a significant share due to their advanced technological capabilities, extensive distribution networks, and well-established market presence. These players dominate the high-performance and innovation-driven segments, while regional manufacturers focus on cost-effective and localized solutions. The market is characterized by rapid innovation, driven by the demand for enhanced sensitivity, specificity, and multiplexing capabilities. Emerging trends such as digital connectivity and eco-friendly materials further shape market dynamics. Additionally, the market demonstrates strong adaptability, expanding into applications beyond clinical diagnostics, including food safety and environmental monitoring. The ongoing competition fosters a dynamic landscape, encouraging continuous development and diversification to meet evolving global needs across industries.
Report Coverage:
The research report offers an in-depth analysis based on By Product Type, By Technique, By Application and By End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is expected to grow significantly, driven by the increasing adoption of point-of-care testing in clinical and non-clinical applications.
- Technological advancements in multiplexing and digital connectivity will enhance assay accuracy and expand diagnostic capabilities.
- Emerging economies in Asia-Pacific, Latin America, and Africa will drive growth as healthcare infrastructure improves.
- Rising investments in R&D will lead to innovative components with better sensitivity and specificity.
- Expansion into food safety and environmental monitoring applications will diversify market opportunities.
- Eco-friendly materials and sustainable manufacturing practices will become a priority for manufacturers.
- Collaboration between public health organizations and private players will improve accessibility in underserved regions.
- Integration with telehealth and personalized medicine platforms will boost the adoption of connected diagnostic solutions.
- Increasing demand for rapid diagnostic tools during disease outbreaks will continue to shape market dynamics.
- Regulatory advancements and streamlined approval processes will facilitate faster market entry for new products.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Point-of-Care Testing (POCT)
The need for rapid, portable, and user-friendly diagnostic solutions is driving adoption of lateral flow assay components, especially in decentralized and resource-limited settings where laboratory infrastructure is lacking.
Technological Advancements in Assay Design
Innovations in microfluidics, biosensors, and multiplexing are enhancing the sensitivity, specificity, and versatility of lateral flow assays, enabling broader clinical, environmental, and food safety applications.
Rising Prevalence of Chronic and Infectious Diseases
The global increase in chronic conditions like diabetes and cardiovascular diseases, as well as infectious disease outbreaks such as COVID-19, has heightened demand for efficient, scalable diagnostic tools like lateral flow assays.
Increased R&D Investments and Product Innovation
Growing investments from both public and private sectors are fostering the development of advanced materials and digital connectivity features, improving assay performance and expanding market reach.
Emergence of Non-Clinical Applications
The adoption of lateral flow assays in food safety, environmental monitoring, and veterinary diagnostics is diversifying market opportunities beyond traditional healthcare, driven by regulatory requirements and consumer demand for safety and transparency.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the lateral flow assay component market by 2032?
What are the primary drivers of market growth?
Which region holds the largest market share?
What challenges does the market face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Medical Device Manufacturing Companies
- 1.2.2 Medical Device Contract Manufacturing Companies
- 1.2.3 Others
- 1.3 By Technique
- 1.3.1 Sandwich Assays
- 1.3.2 Multiplex Detection Assays
- 1.3.3 Competitive Assays
- 1.4 By Application
- 1.4.1 Clinical Testing
- 1.4.2 Food Safety and Environment Testing
- 1.4.3 Drug Development and Quality Testing
- 1.4.4 Others
- 1.5 By Product Type
- 1.5.1 Pads
- 1.5.2 Membranes
- 1.5.3 Lateral Flow Test Strips and Readers
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 388.1 million → 2032: USD 556.15 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Lateral Flow Assay Component Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Lateral Flow Assay Component Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Lateral Flow Assay Component Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Lateral Flow Assay Component Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Lateral Flow Assay Component Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Lateral Flow Assay Component Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Lateral Flow Assay Component Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Lateral Flow Assay Component Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 388.1 million → 2032: USD 556.15 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Lateral Flow Assay Component Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Medical Device Manufacturing Companies
- 12.3.7.2 Medical Device Contract Manufacturing Companies
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technique - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Sandwich Assays
- 12.4.7.2 Multiplex Detection Assays
- 12.4.7.3 Competitive Assays
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Clinical Testing
- 12.5.7.2 Food Safety and Environment Testing
- 12.5.7.3 Drug Development and Quality Testing
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Pads
- 12.6.7.2 Membranes
- 12.6.7.3 Lateral Flow Test Strips and Readers
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Lateral Flow Assay Component End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Lateral Flow Assay Component Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Lateral Flow Assay Component Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Lateral Flow Assay Component Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Abbott
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ahlstrom-Munksjö
- 18.4 Merck KGaA
- 18.5 Sartorius Stedim Biotech
- 18.6 PerkinElmer Inc.
- 18.7 DCN Diagnostics
- 18.8 Advanced Microdevice Pvt. Ltd
- 18.9 Ballya Bio
- 18.10 Nupore Filtration
- 18.11 Danaher Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

