
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Latin America Contract Pharmaceutical Manufacturing Market Size 2023 | USD 10,760.17 million |
| Latin America Contract Pharmaceutical Manufacturing Market, CAGR | 7.63% |
| Latin America Contract Pharmaceutical Manufacturing Market Size 2032 | USD 20,872.05 million |
Market Overview
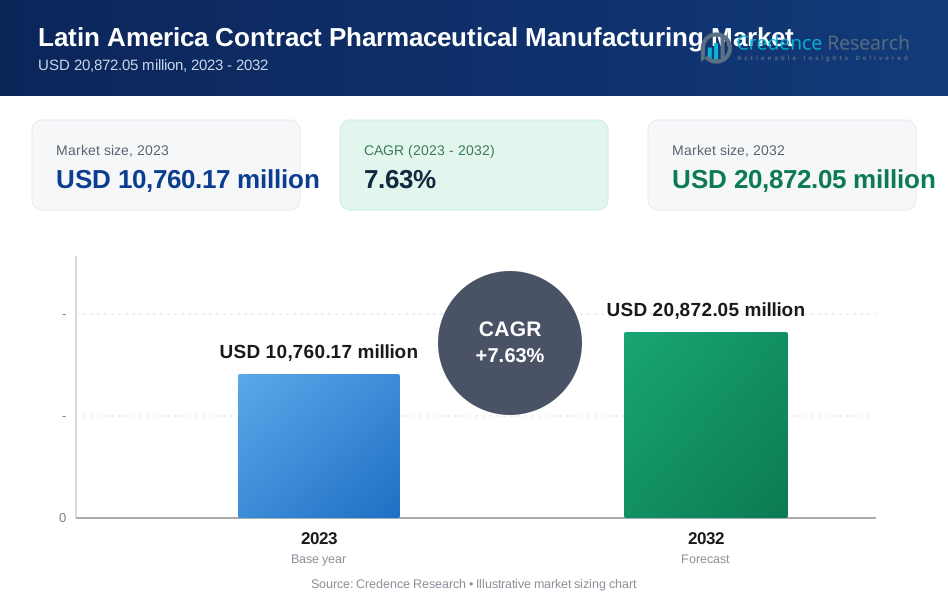
The Latin America Contract Pharmaceutical Manufacturing Market is projected to grow from USD 10,760.17 million in 2023 to USD 20,872.05 million by 2032, at a CAGR of 7.63%.
The Latin America Contract Pharmaceutical Manufacturing market is driven by the increasing outsourcing of pharmaceutical production to reduce costs and improve efficiency. Pharmaceutical companies are focusing on leveraging the expertise of contract manufacturers to enhance product quality and streamline supply chains. The growing demand for generic medicines and biosimilars, coupled with the rise in chronic diseases, has boosted production needs, further propelling market growth. Technological advancements, such as automation and process optimization in manufacturing facilities, are enabling higher production capacity and compliance with regulatory standards. Additionally, the expanding healthcare infrastructure and favorable government initiatives in the region are creating opportunities for contract manufacturers. Trends such as the adoption of sustainable manufacturing practices and the integration of digital solutions for better operational transparency are shaping the market landscape. These factors collectively contribute to the robust growth of the Latin America Contract Pharmaceutical Manufacturing market.
The Latin America contract pharmaceutical manufacturing market benefits from its strategic geographical positioning and growing alignment with international quality standards. Key countries such as Brazil, Argentina, Colombia, and Chile serve as major hubs, supported by favorable government policies and cost-effective production environments. These regions are increasingly attracting multinational pharmaceutical companies seeking efficient outsourcing solutions for APIs, final dosage forms, and specialty pharmaceuticals. Additionally, the presence of skilled professionals and advanced manufacturing infrastructure enhances the region's competitiveness. Prominent players in this market include Lonza Group, Fresenius Kabi AG, Boehringer Ingelheim International GmbH, Recipharm AB, and Catalent, Inc., among others. These companies are leveraging the region's economic advantages and growing demand for biosimilars and generics to expand their operations. The increasing adoption of digitalization, automation, and sustainable manufacturing practices further strengthens Latin America’s role as a key player in the global pharmaceutical outsourcing landscape.
Market Insights
- The Latin America Contract Pharmaceutical Manufacturing market is projected to grow from USD 10,760.17 million in 2023 to USD 20,872.05 million by 2032, at a CAGR of 7.63%.
- The increasing demand for generics and biosimilars is a major driver, fueled by the expiration of blockbuster drug patents.
- Growing outsourcing of pharmaceutical manufacturing by global companies is boosting the market.
- Rising focus on specialty pharmaceuticals, particularly biologics and oncology treatments, is influencing market trends.
- Competitive players like Lonza Group, Boehringer Ingelheim, and Pfizer are expanding their operations in the region.
- Market restraints include regulatory complexities and infrastructure limitations in some countries.
- Brazil, Argentina, and Colombia are key regions driving the market, supported by government incentives and a skilled workforce.
Market Drivers
Growing Domestic Demand
The surging domestic demand for pharmaceuticals is another critical driver of market growth in Latin America. A growing population and rising healthcare expenditure have fueled the need for diverse pharmaceutical products. For instance, Latin America is one of the fastest-growing pharmaceutical markets, with an increasing and aging population of 660 million people. Aging populations across the region require specialized medications to address age-related health conditions. Furthermore, the increasing prevalence of chronic diseases such as diabetes, hypertension, and cardiovascular disorders has escalated the demand for high-quality and affordable medications. This growing demand creates robust opportunities for CMOs to expand their operations and cater to the needs of both domestic and international markets.
Cost-Effectiveness
The Latin America Contract Pharmaceutical Manufacturing market benefits significantly from its cost-effectiveness, making it an attractive destination for pharmaceutical production. Lower labor and operational costs compared to developed regions like North America and Europe enable companies to achieve substantial savings without compromising quality. For instance, Brazil's pharmaceutical contract manufacturing market is attractive due to its low manufacturing costs and the presence of numerous GMP-certified plants. Additionally, government incentives and tax breaks further enhance the region’s appeal by reducing financial barriers for foreign investment in the pharmaceutical sector. These cost advantages not only attract international players but also contribute to the growth of local contract manufacturing organizations (CMOs), fostering a competitive market environment.
Favorable Regulatory Environment
A favorable regulatory environment in Latin America supports the expansion of contract pharmaceutical manufacturing. Streamlined regulatory processes and supportive policies enable companies to establish and operate manufacturing facilities efficiently. For instance, Mexico has implemented a comprehensive regulatory framework to govern pharmaceutical contract manufacturing and research services. Additionally, the alignment of local regulations with international standards such as GMP (Good Manufacturing Practices) and ICH (International Council for Harmonisation) guidelines ensures that pharmaceutical products meet global quality and safety benchmarks. This regulatory alignment not only facilitates exports but also strengthens the credibility of Latin American CMOs in the global market.
Increasing Outsourcing and Technological Advancements
The growing trend of outsourcing manufacturing activities is reshaping the pharmaceutical landscape in Latin America. Pharmaceutical companies are increasingly outsourcing non-core functions to focus on R&D and marketing, while CMOs provide specialized expertise and services. Technological advancements, including automation, robotics, and digitalization, are further driving efficiency and quality in manufacturing processes. Investments in R&D to develop innovative drug delivery systems and formulations, coupled with strategic partnerships and collaborations, are enabling CMOs to expand their capabilities and compete on a global scale.
Market Trends
Rising Demand for Generics and Biosimilars
Latin America is witnessing a surge in demand for generic and biosimilar medications, largely driven by the expiration of patents for blockbuster drugs. These patent expirations present significant opportunities for pharmaceutical companies to develop cost-effective alternatives. For instance, Argentina, Brazil, and Mexico have the largest number of approved similar biotherapeutic products (SBPs) in the region. Moreover, the region's competitive manufacturing environment, supported by lower production costs and skilled labor, makes Latin America an attractive hub for the production of generics and biosimilars. Countries across the region, including Brazil, Mexico, and Argentina, are becoming key players in catering to the rising global demand for affordable and high-quality medicines.
Increased Outsourcing and Regulatory Harmonization
The trend of outsourcing non-core activities, such as manufacturing, is gaining traction among pharmaceutical companies in the region. By shifting their focus to R&D, marketing, and innovation, these companies are fostering the growth of contract manufacturing organizations (CMOs). For instance, the outsourcing of manufacturing activities to specialized CMOs remains a key strategy for pharmaceutical companies to focus on core competencies and meet market demand. Simultaneously, Latin American countries are aligning their regulatory frameworks with international standards, such as ICH and GMP guidelines, to attract more global pharmaceutical companies. This harmonization not only ensures compliance with global quality benchmarks but also enhances the region's appeal as a reliable outsourcing destination.
Expanding Focus on Specialty Pharmaceuticals
The demand for specialty pharmaceuticals is growing rapidly in Latin America, especially in critical areas such as oncology, rare diseases, and biologics. These therapies require specialized manufacturing capabilities and stringent quality control measures, prompting contract manufacturers to expand their expertise and infrastructure. This focus on specialty pharmaceuticals is also supported by increased R&D activities and investments, as companies strive to address complex health challenges. The combination of regional expertise and global partnerships is enabling Latin America to position itself as a significant contributor to this high-value segment of the pharmaceutical industry.
Emphasis on Technology, Sustainability, and Government Support
Latin America's pharmaceutical industry is embracing technological advancements, including automation, robotics, and digitalization, to improve efficiency and product quality. These innovations are driving investments in R&D and fostering a culture of innovation. Additionally, there is a growing focus on sustainability, with contract manufacturers adopting eco-friendly practices to reduce their environmental impact. Government support further enhances the region's pharmaceutical landscape, offering incentives like tax breaks, subsidies, and streamlined regulatory processes to attract foreign investments and bolster local manufacturing capabilities. This combination of technology, sustainability, and government backing positions Latin America as a dynamic and evolving market in the global pharmaceutical industry.
Market Challenges Analysis
Infrastructure, Supply Chain, and Regulatory Challenges
Latin America's pharmaceutical manufacturing industry faces significant challenges related to infrastructure and supply chain limitations. Inadequate infrastructure, such as unreliable power supplies, underdeveloped transportation networks, and insufficient storage facilities, hinders efficient operations in many countries. These limitations can lead to increased production costs and delays in delivering products to market. Furthermore, supply chain disruptions, including raw material shortages and logistical obstacles, pose additional risks to manufacturing continuity. For instance, supply chain disruptions in Latin America have been exacerbated by increased shipping costs and long delays, particularly affecting exports to major markets like the US and China. These issues are further compounded by complex regulatory environments, where varying standards across countries result in higher compliance costs and extended timelines for product approvals. Ensuring the consistent enforcement of regulations remains a challenge, often complicating the navigation of regional markets and delaying the entry of new products.
Economic, Workforce, and Market Access Constraints
Economic and political instability also present formidable challenges for the region. Currency fluctuations can affect manufacturing costs, pricing strategies, and overall profitability, while political uncertainties can deter long-term investments. Talent shortages in specialized fields such as quality assurance and regulatory affairs further hinder industry growth. Many companies face difficulties finding skilled professionals to meet the technical demands of the sector, emphasizing the need for investments in training and workforce development. For example, the pharmaceutical industry in Latin America faces challenges in finding skilled professionals, highlighting the need for workforce development. Additionally, weak intellectual property (IP) protections in some countries discourage innovation and R&D investments. The counterfeit drug trade, exacerbated by inadequate IP enforcement, undermines the market and endangers public health. Market access barriers, including trade restrictions and distribution challenges, further constrain growth. Tariffs, quotas, and non-tariff measures can limit the competitiveness of Latin American-manufactured products in international markets. Establishing effective distribution networks in remote or underserved regions often requires considerable investment and logistical expertise. These interconnected challenges emphasize the need for strategic efforts to address infrastructure deficiencies, strengthen supply chains, harmonize regulatory frameworks, and improve economic and workforce conditions to unlock the full potential of Latin America's pharmaceutical manufacturing sector.
Market Opportunities
Expanding Market for Specialty Pharmaceuticals
Latin America presents significant opportunities in the contract pharmaceutical manufacturing sector, particularly in the growing field of specialty pharmaceuticals. The increasing prevalence of chronic and rare diseases, combined with advancements in biologics and oncology treatments, is driving demand for specialized drug production. Contract manufacturing organizations (CMOs) in the region are well-positioned to capitalize on this trend by expanding their capabilities to include high-value, technically demanding production processes. Furthermore, the rising adoption of biosimilars and generics, propelled by the expiration of patents for blockbuster drugs, offers an additional avenue for growth. Latin America's cost-competitive manufacturing landscape, supported by a skilled workforce and favorable economic conditions, enhances its appeal as a reliable destination for global pharmaceutical companies seeking to outsource production.
Favorable Regulatory and Economic Environment
The region's increasing alignment with international regulatory standards, such as ICH and GMP guidelines, further amplifies its attractiveness for contract manufacturing. This harmonization reduces compliance complexities for multinational companies, enabling smoother market entry. Additionally, governments across Latin America are providing various incentives, including tax benefits, subsidies, and streamlined regulatory processes, to attract foreign investment and foster local pharmaceutical production. The growing focus on sustainability and the adoption of advanced manufacturing technologies like automation and digitalization also create opportunities for CMOs to enhance operational efficiency and meet global quality standards. Together, these factors position Latin America as a dynamic and emerging hub for contract pharmaceutical manufacturing on the global stage.
Market Segmentation Analysis:
By Service Type:
The Latin America contract pharmaceutical manufacturing market is segmented into two primary service categories: Contract Manufacturing Organizations (CMOs) and Contract Research Organizations (CROs). CMOs dominate the landscape, providing critical services such as active pharmaceutical ingredient (API) manufacturing, final dosage form production, and packaging. API manufacturing remains a cornerstone of the market, driven by the growing demand for generics and biosimilars. The final dosage form manufacturing segment benefits from increasing outsourcing by global pharmaceutical companies seeking cost-effective solutions for tablets, capsules, and injectable formulations. Packaging services are gaining traction as the region embraces advanced, sustainable, and customized packaging solutions to meet international standards. CROs complement the CMO segment by offering specialized services across the drug development lifecycle. These include drug discovery, preclinical studies, and clinical trial phases ranging from early Phase I-IIa to late Phase IIIb-IV. Additional services like medical coding, clinical data management, and protocol development are vital for ensuring regulatory compliance and efficient project execution. The growing complexity of drug development and the emphasis on regulatory alignment with global standards drive the demand for CRO services in Latin America.
By Molecule Type:
The market is further segmented by molecule type into small and large molecules. Small molecules represent a substantial portion of the market due to their widespread use in generics and traditional pharmaceutical formulations. The increasing prevalence of chronic diseases and the expiration of blockbuster drug patents drive the production of cost-effective small-molecule therapies. Meanwhile, large molecules, including biologics and biosimilars, are witnessing rapid growth fueled by advancements in biotechnology and increasing demand for targeted therapies. Latin America’s focus on biosimilars and monoclonal antibodies has positioned it as a key player in large-molecule manufacturing. The region’s cost-competitive advantages, coupled with the availability of skilled professionals and infrastructure investments, further bolster its capabilities in this segment. The increasing outsourcing of both small and large-molecule manufacturing by multinational pharmaceutical companies underscores the region's growing prominence in the global pharmaceutical manufacturing sector.
Segments:
Based on Service Type:
- Contract Manufacturing Organization (CMO)
- API Manufacturing
- Final Dosage Form Manufacturing
- Packaging
- Contract Research Organization (CRO)
- Drug Discovery
- Preclinical Studies
- Early Phase I-IIa
- Phase IIa-III
- Phase IIIb-IV
- Medical Coding and Writing
- Monitoring
- Clinical Data Management
- Others (Protocol Development, etc.)
Based on Molecule Type:
- Small Molecule
- Large Molecule
Based on the Geography:
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
Regional Analysis
Brazil
Brazil holds the largest share in the Latin America contract pharmaceutical manufacturing market, accounting for over 35% of the total regional revenue. This dominant position is attributed to the country’s well-established pharmaceutical industry, extensive healthcare infrastructure, and robust domestic demand for generics and specialty medications. Brazil's government policies encourage local production and provide incentives for foreign investment, further boosting its manufacturing capabilities. Additionally, the country’s adoption of international quality standards, such as GMP and ICH guidelines, makes it a preferred outsourcing destination for multinational pharmaceutical companies. Brazil’s focus on developing biosimilars and leveraging advanced manufacturing technologies has also positioned it as a hub for innovative pharmaceutical production in the region.
Argentina
Argentina accounts for approximately 20% of the market share in Latin America, emerging as a key player in the contract pharmaceutical manufacturing sector. The country’s pharmaceutical industry benefits from a skilled workforce, a growing focus on specialty pharmaceuticals, and government support for R&D initiatives. Argentina has increasingly invested in biotechnology and biologics, catering to the rising demand for targeted therapies in oncology and rare diseases. Its strategic location and cost-competitive advantages attract multinational companies seeking efficient manufacturing solutions. Furthermore, the country’s regulatory framework aligns with international standards, facilitating seamless market entry for global players. Argentina’s expanding capabilities in API manufacturing and packaging further reinforce its position in the regional market.
Colombia
Colombia contributes around 15% of the Latin America contract pharmaceutical manufacturing market. The country’s strategic geographic location, coupled with well-developed logistics networks, makes it an attractive hub for pharmaceutical outsourcing. Colombia has made significant progress in aligning its regulatory frameworks with international standards, enhancing its appeal to multinational companies. The government’s support for the pharmaceutical sector, including tax incentives and streamlined regulatory processes, fosters growth in the contract manufacturing landscape. Colombia's focus on sustainable practices and eco-friendly manufacturing aligns with global trends, further driving investments in the sector. Additionally, the growing demand for generics and biosimilars within the domestic market complements the country’s expanding contract manufacturing capabilities.
Peru and Chile
Peru and Chile collectively represent about 10% of the market share, with each country contributing equally to the growth of the contract pharmaceutical manufacturing sector in Latin America. Peru's emphasis on improving healthcare accessibility and fostering foreign investment has led to the establishment of modern manufacturing facilities. The country’s alignment with international regulatory standards supports its growing pharmaceutical exports. Similarly, Chile benefits from a stable economic environment and government initiatives promoting pharmaceutical innovation. Both countries are investing in advanced technologies and infrastructure to enhance their manufacturing capacities, making them emerging players in the Latin America contract pharmaceutical manufacturing market. Their strategic focus on biosimilars and packaging services positions them for sustained growth in the coming years.
Key Player Analysis
- Lonza Group
- Boehringer Ingelheim International GmbH
- Fresenius Kabi AG
- Unither Pharmaceuticals
- Pfizer Inc.
- Charles River Laboratories
- Laboratory Corporation of America Holdings
- IQVIA, Inc.
- Recipharm AB
- AbbVie, Inc.
- Catalent, Inc.
- West Pharmaceutical Services, Inc.
Competitive Analysis
The Latin America Contract Pharmaceutical Manufacturing market is highly competitive, with several leading players striving to capture significant market share. Key players in the region include Lonza Group, Boehringer Ingelheim, Fresenius Kabi AG, Unither Pharmaceuticals, Pfizer Inc., Charles River Laboratories, Laboratory Corporation of America Holdings, IQVIA, Inc., Recipharm AB, AbbVie, Inc., Catalent, Inc., and West Pharmaceutical Services, Inc. These companies are investing heavily in infrastructure, advanced technologies, and regulatory compliance to enhance their manufacturing capabilities. For instance, Grünenthal invested over €80 million to modernize its Latin American production sites, ensuring a reliable supply of medicines for patients across Latin America, Europe, and beyond. Leading firms are investing heavily in automation, digitalization, and sustainable practices to enhance operational efficiency and meet global quality standards. In the market, there is an increasing focus on biologics, biosimilars, and specialty pharmaceuticals, with players offering end-to-end services from active pharmaceutical ingredient (API) manufacturing to packaging. The trend of outsourcing is also gaining momentum, as pharmaceutical companies seek to reduce costs, improve time-to-market, and focus more on R&D and marketing. The competitive landscape is marked by ongoing mergers, partnerships, and acquisitions as firms look to strengthen their regional presence and expand their service offerings. Additionally, companies are focusing on enhancing their portfolios by providing value-added services such as clinical trials, drug discovery, and preclinical research. This is positioning Latin America as a growing hub for pharmaceutical manufacturing, with firms continuously evolving to meet the market’s dynamic needs.
Recent Developments
- In July 2024, Esteve Pharmaceuticals announced an investment of USD 108 million to build a new manufacturing unit at its Girona plant for API production.
- In May 2024, AbbVie entered into a product development and option-to-license agreement with Gilgamesh Pharmaceuticals to develop next-generation therapies for psychiatric disorders.
- In May 2024, Siren Biotechnology and Catalent, Inc. entered in partnership for manufacturing of AAV Gene Therapies for cancer.
- In April 2024, KVK-Tech entered into a strategic agreement with Sen-Jam Pharmaceutical to manufacture the latter’s injectable anti-inflammatory therapeutic, SJP-100.
- In March 2024, Lonza has signed an agreement to acquire the Genentech manufacturing facility in Vacaville (US) from Roche for USD 1.2 billion in cash.
- In November 2023, Daré Bioscience, Inc., a leader in women’s health innovation, and Premier Research International, LLC, a global clinical research, product development, and consulting company, announced that the companies extended their partnership agreement under which Premier Research International, LLC will continue to provide an exclusive basis contract research organization (CRO) service within the U.S. to support the clinical development of Daré Bioscience, Inc’s reproductive health portfolio
- In November, 2023, Ichor Life Sciences, a full-service contract research organization (CRO) and longevity biotechnology company, announced the launch of Ichor Clinical Trial Services. With the founding of Ichor Clinical, the company is able to serve biotechnology and pharmaceutical clients from early preclinical studies through late-stage clinical trials and U.S. Food Drug Administration approval.
Market Concentration & Characteristics
The Latin America Contract Pharmaceutical Manufacturing market exhibits moderate concentration, with a combination of regional and global players competing for market share. While multinational companies dominate the larger segments of the market, several regional players are steadily increasing their presence, particularly in specialized services such as biosimilars and small-batch production. This blend of established global players and emerging regional firms creates a competitive environment that fosters innovation and cost-effective solutions. The market is characterized by a high level of service specialization, with companies offering a wide range of services from API manufacturing and final dosage form production to packaging and clinical trials. The market is also defined by growing outsourcing trends, as pharmaceutical companies increasingly look to reduce costs, enhance efficiency, and streamline operations. Outsourcing provides access to state-of-the-art facilities and expertise, particularly for biologics and generics production. Additionally, regulatory compliance and adherence to international standards such as GMP and ICH are crucial for maintaining competitiveness in this market. Companies are investing in advanced manufacturing technologies, including automation, robotics, and digitalization, to meet the rising demand for quality products in a cost-effective manner. The combination of specialized services, technological advancements, and outsourcing trends ensures that the Latin American contract pharmaceutical manufacturing market remains dynamic and attractive to both domestic and international companies.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Molecule Type, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Latin America Contract Pharmaceutical Manufacturing market is expected to continue growing at a robust pace, driven by increasing demand for generics and biosimilars.
- Technological advancements in automation, robotics, and digitalization will further enhance manufacturing efficiency and product quality.
- The region's cost-effective production capabilities will remain a key attraction for pharmaceutical companies seeking to reduce manufacturing costs.
- Outsourcing of pharmaceutical manufacturing will rise, as global companies focus on R&D and marketing while outsourcing non-core activities.
- Demand for specialty pharmaceuticals, particularly biologics, oncology treatments, and rare disease drugs, will drive further investments in advanced manufacturing capabilities.
- The regulatory environment will continue to align with international standards, fostering trust and attracting global players to the region.
- The expansion of production capacity in Brazil, Argentina, and Colombia will continue to lead the growth of contract manufacturing in Latin America.
- Latin American countries will increasingly focus on sustainability and eco-friendly practices to meet global environmental standards.
- The market will see a rise in partnerships and collaborations between local and international companies to leverage regional expertise.
- As healthcare access improves across Latin America, there will be growing demand for both generic and branded pharmaceutical products, further stimulating market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Outsourcing to Reduce Costs
Pharmaceutical companies are increasingly outsourcing manufacturing to Latin America to leverage lower labor and operational costs, enabling them to focus on R&D and marketing while improving efficiency and reducing overall production expenses.
Rising Demand for Generics and Biosimilars
Patent expirations for blockbuster drugs and the growing prevalence of chronic diseases are driving demand for affordable generics and biosimilars, boosting the need for contract manufacturing services in the region.
Favorable Regulatory Alignment and Government Incentives
Latin American countries are aligning their regulatory frameworks with international standards such as GMP and ICH, and offering tax breaks and incentives, making the region more attractive for multinational pharmaceutical companies seeking reliable outsourcing partners.
Technological Advancements and Digitalization
Investments in automation, robotics, and digital solutions are enhancing manufacturing capacity, quality, and compliance, enabling contract manufacturers in Latin America to meet global standards and attract more business.
Expansion of Healthcare Infrastructure
The ongoing development of healthcare infrastructure and increased healthcare expenditure across Latin America are creating greater demand for pharmaceutical products, thereby driving growth in contract manufacturing services.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Latin America Contract Pharmaceutical Manufacturing market?
What factors are driving the growth of the Latin America Contract Pharmaceutical Manufacturing market?
What are the key segments within the Latin America Contract Pharmaceutical Manufacturing market?
What are some challenges faced by the Latin America Contract Pharmaceutical Manufacturing market?
Who are the major players in the Latin America Contract Pharmaceutical Manufacturing market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Type
- 1.2.1 Contract Manufacturing Organization (CMO)
- 1.2.2 API Manufacturing
- 1.2.3 Final Dosage Form Manufacturing
- 1.2.4 Packaging
- 1.2.5 Contract Research Organization (CRO)
- 1.2.6 Drug Discovery
- 1.2.7 Preclinical Studies
- 1.2.8 Clinical Trial Phases (I-IV)
- 1.2.9 Medical Coding and Writing
- 1.2.10 Monitoring
- 1.2.11 Clinical Data Management
- 1.2.12 Others (Protocol Development, etc.)
- 1.3 By Molecule Type
- 1.3.1 Small Molecule
- 1.3.2 Large Molecule (Biologics, Biosimilars)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 10,760.17 million → 2032: USD 20,872.05 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Latin America Contract Pharmaceutical Manufacturing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Latin America Contract Pharmaceutical Manufacturing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Latin America Contract Pharmaceutical Manufacturing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Latin America Contract Pharmaceutical Manufacturing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Latin America Contract Pharmaceutical Manufacturing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Latin America Contract Pharmaceutical Manufacturing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Latin America Contract Pharmaceutical Manufacturing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Latin America Contract Pharmaceutical Manufacturing Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 10,760.17 million → 2032: USD 20,872.05 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Latin America Contract Pharmaceutical Manufacturing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Contract Manufacturing Organization (CMO)
- 12.3.7.2 API Manufacturing
- 12.3.7.3 Final Dosage Form Manufacturing
- 12.3.7.4 Packaging
- 12.3.7.5 Contract Research Organization (CRO)
- 12.3.7.6 Drug Discovery
- 12.3.7.7 Preclinical Studies
- 12.3.7.8 Clinical Trial Phases (I-IV)
- 12.3.7.9 Medical Coding and Writing
- 12.3.7.10 Monitoring
- 12.3.7.11 Clinical Data Management
- 12.3.7.12 Others (Protocol Development, etc.)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Molecule Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Small Molecule
- 12.4.7.2 Large Molecule (Biologics, Biosimilars)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Latin America Contract Pharmaceutical Manufacturing Geographic Market Outlook, 2023-2032
- 13.1 Regional Market Size and Country-Level Shares, 2023
- 13.2 Country Market Size Comparison, 2023
- 13.3 Country Market Forecasts, 2023-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Latin America Contract Pharmaceutical Manufacturing Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Latin America Contract Pharmaceutical Manufacturing Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Lonza Group
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Boehringer Ingelheim International GmbH
- 17.4 Fresenius Kabi AG
- 17.5 Recipharm AB
- 17.6 Catalent, Inc.
- 17.7 Pfizer Inc.
- 17.8 AbbVie, Inc.
- 17.9 Charles River Laboratories
- 17.10 IQVIA, Inc.
- 17.11 West Pharmaceutical Services, Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

