
Liposuction Market Overview:
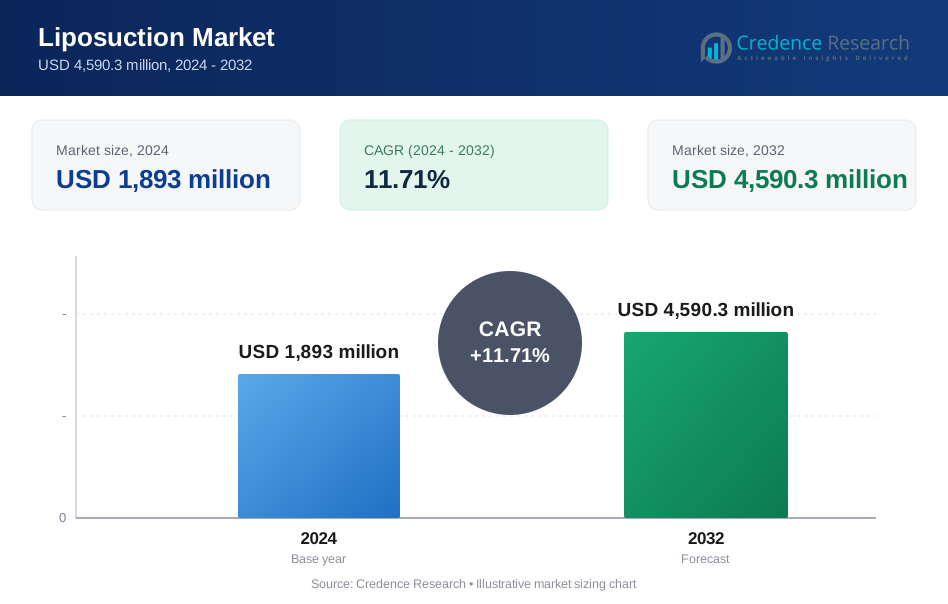
Liposuction market size was valued at USD 1,893 million in 2024 and is anticipated to reach USD 4,590.3 million by 2032, growing at a CAGR of 11.71% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Liposuction Market Size 2024 | USD 1,893 million |
| Liposuction Market, CAGR | 11.71% |
| Liposuction Market Size 2032 | USD 4,590.3 million |
Liposuction Market Insights
- Growth is supported by rising preference for minimally invasive procedures, increasing obesity prevalence, and higher body image awareness, with tumescent liposuction dominating the product mix at a 41.6% share in 2024 due to safety and wide clinical acceptance.
- Technology-led trends include increased adoption of power-assisted and energy-assisted systems, with power-assisted liposuction holding a 24.8% share, while ultrasound-assisted and laser-assisted techniques together accounted for 33.6% in 2024.
- Market structure is shaped by established device manufacturers focusing on innovation, surgeon training, and clinic partnerships to expand procedural volumes across cosmetic surgery clinics, which led end users with a 47.3% share in 2024.
- Regionally, North America led with a 38.2% share in 2024, followed by Europe at 27.4% and Asia Pacific at 23.1%, while Latin America and Middle East & Africa together accounted for 11.3%, supported by medical tourism and expanding private clinics.

Liposuction Market Segmentation Analysis:
By Product Type:
In the Liposuction market, tumescent liposuction emerged as the dominant product type, accounting for 41.6% market share in 2024, driven by its high safety profile, reduced blood loss, and wide clinical acceptance across both basic and advanced procedures. Surgeons favor this technique due to lower anesthesia requirements and consistent outcomes in large-volume fat removal. Power-assisted liposuction followed with 24.8% share, supported by efficiency in fibrous areas, while ultrasound-assisted and laser-assisted liposuction together represented 33.6%, benefiting from growing demand for precision contouring and skin-tightening capabilities in aesthetic procedures.
- For instance, in 261 VASER (third-generation ultrasound-assisted) cases by B.N.N. Tran, the overall complication rate was 4.6% (including 1.9% contour irregularities), with significant skin retraction observed even early in recovery despite large treatment volumes
By Application:
By application, the abdomen segment dominated the Liposuction market with a 38.9% share in 2024, supported by high prevalence of central obesity and strong demand for body contouring procedures among both male and female patients. The abdomen remains the primary focus area due to visible aesthetic impact and suitability for multiple liposuction techniques. Thighs accounted for 19.7%, followed by arms at 14.6%, driven by post-weight-loss treatments. Back and face & neck segments jointly held 26.8%, supported by rising demand for localized fat reduction and minimally invasive cosmetic enhancements.
- For instance, SculpSure by Cynosure received FDA clearance for non-invasive abdominal lipolysis, targeting stubborn fat deposits effectively in real-world applications.
By End User:
Among end users, cosmetic surgery clinics led the Liposuction market with a 47.3% share in 2024, driven by high procedural volumes, specialized expertise, and patient preference for outpatient aesthetic centers. These clinics benefit from faster turnaround times and adoption of advanced liposuction technologies. Hospitals accounted for 32.1%, supported by complex and combination procedures requiring multidisciplinary care. Ambulatory surgical centers held 20.6%, gaining traction due to cost efficiency, shorter recovery times, and increasing regulatory approvals for minimally invasive cosmetic surgeries in outpatient settings.
Key Growth Drivers
Rising Demand for Minimally Invasive Aesthetic Procedures
The Liposuction market is experiencing strong growth due to increasing preference for minimally invasive cosmetic procedures that offer reduced recovery time, lower complication risks, and improved aesthetic outcomes. Patients increasingly favor liposuction techniques that minimize scarring and anesthesia exposure while delivering precise body contouring. Advancements in device-assisted technologies have improved procedural safety and consistency, encouraging broader adoption across age groups. Growing social acceptance of aesthetic enhancement, combined with rising disposable income in emerging economies, continues to expand the addressable patient pool and reinforces sustained demand for liposuction procedures globally.
- For instance, InMode's BodyTite uses radiofrequency-assisted liposuction (RFAL) to enable simultaneous fat reduction and skin contraction with minimal invasiveness.
Increasing Prevalence of Obesity and Body Image Awareness
The rising prevalence of obesity and lifestyle-related weight gain has significantly accelerated demand in the Liposuction market. Sedentary lifestyles, dietary changes, and urbanization have contributed to stubborn fat accumulation that is resistant to exercise and diet. At the same time, heightened awareness of body image, fueled by social media and digital wellness platforms, has increased interest in body contouring solutions. Liposuction is increasingly viewed as a complementary procedure following weight loss, driving consistent procedure volumes across developed and developing regions.
- For instance, Cynosure's Smartlipo Triplex, FDA-approved in 2006, uses laser-assisted lipolysis to melt fat cells via a thin fiber inserted through small incisions, enabling gentler suction and skin tightening through coagulation.
Technological Advancements in Liposuction Devices
Continuous innovation in liposuction technologies is a major growth driver, as manufacturers introduce energy-based and power-assisted systems that improve fat removal efficiency and skin tightening. These advancements enhance procedural precision, reduce surgeon fatigue, and improve patient outcomes. Improved safety features and customizable treatment options have expanded the use of liposuction across multiple body areas. As clinics and hospitals invest in advanced equipment to differentiate services, technology upgrades are directly supporting higher adoption rates and procedural expansion in the Liposuction market.
Key Trends & Opportunities
Expansion of Outpatient and Office-Based Procedures
A key trend shaping the Liposuction market is the shift toward outpatient and office-based procedures, driven by patient demand for convenience and cost-effective treatment settings. Cosmetic surgery clinics and ambulatory centers are increasingly equipped with advanced liposuction systems, enabling same-day procedures and faster discharge. This trend creates opportunities for service providers to increase throughput and improve margins. Manufacturers are also benefiting by designing compact, user-friendly devices tailored for outpatient environments, supporting wider adoption beyond traditional hospital settings.
- For instance, InMode's BodyTite uses radiofrequency-assisted lipolysis for office-based fat reduction and skin tightening, with RF energy achieving up to 35% soft tissue contraction at 12 months. The system supports same-day procedures via small cannulas, minimizing downtime in ambulatory clinics.
Growing Demand in Emerging Markets
Emerging economies present significant growth opportunities for the Liposuction market due to rising medical tourism, expanding middle-class populations, and improving access to aesthetic healthcare. Countries in Asia-Pacific, Latin America, and the Middle East are witnessing increased demand for cosmetic procedures at competitive costs. Local clinics are rapidly adopting advanced liposuction technologies to attract international and domestic patients. This trend is encouraging global players to expand regional footprints through partnerships, training programs, and localized product offerings.
- For instance, MyMediTour expanded its medical tourism network in December 2025 by adding 15 partners in Mexico and Colombia, enhancing access to liposuction among other cosmetic surgeries like tummy tucks.
Key Challenges
High Procedure Costs and Limited Reimbursement
One of the primary challenges in the Liposuction market is the high cost of procedures, which limits accessibility for a large portion of the population. Advanced device-assisted liposuction systems increase capital investment for providers, while patients typically bear out-of-pocket expenses due to limited insurance coverage. This cost barrier restricts adoption in price-sensitive markets and may slow penetration in lower-income regions. Providers must balance pricing strategies with technology investments to maintain patient volumes and profitability.
Regulatory Scrutiny and Safety Concerns
Regulatory oversight and safety concerns continue to challenge the Liposuction market, particularly regarding practitioner qualifications and procedural standards. Adverse outcomes from improperly performed procedures can impact patient trust and attract stricter regulations. Variability in regulatory frameworks across regions complicates market entry for manufacturers and service providers. Ensuring consistent training, adherence to safety protocols, and post-procedure care remains critical to mitigating risks and sustaining long-term market growth.
Regional Analysis
North America
North America led the Liposuction market with a 38.2% market share in 2024, supported by high procedure volumes, strong awareness of aesthetic treatments, and early adoption of advanced liposuction technologies. The region benefits from a large base of board-certified plastic surgeons and well-established cosmetic surgery clinics. Demand remains strong across abdomen and thigh procedures, driven by obesity prevalence and lifestyle-related fat accumulation. Favorable financing options, high disposable income, and continuous product innovation further support sustained growth across the United States and Canada.
Europe
Europe accounted for a 27.4% market share in 2024, driven by increasing acceptance of cosmetic procedures and strong demand from countries such as Germany, France, Italy, and the United Kingdom. The region benefits from advanced healthcare infrastructure and a growing emphasis on body aesthetics among aging and younger populations. Adoption of minimally invasive liposuction techniques is rising, particularly in outpatient settings. Medical tourism within Europe and growing surgeon expertise continue to strengthen procedure volumes, supporting steady expansion of the Liposuction market across the region.
Asia Pacific
Asia Pacific held a 23.1% market share in 2024, reflecting rapid growth fueled by expanding medical tourism, rising disposable incomes, and increasing social acceptance of aesthetic enhancements. Countries such as South Korea, China, Japan, and India are major contributors due to high procedural demand and competitive treatment costs. The region is witnessing strong adoption of advanced liposuction devices in cosmetic clinics. Growing urbanization, body image awareness, and improving access to aesthetic healthcare are accelerating market penetration across both developed and emerging economies.
Latin America
Latin America captured a 6.7% market share in 2024, supported by strong demand for cosmetic procedures in countries such as Brazil, Mexico, and Colombia. The region benefits from a high concentration of skilled aesthetic surgeons and a strong cultural emphasis on body contouring. Cost-effective procedures and growing medical tourism are key growth drivers. Increasing investments in private cosmetic clinics and rising adoption of modern liposuction technologies continue to improve service quality, supporting gradual expansion of the Liposuction market across the region.
Middle East & Africa
The Middle East & Africa region accounted for a 4.6% market share in 2024, driven by rising demand for aesthetic procedures in countries such as the UAE, Saudi Arabia, and South Africa. Growth is supported by expanding private healthcare infrastructure and increasing interest in body contouring among high-income populations. Medical tourism and luxury cosmetic clinics play a key role in regional demand. However, uneven access to trained professionals limits broader penetration, resulting in moderate but steady growth of the Liposuction market.
Liposuction Market Segmentations:
By Product Type
- Laser-assisted liposuction
- Ultrasound-assisted liposuction
- Power-assisted liposuction
- Tumescent liposuction
By Application
- Abdomen
- Thighs
- Arms
- Back
- Face & neck
By End User
- Hospitals
- Cosmetic surgery clinics
- Ambulatory surgical centers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Liposuction market highlights the presence of established device manufacturers such as InMode Ltd., Solta Medical, Alma Lasers, Cynosure Inc., Sciton Inc., Apyx Medical Corporation, Wells Johnson Co., and YOLO Medical Inc.. The market is moderately consolidated, with competition driven by technological innovation, product differentiation, and strong surgeon relationships. Leading players focus on developing energy-assisted and power-assisted systems that enhance procedural efficiency and patient outcomes. Strategic initiatives include product upgrades, geographic expansion, physician training programs, and partnerships with cosmetic clinics. Companies also compete on ease of use, safety features, and post-procedure results, while regulatory compliance and clinical validation remain critical for sustaining market position and long-term growth.
Key Player Analysis
- Solta Medical
- InMode Ltd.
- Alma Lasers
- Sciton Inc.
- Cynosure Inc.
- Zeltiq Aesthetics
- Genesis Biosystems, Inc.
- Wells Johnson Co.
- YOLO Medical Inc.
- Apyx Medical Corporation
Recent Developments
- In January 2025, MicroAire Surgical Instruments acquired Neosyad, a French liposuction technology company, to integrate its AdiMate all-in-one system for infiltration, liposuction, and adipose tissue engineering into MicroAire's portfolio.
- In September 2025, Apyx Medical Corporation launched the nationwide commercial rollout of its AYON Body Contouring System, featuring ultrasound-assisted liposuction and Renuvion technology for integrated fat removal and skin tightening.
- In July 2025, 365mc and Raziel Therapeutics announced a strategic collaboration to accelerate development of RZL-012, a non-invasive fat reduction therapy, combined with 365mc's LAMS liposuction-assisted modeling system in South Korea.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Liposuction market will continue to expand due to sustained demand for minimally invasive body contouring procedures.
- Technological advancements will improve procedural precision, safety, and skin-tightening outcomes.
- Energy-assisted and power-assisted liposuction systems will gain wider adoption across cosmetic clinics.
- Outpatient and office-based procedures will increase as patients seek convenience and faster recovery.
- Growing obesity rates will support long-term demand for fat reduction solutions.
- Rising body image awareness will drive higher procedure volumes across diverse age groups.
- Emerging markets will witness faster adoption supported by medical tourism and improving healthcare access.
- Physician training and certification programs will enhance procedural standardization and safety.
- Product innovation will focus on reducing downtime and improving patient comfort.
- Strategic partnerships and geographic expansion will strengthen competitive positioning of key players.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Liposuction market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Liposuction market projected to grow between 2024 and 2032?
Which Liposuction market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Liposuction market?
Who are the leading companies in the Liposuction market?
Which region commanded the largest share of the Liposuction market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Liposuction Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Liposuction Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,893 million → 2032: USD 4,590.3 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Liposuction Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Liposuction Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Liposuction Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Liposuction Market Drivers
- 3.3 Liposuction Market Restraints & Challenges
- 3.4 Liposuction Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Liposuction Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Liposuction Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Liposuction category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Liposuction Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Liposuction Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Liposuction market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Liposuction Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Liposuction Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Liposuction Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Liposuction (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Liposuction Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Liposuction Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Liposuction Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Liposuction Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Liposuction Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Liposuction Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Liposuction Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Liposuction Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Liposuction Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
