
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Liquid Chromatography Systems Market Size 2024 | USD 10315 Million |
| Liquid Chromatography Systems Market, CAGR | 6.1% |
| Liquid Chromatography Systems Market Size 2032 | USD 16565.03 Million |
Market Overview:
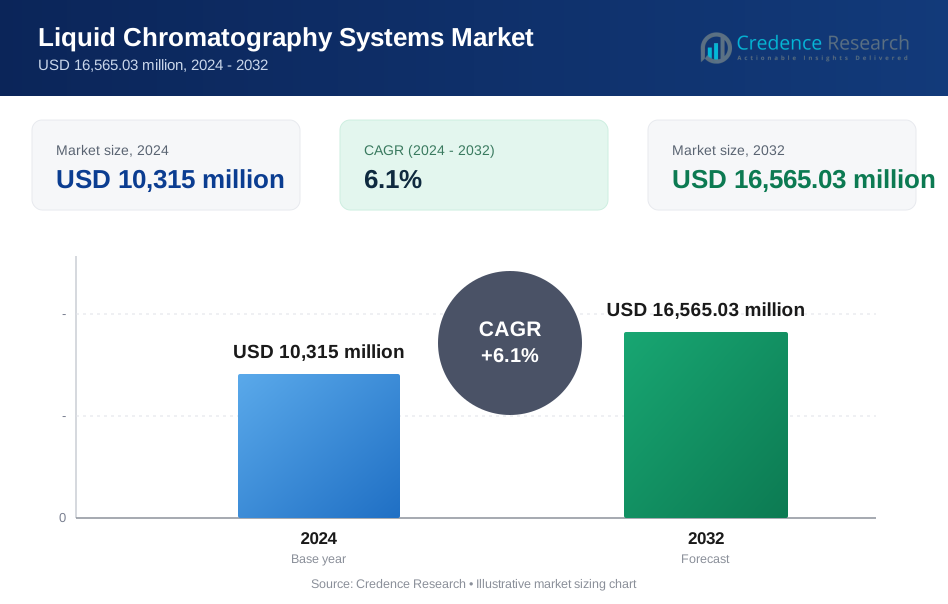
The Liquid Chromatography Systems Market is projected to grow from USD 10315 million in 2024 to an estimated USD 16565.03 million by 2032, with a compound annual growth rate (CAGR) of 6.1% from 2024 to 2032.
Key drivers for this growth include the expanding pharmaceutical and biotechnology industries, which rely heavily on liquid chromatography systems for drug development, quality control, and compliance with stringent regulatory standards. The growing focus on environmental testing to monitor water quality and detect contaminants further fuels demand for these systems. Additionally, increasing investments in research and development across academic and industrial sectors are enhancing the adoption of advanced chromatography technologies. The rise in chronic diseases globally has also spurred the demand for personalized medicine, where liquid chromatography systems play a pivotal role in biomarker discovery and therapeutic monitoring.
Regionally, North America dominates the market, accounting for the largest share due to its robust pharmaceutical industry, extensive research infrastructure, and significant government funding for scientific research. The United States is a key contributor, with widespread adoption of liquid chromatography systems in drug discovery and regulatory testing. Europe follows closely, driven by stringent environmental regulations and a strong emphasis on food safety. The Asia-Pacific region is anticipated to witness the fastest growth, fueled by rising healthcare investments, expanding pharmaceutical production, and growing awareness of advanced analytical techniques in countries like China, India, and Japan. Emerging markets in Latin America and the Middle East & Africa are also showing promising potential, supported by increasing investments in research capabilities and industrialization.
Market Insights:
- The market is projected to grow from USD 10,315 million in 2024 to USD 16,565.03 million by 2032, with a CAGR of 6.1%, driven by expanding applications in pharmaceuticals and biotechnology.
- Increasing adoption in environmental testing for pollutant detection and compliance with stricter regulations supports market growth.
- The food and beverage industry leverages liquid chromatography systems to ensure safety, detect contaminants, and authenticate product origins.
- Technological advancements, such as UHPLC and automated systems, are enhancing analysis speed, sensitivity, and operational efficiency.
- North America dominates the market with strong pharmaceutical demand, while Asia-Pacific shows the fastest growth due to expanding healthcare and industrial sectors.
- High initial costs and operational complexity remain challenges, particularly for SMEs and emerging markets.
- The market is evolving with green chromatography practices, focusing on eco-friendly methods and reduced solvent use, aligning with global sustainability trends.
Market Drivers:
Expanding Pharmaceutical and Biotechnology Industries
The rapid growth of the pharmaceutical and biotechnology sectors is a primary driver for the liquid chromatography systems market. These industries rely heavily on liquid chromatography systems for drug discovery, development, and quality assurance. For instance, Agilent Technologies' InfinityLab LC/MSD iQ system offers enhanced sensitivity and precision, enabling pharmaceutical companies to identify and quantify trace-level compounds in complex mixtures. With the increasing prevalence of chronic diseases and the rising demand for personalized medicine, pharmaceutical companies are leveraging advanced analytical tools to identify and develop targeted therapies. Liquid chromatography systems play a critical role in analyzing complex mixtures, identifying biomarkers, and ensuring compliance with stringent regulatory standards, thereby fueling their widespread adoption across the pharmaceutical value chain.
Rising Demand for Environmental Testing
The growing emphasis on environmental conservation and public health has significantly boosted the demand for liquid chromatography systems in environmental testing. Governments and regulatory bodies worldwide are implementing stricter guidelines to monitor water quality, detect pollutants, and control air and soil contamination. For example, Thermo Fisher Scientific's Vanquish UHPLC system provides high-resolution separation and detection capabilities, essential for identifying trace-level contaminants in environmental samples. Liquid chromatography systems offer unparalleled precision and reliability in identifying trace-level contaminants, making them indispensable in environmental analysis. As concerns over industrial pollution and climate change escalate, the adoption of advanced analytical techniques is expected to increase, further driving the market for liquid chromatography systems.
Increasing Applications in Food and Beverage Safety
The food and beverage industry is increasingly adopting liquid chromatography systems to ensure product safety and quality. Rising consumer awareness and stringent regulatory requirements have intensified the need for advanced testing solutions to detect contaminants, pesticides, and other harmful substances in food products. For instance, Waters Corporation's ACQUITY UPLC H-Class PLUS system is used to analyze pesticide residues in food, providing high sensitivity and accuracy. Liquid chromatography systems are also used to analyze nutritional content and authenticate food origin, addressing growing concerns over food fraud and labeling inaccuracies. This expanding application base is a significant factor propelling market growth, as companies prioritize consumer safety and regulatory compliance.
Technological Advancements in Analytical Instruments
Advancements in liquid chromatography technology are revolutionizing analytical workflows, contributing to the market’s growth. Innovations such as high-performance liquid chromatography (HPLC), ultra-high-performance liquid chromatography (UHPLC), and automated systems have enhanced the speed, sensitivity, and accuracy of chemical analysis. For example, Shimadzu's Nexera X2 UHPLC system offers ultra-fast analysis with a pressure tolerance of up to 130 MPa, significantly improving throughput and efficiency. These developments are enabling researchers and industries to achieve higher productivity and efficiency in their processes. Additionally, the integration of chromatography systems with advanced software and data analytics tools has streamlined operations, reducing human error and optimizing results. These technological advancements are expanding the scope of liquid chromatography applications, attracting investments from academic, industrial, and governmental organizations.
Market Trends:
Growing Adoption of Automation in Liquid Chromatography
One of the notable trends in the liquid chromatography systems market is the increasing adoption of automation in analytical processes. Automated liquid chromatography systems are becoming a preferred choice across industries as they enhance throughput, minimize human error, and improve data accuracy. For instance, Agilent Technologies has enhanced its automated liquid chromatography systems, such as the Agilent 1290 Infinity II, which offers a throughput increase of up to 40% compared to previous models. Laboratories and manufacturing facilities are leveraging these systems to streamline workflows and achieve consistent results, particularly in high-throughput environments such as pharmaceutical quality control and environmental testing. The integration of robotic arms and advanced software solutions allows for seamless sample handling, method development, and data analysis, driving the popularity of automated systems.
Rising Popularity of Miniaturized and Portable Systems
The demand for miniaturized and portable liquid chromatography systems is on the rise, driven by the need for on-site and field-based analysis. These compact systems are particularly valuable in environmental testing, food safety inspections, and forensic applications where rapid, real-time analysis is critical. Technological advancements in microfluidics and nano-scale chromatography have enabled the development of lightweight yet highly efficient systems that deliver precise results. For instance, Recent advancements from Nano Separations Technologies have led to a new high-performance liquid chromatography (HPLC) system that operates at capillary flow rates of 2–7 µL/min. As industries seek to reduce laboratory dependency and improve operational flexibility, the adoption of portable chromatography systems is expected to grow significantly.
Integration of Artificial Intelligence and Data Analytics
The integration of artificial intelligence (AI) and data analytics in liquid chromatography systems is reshaping the market landscape. AI-driven software is enhancing the efficiency of chromatographic workflows by automating data interpretation, optimizing method development, and identifying anomalies in real-time. For instance, a study highlighted the use of machine learning algorithms that can analyze historical chromatographic data to optimize separation parameters with over 85% accuracy. These intelligent systems also facilitate predictive maintenance, reducing downtime and operational costs. Moreover, the use of big data analytics allows organizations to derive actionable insights from complex datasets, enabling better decision-making in research, manufacturing, and quality assurance processes. This trend is particularly evident in pharmaceutical and biotechnology sectors, where precision and speed are critical.
Increasing Focus on Green Chromatography
Sustainability has become a focal point in the liquid chromatography systems market, leading to the emergence of green chromatography practices. Industries and research institutions are adopting eco-friendly methodologies to reduce solvent consumption, waste generation, and energy usage in analytical processes. Techniques such as supercritical fluid chromatography (SFC) and the use of water-based solvents are gaining traction as sustainable alternatives to traditional methods. For instance, Waters Corporation is leading the shift towards green chromatography by promoting supercritical fluid chromatography (SFC), which reduces solvent consumption by up to 50% compared to traditional methods. Manufacturers are also developing energy-efficient systems that align with environmental regulations and corporate sustainability goals. This shift toward green chromatography reflects the industry’s commitment to minimizing its environmental impact while maintaining analytical excellence.
Market Challenges Analysis:
High Initial Costs and Maintenance Expenses
One of the key restraints in the liquid chromatography systems market is the high initial cost associated with acquiring advanced equipment. State-of-the-art systems, such as high-performance liquid chromatography (HPLC) and ultra-high-performance liquid chromatography (UHPLC), involve significant capital investment, which can be a challenge for small and medium-sized enterprises (SMEs) and research institutions with limited budgets. Additionally, these systems require regular maintenance and calibration to ensure optimal performance, adding to operational costs. The expense of consumables, such as columns and solvents, further exacerbates the financial burden on end-users, limiting the market’s penetration in cost-sensitive regions.
Complexity of Operation and Need for Skilled Personnel
The technical complexity of liquid chromatography systems presents a challenge for their widespread adoption. Operating these systems requires specialized training and expertise, as precise handling and interpretation of results are critical for accurate analysis. The shortage of skilled professionals, particularly in developing regions, creates a barrier to effective utilization of these systems. Companies and research organizations must invest in training programs and skilled workforce development, which can increase operational costs and delay adoption.
Regulatory and Compliance Challenges
The liquid chromatography systems market is heavily influenced by stringent regulatory requirements, particularly in industries such as pharmaceuticals and food safety. Adhering to these regulations demands significant investment in validation processes, documentation, and compliance audits. Non-compliance can result in penalties, product recalls, or loss of market access, making it a critical challenge for manufacturers and end-users alike. Furthermore, frequent updates to regulatory frameworks can create additional complexities, requiring constant adaptation and innovation.
Limited Access in Emerging Markets
Despite growing awareness, the adoption of liquid chromatography systems in emerging markets remains limited due to financial constraints, lack of infrastructure, and insufficient awareness of advanced analytical techniques. Many industries in these regions continue to rely on traditional methods that are more affordable but less efficient. Bridging this gap requires targeted efforts to educate end-users about the long-term benefits of liquid chromatography systems, alongside strategies to make these technologies more accessible and affordable.
Market Opportunities:
The liquid chromatography systems market presents substantial growth opportunities driven by advancements in pharmaceutical research, environmental testing, and food safety regulations. The pharmaceutical and biotechnology sectors, in particular, offer immense potential as drug discovery and development efforts intensify. With the rising prevalence of chronic diseases and the growing emphasis on personalized medicine, there is an increasing need for precise analytical tools to identify biomarkers, develop targeted therapies, and ensure regulatory compliance. Liquid chromatography systems, with their ability to deliver high-precision analysis, are poised to play a crucial role in these efforts. The growing adoption of biologics and biosimilars further expands the market as these therapies demand advanced analytical techniques for quality assurance.
Emerging markets in Asia-Pacific, Latin America, and the Middle East & Africa provide untapped opportunities for market growth. Rapid industrialization, urbanization, and rising healthcare investments in these regions are driving the adoption of liquid chromatography systems across diverse industries. The expansion of pharmaceutical manufacturing, coupled with increasing awareness of environmental monitoring and food safety, underscores the demand for advanced analytical systems. Additionally, the development of cost-effective and portable chromatography solutions tailored to these regions' needs presents a pathway for greater market penetration. As global industries prioritize innovation, regulatory compliance, and sustainability, the liquid chromatography systems market is set to capitalize on these trends, fostering long-term growth and diversification.
Market Segmentation Analysis:
The liquid chromatography systems market is categorized by technique, type, application, end-user, and region, reflecting its wide-ranging applications and technological advancements.
By technique, the market includes High-Performance Liquid Chromatography (HPLC), Ultra-High Pressure Liquid Chromatography (UHPLC), Low-Pressure Liquid Chromatography (LPLC), and Fast Protein Liquid Chromatography (FPLC). HPLC dominates due to its precision and versatility in pharmaceutical, environmental, and food analysis. UHPLC, with its enhanced speed and sensitivity, is gaining traction in research and high-throughput testing applications.
By type, the market is segmented into consumables, instruments, and services. Consumables, such as columns and solvents, account for a significant share due to their recurring demand. Instruments drive substantial investments owing to technological advancements, while services grow as organizations outsource maintenance and analytical tasks.
By application, the market spans clinical diagnostics, environmental testing, food and beverage analysis, forensic tests, and life sciences. The life sciences sector leads, supported by drug discovery and biomarker analysis. Environmental testing and food safety are also growing rapidly due to stringent regulations and consumer awareness.
By end-user, the market serves academics and research institutes, pharmaceutical companies, hospitals, agriculture industry, and others. Pharmaceutical companies hold the largest share, driven by drug development needs, while research institutes significantly contribute through innovations in analytical methods.
Segmentation:
By Technique:
- High Performance Liquid Chromatography (HPLC)
- Ultra High Pressure Liquid Chromatography (UHPLC)
- Low Pressure Liquid Chromatography (LPLC)
- Fast Protein Liquid Chromatography (FPLC)
By Type:
- Consumables
- Instruments
- Services
By Application:
- Clinical Diagnostics
- Environmental Testing
- Food And Beverage Analysis
- Forensic Tests
- Life Sciences
By End-User:
- Academics And Research Institutes
- Pharmaceutical Companies
- Hospitals
- Agriculture Industry
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The liquid chromatography systems market demonstrates significant regional variations, with North America leading the global market. North America accounts for approximately 35% of the market share, driven by robust pharmaceutical and biotechnology sectors, advanced research infrastructure, and strong government funding for scientific research. The United States plays a pivotal role, with widespread adoption of chromatography systems in drug discovery, quality control, and regulatory testing. Additionally, increasing investments in personalized medicine and biologics contribute to the region’s dominance.
Europe holds the second-largest market share, at around 28%, supported by stringent regulatory frameworks and a strong focus on environmental and food safety. Countries such as Germany, the United Kingdom, and France are key contributors, leveraging liquid chromatography systems to comply with rigorous EU standards. The region’s emphasis on research and development, along with its well-established pharmaceutical industry, further bolsters market growth. Europe’s adoption of green chromatography practices also reflects its commitment to sustainability, adding a competitive edge to its market presence.
The Asia-Pacific region is anticipated to witness the fastest growth, currently holding about 22% of the global market share. Rapid industrialization, expanding pharmaceutical manufacturing, and increasing healthcare investments in countries like China, India, and Japan are driving demand for liquid chromatography systems. The region’s burgeoning middle class and growing focus on food safety and environmental conservation create additional opportunities for market expansion. Moreover, government initiatives to enhance research capabilities and infrastructure are fostering the adoption of advanced analytical techniques.
Latin America and the Middle East & Africa collectively represent approximately 15% of the market share, with promising growth potential. In Latin America, Brazil and Mexico are leading markets, driven by rising healthcare awareness, increasing investments in pharmaceutical production, and the expansion of food safety regulations. Similarly, the Middle East & Africa region is experiencing growth due to improving industrial infrastructure, rising demand for environmental testing, and government-led efforts to modernize healthcare systems.
Key Player Analysis:
- GE Healthcare (US)
- Gilson (US)
- Hamilton Company (US)
- Hitachi (Japan)
- JASCO (US)
- Merck Millipore (Germany)
- Orochem (US)
- Phenomenex (US)
- Shimadzu (Japan)
- Showa Denko (Japan)
- SIELC (US)
- Thermo Fisher (US)
- Tosoh Bioscience LLC (Japan)
- Trajan Scientific (Australia)
- YMC Co. Ltd. (Japan)
Competitive Analysis:
The liquid chromatography systems market is highly competitive, characterized by the presence of global leaders and regional players focusing on technological innovation and market expansion. Key players such as Agilent Technologies, Thermo Fisher Scientific, Waters Corporation, Shimadzu Corporation, and PerkinElmer dominate the market with their extensive product portfolios and strong global presence. These companies invest significantly in research and development to introduce advanced systems, such as high-performance liquid chromatography (HPLC) and ultra-high-performance liquid chromatography (UHPLC), catering to diverse industrial needs. For instance, Shimadzu Corporation's Nexera series integrates Analytical Intelligence to optimize performance and reduce operational errors. Regional players contribute by offering cost-effective solutions tailored to local requirements, particularly in emerging markets. The market is witnessing growing partnerships and collaborations between manufacturers and academic or industrial research institutions to develop customized solutions. The increasing integration of software and automation in chromatography systems provides a competitive edge, enabling companies to address evolving analytical challenges and strengthen their market positions.
Recent Developments:
- On December 5, 2024, GE Healthcare acquired the remaining 50% stake in Nihon Medi-Physics from Sumitomo Chemical. This strategic move aims to bolster its radiopharmaceutical capabilities and strengthen its presence in the Japanese market.
- Gilson launched its innovative liquid handling solution, SmartRock, on December 17, 2024. Designed to enhance accuracy in liquid chromatography applications, this product underscores Gilson's commitment to advancing laboratory workflows.
- On December 15, 2024, Hamilton Company introduced a new line of high-precision liquid handling robots. These systems aim to improve automation in laboratories, highlighting Hamilton’s focus on cutting-edge analytical solutions.
- Hitachi announced the completion of a share repurchase program on December 23, 2024, reflecting its strategic efforts to strengthen its financial position while maintaining investments in technological innovation.
- On December 20, 2024, Merck Millipore finalized an exclusive global license agreement for LM-299, an investigational anti-PD-1/VEGF bispecific antibody, marking a significant step in its biopharmaceutical expansion.
- Orochem showcased its latest chromatographic innovations at the Chicago IFT Suppliers Expo on November 5, 2024, reaffirming its commitment to advancing separation technologies for the food and beverage industry.
- Shimadzu signed a comprehensive partnership agreement with Shinshu University on August 29, 2024, focusing on advancements in liquid chromatography systems and related technologies.
- On December 10, 2024, Showa Denko announced significant investments in advanced materials for chromatography applications, aiming to meet growing market demands and enhance its product offerings.
- SIELC Technologies launched the Alltesta™ LHS (Liquid Handling Station) on May 12, 2023, designed to improve efficiency and accuracy in high-throughput liquid chromatography applications.
- On December 2, 2024, Thermo Fisher expanded its portfolio with new high-performance liquid chromatography systems, tailored to meet evolving laboratory demands worldwide.
- On November 1, 2024, YMC Co., Ltd. announced updates to its Meteoric Core columns hardware, reinforcing its commitment to improving product performance in liquid chromatography applications.
Market Concentration & Characteristics:
The liquid chromatography systems market is moderately concentrated, with a mix of global leaders and regional players driving innovation and adoption. Dominant companies such as Agilent Technologies, Waters Corporation, Thermo Fisher Scientific, and Shimadzu Corporation hold a significant share due to their extensive product offerings, strong brand recognition, and global distribution networks. These firms focus on high-performance systems like HPLC and UHPLC, catering to advanced analytical needs in pharmaceuticals, biotechnology, and environmental testing. Regional players play a vital role in addressing localized demands, particularly in cost-sensitive markets, by offering tailored and affordable solutions. The market is characterized by rapid technological advancements, including automation, miniaturization, and integration with artificial intelligence, enhancing efficiency and accuracy. Sustainability is emerging as a key characteristic, with increasing adoption of eco-friendly practices and materials. This dynamic landscape underscores the market's adaptability to diverse industries and its emphasis on precision, innovation, and compliance.
Report Coverage:
The research report offers an in-depth analysis based on By Technique, By Type, By Application and By End-User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is projected to experience steady growth, driven by increasing applications in pharmaceuticals and biotechnology.
- Rising demand for personalized medicine and biomarker discovery will boost the adoption of advanced liquid chromatography systems.
- Innovations in automation and AI integration will enhance analytical accuracy and workflow efficiency.
- Expanding environmental monitoring initiatives will create opportunities for chromatography in detecting pollutants and contaminants.
- Growth in food safety regulations will drive the need for precise analysis of contaminants and nutritional profiling.
- Miniaturized and portable chromatography systems will gain traction for on-site and real-time analysis.
- Emerging markets, particularly in Asia-Pacific and Latin America, will witness rapid adoption due to industrialization and healthcare investments.
- Increasing focus on sustainability will spur the development of green chromatography methods and eco-friendly systems.
- Collaboration between manufacturers and research institutions will foster customized solutions for diverse industries.
- Advances in column technology and solvent efficiency will improve system performance and reduce operational costs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Pharmaceutical and Biotechnology Industries
The rapid growth of pharmaceutical and biotechnology sectors is increasing the demand for liquid chromatography systems, which are essential for drug discovery, development, and quality assurance. These systems enable precise analysis of complex mixtures and compliance with stringent regulatory standards, supporting innovation and efficiency in drug development pipelines.
Rising Demand for Environmental Testing
Stricter environmental regulations and heightened public health concerns are driving the adoption of liquid chromatography systems for monitoring water quality, detecting pollutants, and analyzing environmental samples. Their high sensitivity and reliability make them indispensable for regulatory compliance and environmental conservation efforts.
Increasing Applications in Food and Beverage Safety
The food and beverage industry is leveraging liquid chromatography systems to detect contaminants, pesticides, and ensure product authenticity. Growing consumer awareness and regulatory requirements for food safety are fueling the need for advanced analytical solutions in this sector.
Technological Advancements in Analytical Instruments
Innovations such as UHPLC, automation, and integration with advanced software are enhancing the speed, sensitivity, and operational efficiency of liquid chromatography systems. These advancements are broadening the scope of applications and attracting investments from both academic and industrial sectors.
Growth in Personalized Medicine and Biomarker Discovery
The global rise in chronic diseases and the shift toward personalized medicine are increasing the need for precise analytical tools like liquid chromatography systems. These systems play a pivotal role in biomarker discovery, therapeutic monitoring, and the development of targeted therapies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size by 2032?
What are the primary drivers for market growth?
What role does liquid chromatography play in environmental testing?
What are the main challenges in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Consumables
- 1.2.2 Instruments
- 1.2.3 Services
- 1.3 By End-User
- 1.3.1 Academics And Research Institutes
- 1.3.2 Pharmaceutical Companies
- 1.3.3 Hospitals
- 1.3.4 Agriculture Industry
- 1.3.5 Others
- 1.4 By Technique
- 1.4.1 High Performance Liquid Chromatography (HPLC)
- 1.4.2 Ultra High Pressure Liquid Chromatography (UHPLC)
- 1.4.3 Low Pressure Liquid Chromatography (LPLC)
- 1.4.4 Fast Protein Liquid Chromatography (FPLC)
- 1.5 By Application
- 1.5.1 Clinical Diagnostics
- 1.5.2 Environmental Testing
- 1.5.3 Food And Beverage Analysis
- 1.5.4 Forensic Tests
- 1.5.5 Life Sciences
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 10,315 million → 2032: USD 16,565.03 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Liquid Chromatography Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Liquid Chromatography Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Liquid Chromatography Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Liquid Chromatography Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Liquid Chromatography Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Liquid Chromatography Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Liquid Chromatography Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Liquid Chromatography Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 10,315 million → 2032: USD 16,565.03 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Liquid Chromatography Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Consumables
- 12.3.7.2 Instruments
- 12.3.7.3 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Academics And Research Institutes
- 12.4.7.2 Pharmaceutical Companies
- 12.4.7.3 Hospitals
- 12.4.7.4 Agriculture Industry
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technique - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 High Performance Liquid Chromatography (HPLC)
- 12.5.7.2 Ultra High Pressure Liquid Chromatography (UHPLC)
- 12.5.7.3 Low Pressure Liquid Chromatography (LPLC)
- 12.5.7.4 Fast Protein Liquid Chromatography (FPLC)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Clinical Diagnostics
- 12.6.7.2 Environmental Testing
- 12.6.7.3 Food And Beverage Analysis
- 12.6.7.4 Forensic Tests
- 12.6.7.5 Life Sciences
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Liquid Chromatography Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Liquid Chromatography Systems Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Liquid Chromatography Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Liquid Chromatography Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Agilent Technologies
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Thermo Fisher Scientific
- 18.4 Waters Corporation
- 18.5 Shimadzu Corporation
- 18.6 PerkinElmer
- 18.7 GE Healthcare
- 18.8 Merck Millipore
- 18.9 Gilson
- 18.10 Hitachi
- 18.11 YMC Co. Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

