
Market Overview
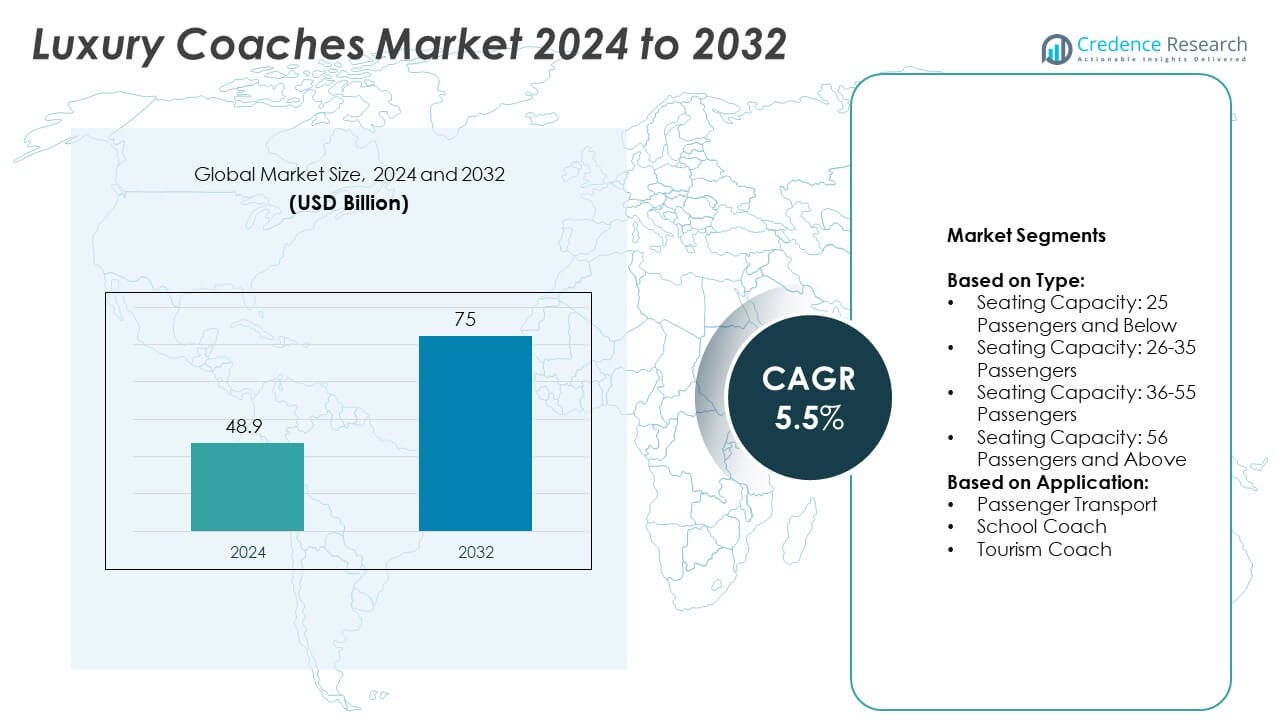
The Luxury Coaches Market size was valued at USD 48.9 billion in 2024 and is anticipated to reach USD 75 billion by 2032, at a CAGR of 5.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Luxury Coaches Market Size 2024 | USD 48.9 Billion |
| Luxury Coaches Market, CAGR | 5.5% |
| Luxury Coaches Market Size 2032 | USD 75 Billion |
The Luxury Coaches market grows steadily, driven by rising demand for premium travel experiences, expanding tourism, and increasing adoption of advanced mobility solutions. It benefits from technological innovations such as AI-powered driver assistance, real-time monitoring, and smart connectivity that enhance passenger comfort and operational efficiency. Growing environmental awareness pushes manufacturers to focus on electric and hybrid luxury coaches, aligning with global sustainability goals. Increasing disposable incomes and changing lifestyle preferences accelerate the shift toward personalized and high-end transportation.
The Luxury Coaches market shows strong growth across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, driven by rising tourism, advanced infrastructure, and increasing demand for premium transportation. North America and Europe lead with high adoption of electric and hybrid luxury fleets, while Asia Pacific experiences rapid expansion due to growing urbanization and tourism activities. Key players shaping the market include BYD Auto, Daimler Truck, Alexander Dennis Limited (ADL), and Yutong Bus, focusing on innovation and sustainability.
Market Insights
- The Luxury Coaches market was valued at USD 48.9 billion in 2024 and is projected to reach USD 75 billion by 2032, growing at a CAGR of 5.5% during the forecast period.
- Rising demand for premium travel experiences, advanced mobility solutions, and growing tourism activities are driving the market’s expansion globally.
- Technological advancements, including AI-powered driver assistance, smart connectivity, electric powertrains, and real-time monitoring systems, are shaping market trends and improving passenger comfort.
- The competitive landscape is marked by innovation and strategic partnerships, with key players such as BYD Auto, Daimler Truck, Alexander Dennis Limited (ADL), Yutong Bus, and Irizar Group investing in sustainable solutions.
- High operational costs, strict environmental regulations, and infrastructure limitations like inadequate charging stations act as major restraints for the market.
- North America leads due to strong adoption of luxury fleets and technological integration, while Europe benefits from cross-border travel demand, and Asia Pacific grows rapidly with increasing tourism and urbanization.
- The market witnesses rising investment in electric and hybrid coaches globally, with regional governments supporting eco-friendly initiatives, creating significant opportunities for manufacturers and fleet operators.
Market Drivers
Growing Demand for Premium Travel Experiences
The Luxury Coaches market experiences significant growth due to rising demand for premium and comfortable travel options. Consumers increasingly prefer coaches with advanced seating, entertainment systems, and personalized amenities for long-distance journeys. Tourism operators and private service providers focus on enhancing passenger comfort to attract high-value customers. It invests heavily in modern interiors, better ergonomics, and noise reduction technologies to improve ride quality. Increased spending power and evolving lifestyle preferences encourage travelers to opt for luxury services. Expanding cross-border tourism activities further strengthen the adoption of premium coach solutions globally.
- For instance, Daimler Buses secured a landmark order from Busitalia in Italy for 111 luxury coaches-comprising 80 Mercedes‑Benz Tourismo, 20 Mercedes‑Benz Tourismo M/3, and 11 Setra S 531 DT double-decker buses-with delivery slated to conclude by the end of 2025. This €43 million contract, managed by Daimler Buses Italia, includes a 10-year maintenance contract and a Digital Services Package.
Advancements in Vehicle Technology and Design
Technological innovations drive strong demand in the Luxury Coaches market by improving vehicle performance, safety, and passenger experience. Manufacturers integrate smart navigation systems, automated controls, and energy-efficient drivetrains to deliver superior functionality. It adopts lightweight materials, optimized aerodynamics, and modern designs to enhance fuel efficiency and operational sustainability. Advanced connectivity features, including Wi-Fi and infotainment systems, improve passenger convenience during long-distance travel. Integration of AI-powered driver assistance systems boosts operational safety and reliability. These developments position luxury coaches as a preferred alternative to conventional travel modes.
- For instance, Temsa delivered six TS35 luxury mini-coaches to Yankee Line in Boston, each with 21‑passenger two-plus-one seating arranged for executive comfort, offering satellite TV, USB ports, and a custom galley.
Rising Tourism and Cross-Border Travel
The Luxury Coaches market benefits from growing domestic and international tourism activities across emerging and developed regions. It plays a vital role in providing premium group travel services for tourism, corporate events, and leisure activities. Government initiatives promoting tourism infrastructure encourage investments in high-end transportation services. Increased demand for chartered coaches from travel agencies and tour operators supports consistent market expansion. Luxury coaches offer flexibility, enhanced comfort, and convenience for both short-distance and interstate journeys. Rising business travel trends also contribute significantly to overall revenue growth.
Sustainability and Adoption of Eco-Friendly Solutions
Environmental concerns and stricter emission regulations accelerate innovation in the Luxury Coaches market. It focuses on adopting cleaner technologies such as electric, hybrid, and fuel-efficient engines to meet global sustainability goals. Manufacturers develop advanced powertrains that reduce fuel consumption without compromising passenger comfort. Governments and operators collaborate to introduce zero-emission luxury fleets across urban and tourist regions. The shift towards green mobility creates opportunities for integrating renewable energy solutions into coach operations. Increased preference for sustainable transportation enhances the long-term market potential.
Market Trends
Integration of Advanced Digital Technologies
The Luxury Coaches market witnesses a significant shift with the adoption of smart technologies and digital solutions. Manufacturers focus on equipping vehicles with advanced infotainment systems, real-time tracking, and automated passenger assistance features. It leverages AI-based predictive maintenance tools to improve vehicle performance and reduce downtime. Smart connectivity solutions enhance customer experience through seamless Wi-Fi, entertainment platforms, and mobile app integrations. Integration of data analytics supports operators in optimizing routes and fuel efficiency. This trend reshapes the passenger experience and strengthens competitive positioning for manufacturers.
- For instance, Scania received a substantial order of 231 new buses for Tenerife’s public transport operator, of which 173 were hybrid units, significantly boosting their hybrid vehicle fleet.
Growing Preference for Customization and Premium Interiors
Consumers increasingly demand personalized travel experiences, driving the growth of luxury coach customization. The Luxury Coaches market focuses on offering tailor-made designs with advanced seating layouts, ambient lighting, and entertainment options. It emphasizes high-quality materials, ergonomic seating, and improved cabin aesthetics to meet evolving customer expectations. Rising competition encourages operators to differentiate their services by providing premium onboard features. Enhanced storage options, integrated charging systems, and climate-controlled environments improve travel comfort. This customization trend appeals strongly to high-income travelers seeking exclusive and luxurious mobility solutions.
- For instance, The Coach Travel Group purchased 42 brand-new Scania Touring coaches, showcasing a significant fleet modernization at Euro Bus Expo.
Shift Towards Sustainable and Green Mobility Solutions
Sustainability emerges as a key trend shaping the future of the Luxury Coaches market. Manufacturers invest in electric, hybrid, and low-emission technologies to comply with global environmental regulations. It focuses on developing fuel-efficient engines and adopting lightweight materials to minimize carbon emissions. Growing government initiatives promoting eco-friendly transport encourage operators to transition toward green fleets. Demand for zero-emission coaches rises across urban regions and tourist destinations. This shift toward sustainability supports long-term operational cost savings while improving the environmental footprint of the industry.
Rising Demand for Tourism and Cross-Border Luxury Travel
The Luxury Coaches market experiences growth due to expanding tourism activities and international travel demand. Tour operators invest in high-end coaches to cater to premium travelers seeking comfort and convenience. It drives higher adoption rates across destinations where group travel plays a significant role. Increasing cross-border business travel boosts the need for luxury fleet services. Government-backed infrastructure development enhances connectivity, further fueling market expansion. This rising focus on luxury tourism opens opportunities for operators to expand their service portfolios globally.
Market Challenges Analysis
High Operational Costs and Intense Price Competition
The Luxury Coaches market faces significant challenges due to high operational and maintenance expenses. Advanced technologies, premium interiors, and fuel-efficient engines increase production costs for manufacturers and operators. It struggles to maintain profitability while meeting customer demands for enhanced features and superior comfort. Rising fuel prices, fluctuating raw material costs, and compliance with safety regulations put pressure on margins. Intense price competition among regional and global players limits pricing flexibility, affecting long-term growth strategies. Operators must balance cost optimization with service quality to remain competitive in the market.
Regulatory Compliance and Infrastructure Limitations
Strict environmental policies and safety regulations create operational hurdles for the Luxury Coaches market. Manufacturers invest heavily in research and innovation to meet emission norms and adopt sustainable technologies. It faces challenges in markets with underdeveloped road infrastructure, limited charging stations, and inadequate parking facilities. High taxation on luxury vehicles and import duties further restrict market penetration in several regions. Rapidly changing regulatory frameworks require continuous adaptation, increasing operational complexities for stakeholders. These factors collectively slow down expansion plans and demand strategic investments to ensure market resilience.
Market Opportunities
Rising Demand for Premium Tourism and Corporate Travel
The Luxury Coaches market presents significant opportunities with the growing preference for high-end travel experiences. Increasing tourism activities, business events, and long-distance travel requirements drive demand for advanced and comfortable transportation solutions. It attracts premium travelers seeking customized interiors, enhanced safety, and superior onboard amenities. Expansion of the hospitality and tourism sectors encourages operators to invest in modern fleets with innovative features. Government initiatives to promote tourism infrastructure further boost opportunities for service providers. Growing partnerships between tour operators and luxury coach manufacturers support sustainable revenue growth.
Adoption of Electric and Smart Mobility Solutions
Technological advancements create new opportunities for the Luxury Coaches market, with a strong focus on sustainability and digital integration. Operators increasingly adopt electric and hybrid coaches to reduce emissions and improve energy efficiency. It benefits from the rising availability of charging infrastructure and government incentives for green mobility solutions. Integration of advanced telematics, AI-based driver assistance, and real-time monitoring systems enhances operational performance. Smart mobility solutions improve passenger comfort and strengthen the appeal of luxury fleets. This shift toward eco-friendly and tech-enabled transportation opens new avenues for long-term market expansion.
Market Segmentation Analysis:
By Type:
The Luxury Coaches market is segmented by seating capacity, addressing diverse customer needs across travel and tourism sectors. Coaches with seating capacity for 25 passengers and below gain popularity in urban and corporate segments due to their flexibility and premium comfort. It caters to small groups seeking personalized services with advanced interiors and enhanced safety features. The 26-35 passenger segment shows steady demand from business travel and mid-sized tourism operators requiring cost-effective yet luxurious mobility. The 36-55 passenger category dominates the market, driven by large tour groups and intercity travel operators seeking efficiency and higher occupancy rates. Coaches with seating capacity for 56 passengers and above serve premium long-distance routes, offering advanced features like reclining seats, entertainment systems, and spacious designs to enhance passenger experience.
- For instance, Van Hool has a significant presence in North America, with over 11,000 coaches and buses on U.S. roads, supported by its exclusive distributor, ABC Companies. This large deployment, which includes high-profile clients like Silicon Valley companies, highlights Van Hool's established role in the private coach and bus market, a partnership that began over three decades ago.
By Application:
The Luxury Coaches market, when viewed by application, is driven by diverse usage patterns across transportation services. Passenger transport remains the largest contributor, supported by growing urban mobility needs and corporate travel requirements. It benefits from increased adoption among private operators investing in high-end fleets to attract premium customers. The school coach segment witnesses steady growth as educational institutions prioritize safety, comfort, and advanced monitoring systems for student transportation. Tourism coaches represent a rapidly growing segment, supported by rising global travel activities and increasing demand for personalized group travel solutions. Investments by travel operators in luxury features, connectivity solutions, and eco-friendly models continue to strengthen this segment's expansion. Growing collaboration between tourism boards and transportation providers further supports market penetration across developing and developed regions.
- For instance, Scania‑Higer delivered 16 Scania Touring luxury coaches to Shanghai Airport Bus Company. These coaches were deployed for shuttle services among Hongqiao Airport, Pudong Airport, and Shanghai Disneyland, marking the largest order for Scania Touring coaches in China to that date.
Segments:
Based on Type:
- Seating Capacity: 25 Passengers and Below
- Seating Capacity: 26-35 Passengers
- Seating Capacity: 36-55 Passengers
- Seating Capacity: 56 Passengers and Above
Based on Application:
- Passenger Transport
- School Coach
- Tourism Coach
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest share of the Luxury Coaches market, accounting for 32% in 2024, driven by rising demand for premium travel solutions and advanced transportation infrastructure. The region benefits from strong tourism activity, expanding corporate travel, and increasing investments in high-end mobility services. It witnesses significant adoption of luxury coaches by private operators and travel companies focusing on personalized group travel experiences. Integration of advanced technologies, including real-time tracking, onboard entertainment, and Wi-Fi connectivity, enhances customer satisfaction. Leading manufacturers focus on expanding their presence in the U.S. and Canada, supported by government initiatives for sustainable mobility. The growing demand for electric and hybrid luxury coaches further strengthens regional market performance.
Europe
Europe represents a substantial share of the Luxury Coaches market, contributing 27% in 2024, supported by high tourism inflows and extensive cross-border travel demand. The region has a well-developed transportation infrastructure, enabling greater adoption of advanced luxury fleets. It experiences increased investments from operators focusing on integrating smart technologies and sustainable powertrains into their fleets. European consumers prefer customized interiors and eco-friendly models, driving innovation in electric and hybrid luxury coaches. Key countries such as Germany, France, and the UK play a major role in shaping market dynamics due to strong demand for premium travel experiences. Government initiatives promoting low-emission transport and stricter environmental policies further accelerate market growth in the region.
Asia Pacific
Asia Pacific captures 24% of the Luxury Coaches market in 2024, propelled by expanding tourism, rising disposable incomes, and rapid urbanization. The region witnesses significant growth in countries like China, Japan, India, and South Korea, where demand for premium long-distance travel is increasing. It benefits from large-scale investments in infrastructure development and cross-country connectivity projects. Luxury coach manufacturers focus on introducing cost-effective models with advanced interiors to cater to price-sensitive yet experience-driven consumers. Growing government support for electric and fuel-efficient coaches further boosts adoption in this region. Increasing partnerships between travel operators and tourism boards enhance the availability of luxury transport services across popular tourist destinations.
Middle East & Africa
The Middle East & Africa account for 10% of the Luxury Coaches market in 2024, driven by growing tourism, religious travel, and rising luxury lifestyle preferences. Countries like the UAE, Saudi Arabia, and South Africa are major contributors, with increasing investments in premium travel infrastructure. It benefits from high demand for customized luxury fleets among hospitality chains, event organizers, and tourism operators. Expanding adoption of advanced safety systems, real-time tracking, and entertainment features improves passenger comfort. Government initiatives to promote tourism diversification in the Gulf Cooperation Council (GCC) countries significantly boost opportunities for market growth.
Latin America
Latin America holds 7% of the Luxury Coaches market in 2024, supported by expanding tourism and improved transportation infrastructure. Countries such as Brazil, Mexico, and Argentina contribute significantly to regional demand for premium group travel services. It experiences rising investments from operators offering advanced luxury fleets with modern interiors and safety features. The growing focus on cross-border travel, particularly for tourism and corporate events, drives fleet modernization. Technological integration, coupled with the adoption of fuel-efficient models, strengthens overall market expansion in the region.
Key Player Analysis
- BYD Auto (Electric Coaches)
- Daimler Truck
- King Long United Automotive
- Alexander Dennis Limited (ADL)
- Yutong Bus
- Irizar Group
- Beiqi Foton Motor
- Scania
- Foretravel Motorcoach
- Ankai
Competitive Analysis
The leading players in the Luxury Coaches market include BYD Auto (Electric Coaches), Daimler Truck, King Long United Automotive, Alexander Dennis Limited (ADL), Yutong Bus, Irizar Group, Beiqi Foton Motor, Scania, Foretravel Motorcoach, and Ankai. These companies focus on expanding their product portfolios by introducing advanced, technology-driven, and eco-friendly luxury coaches to meet evolving consumer preferences. The market witnesses growing investments in electric and hybrid powertrains to comply with environmental regulations and reduce operating costs. Manufacturers prioritize premium interiors, enhanced safety systems, and improved passenger comfort to strengthen customer loyalty and increase adoption. Strategic collaborations with tourism operators, fleet owners, and government bodies support large-scale deployments of luxury fleets across emerging and developed regions. Research and development remain a key focus area, with companies integrating real-time monitoring systems, smart connectivity, and AI-powered driver assistance features. Rising competition encourages players to expand their global footprint through mergers, partnerships, and distribution agreements. Innovation in sustainable designs and cost-effective production methods positions these companies competitively in the growing demand for premium travel solutions. The market’s growth potential drives continuous product upgrades and adoption of advanced technologies to capture a wider customer base and maintain leadership.
Recent Developments
- In June 2025, BYD announced plans to expand its electric bus and truck production in Komárom, northern Hungary, tripling the plant’s annual capacity to 1,250 vehicles
- In 2025, ADL opened a manufacturing facility in Las Vegas and delivered Enviro500 double-deckers to RTC
- In 2024, Volvo Bus India won a historic order for 122 high-end 9600 luxury coaches under the Government of Odisha's LAccMI Scheme. The coaches will improve public transport by linking major business districts and commercial centers to the state capital and Jagannath Dham Puri.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Luxury Coaches market will experience steady growth driven by rising demand for premium travel solutions.
- Manufacturers will focus on integrating advanced technologies to enhance passenger comfort and safety.
- Electric and hybrid luxury coaches will gain strong traction due to stricter emission regulations and sustainability goals.
- Tourism expansion and cross-border travel will create significant opportunities for luxury fleet operators.
- Customization in interiors, seating layouts, and entertainment systems will remain a major differentiator for premium customers.
- Adoption of AI-powered driver assistance and real-time monitoring systems will improve operational efficiency.
- Strategic partnerships between manufacturers, tourism operators, and fleet owners will strengthen global market presence.
- Demand for luxury coaches in corporate travel and event transportation will continue to grow.
- Investments in charging infrastructure will accelerate the shift toward electric and zero-emission fleets.
- Increasing consumer preference for sustainable, tech-enabled, and personalized travel solutions will define future market trends.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand for Premium Travel Experiences
Consumers are increasingly seeking comfortable, high-end travel options with advanced amenities, driving operators and manufacturers to invest in luxury coaches with superior interiors, entertainment systems, and personalized features.
Advancements in Vehicle Technology and Design
Integration of AI-powered driver assistance, real-time monitoring, smart connectivity, and energy-efficient drivetrains is enhancing passenger comfort, safety, and operational efficiency, making luxury coaches more attractive to both operators and travelers.
Rising Tourism and Cross-Border Travel
Expanding domestic and international tourism, along with increased business and leisure travel, is boosting demand for luxury coaches that offer group travel solutions with enhanced comfort and flexibility.
Sustainability and Adoption of Eco-Friendly Solutions
Stricter emission regulations and growing environmental awareness are pushing manufacturers to develop electric and hybrid luxury coaches, aligning with global sustainability goals and attracting eco-conscious customers.
Customization and Premium Interiors
The trend toward personalized travel experiences is leading to higher demand for coaches with tailor-made seating layouts, ambient lighting, and advanced entertainment options, differentiating offerings in a competitive market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Luxury Coaches market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Luxury Coaches Market projected to grow between 2025 and 2032?
Which Luxury Coaches market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Luxury Coaches market?
Who are the leading companies in the Luxury Coaches Market?
Which region commanded the largest share of the Luxury Coaches market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Passenger Transport
- 1.2.2 School Coach
- 1.2.3 Tourism Coach
- 1.3 By Propulsion Type
- 1.3.1 Diesel
- 1.3.2 Hybrid
- 1.3.3 Electric
- 1.4 By Seating Capacity
- 1.4.1 25 Passengers and Below
- 1.4.2 26-35 Passengers
- 1.4.3 36-55 Passengers
- 1.4.4 56 Passengers and Above
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 48.9 billion → 2032: USD 75 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Luxury Coaches Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Luxury Coaches Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Luxury Coaches Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Luxury Coaches Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Luxury Coaches Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Luxury Coaches Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Luxury Coaches Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Luxury Coaches Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 48.9 billion → 2032: USD 75 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Luxury Coaches Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Passenger Transport
- 12.3.7.2 School Coach
- 12.3.7.3 Tourism Coach
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Propulsion Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Diesel
- 12.4.7.2 Hybrid
- 12.4.7.3 Electric
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Seating Capacity - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 25 Passengers and Below
- 12.5.7.2 26-35 Passengers
- 12.5.7.3 36-55 Passengers
- 12.5.7.4 56 Passengers and Above
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Luxury Coaches End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Luxury Coaches Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Luxury Coaches Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Luxury Coaches Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BYD Auto
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Daimler Truck
- 18.4 Alexander Dennis Limited (ADL)
- 18.5 Yutong Bus
- 18.6 Irizar Group
- 18.7 King Long United Automotive
- 18.8 Beiqi Foton Motor
- 18.9 Scania
- 18.10 Foretravel Motorcoach
- 18.11 Ankai
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

