
Market Overview
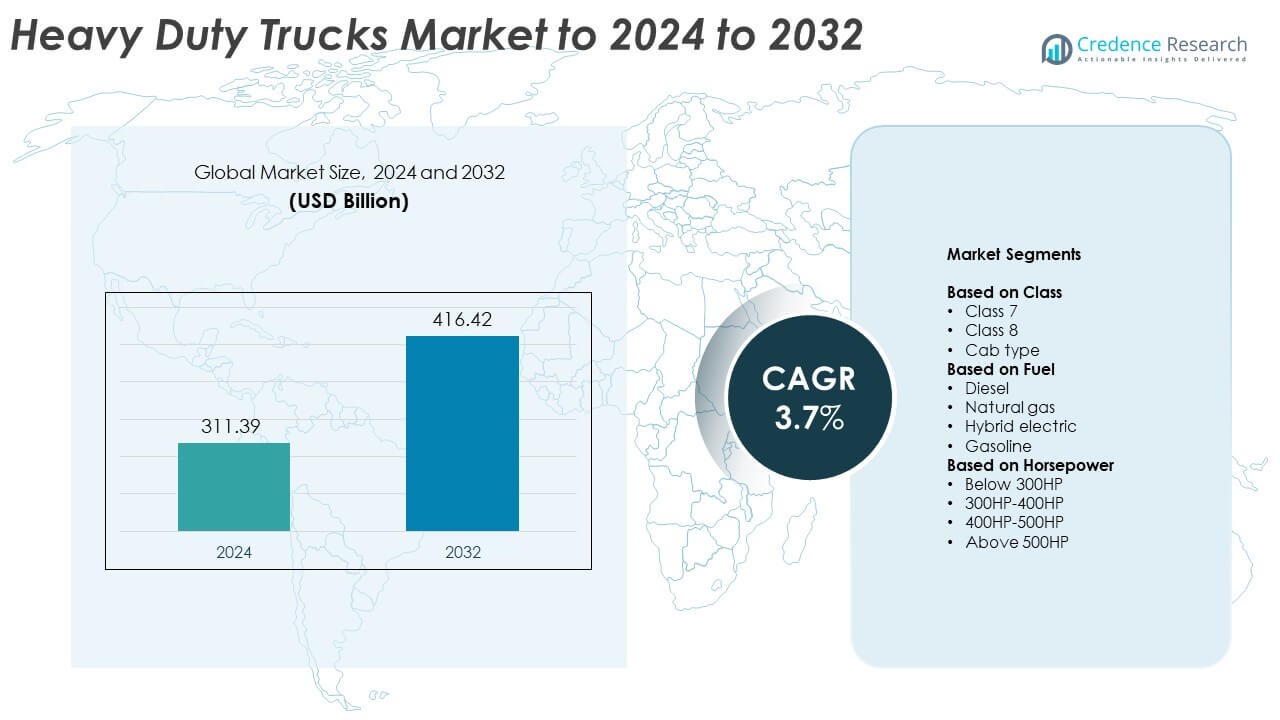
The Heavy Duty Trucks Market size was valued at USD 311.39 billion in 2024 and is anticipated to reach USD 416.42 billion by 2032, at a CAGR of 3.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Heavy Duty Trucks Market Size 2024 | USD 311.39 Billion |
| Heavy Duty Trucks Market, CAGR | 3.7% |
| Heavy Duty Trucks Market Size 2032 | USD 416.42 Billion |
The Heavy Duty Trucks market is shaped by major players such as Volvo Trucks, Navistar, MAN, Mack Trucks, Kenworth, Daimler, Isuzu Motors, Scania AB, Hyzon Motors, Freightliner, Peterbilt, and PACCAR (Peterbilt, Kenworth, DAF). These companies compete through innovation in fuel-efficient engines, connected vehicle technologies, and autonomous driving systems. Product diversification and regional expansion strategies enhance their global presence. North America leads the market with a 37% share, followed by Europe at 28% and Asia Pacific at 25%. Continuous advancements in powertrain technologies, fleet electrification, and digital logistics management continue to define the competitive landscape.
Market Insights
- The Heavy Duty Trucks Market was valued at USD 311.39 billion in 2024 and is projected to reach USD 416.42 billion by 2032, growing at a CAGR of 3.7%.
- Rising freight transportation demand, industrial expansion, and infrastructure development are driving the adoption of Class 8 heavy-duty trucks globally.
- The market is witnessing a strong trend toward electrification, digital connectivity, and integration of autonomous driving and telematics systems to enhance fleet efficiency.
- Competition is shaped by innovation in powertrain design, emission reduction technologies, and partnerships between OEMs and logistics operators to improve supply chain efficiency.
- North America leads the market with a 37% share, followed by Europe at 28% and Asia Pacific at 25%, while the Class 8 segment dominates with nearly 80% of total market volume.
Market Segmentation Analysis:
By Class
The Class 8 segment dominated the heavy-duty trucks market with nearly 80% share in 2024. This segment’s leadership is driven by its use in long-haul freight, construction, and mining operations that demand high payload capacity and endurance. Class 8 trucks are preferred for their durability, advanced powertrains, and enhanced fuel efficiency. Ongoing fleet modernization programs and stricter emission standards encourage companies to adopt new-generation models with telematics, driver-assist, and autonomous features. As infrastructure investments expand across major economies, demand for Class 8 vehicles continues to accelerate globally.
- For instance, PACCAR MX-13 delivers 405–510 hp and 1,550–1,850 lb-ft torque, with B10 life 1,000,000 miles.
By Fuel
The diesel segment accounted for approximately 55% of the market share in 2024, supported by its unmatched energy density and fuel efficiency in heavy-duty applications. Diesel trucks remain the backbone of logistics and industrial transport due to established fueling infrastructure and lower total ownership costs. However, the market is witnessing a gradual shift toward cleaner alternatives such as natural gas and hybrid electric variants. OEMs are introducing LNG and CNG-powered models to reduce carbon emissions, while hybrid systems enhance fuel economy and comply with evolving environmental regulations.
- For instance, Cummins X15N natural-gas engine provides 400–500 hp and 1,450–1,850 lb-ft torque.
By Horsepower
The 400HP–500HP category held about 36% of the global market share in 2024, reflecting its balance between performance and operating efficiency. Trucks in this range are widely used for regional and intercity logistics, offering robust towing capacity and reliability across diverse terrains. Manufacturers are incorporating advanced engine management systems and lightweight materials to boost torque output while minimizing fuel consumption. Growing adoption in construction, mining, and logistics sectors reinforces this segment’s strong position, as fleet owners prioritize vehicles that deliver higher productivity and lower lifecycle costs.
Key Growth Drivers
Rising Freight Transportation Demand
The growing global trade and e-commerce expansion are key drivers for the heavy-duty trucks market. Increasing movement of goods across long distances requires robust transport solutions capable of handling large payloads. Fleet operators are investing in advanced trucks with higher fuel efficiency and improved connectivity to optimize logistics performance. Infrastructure development projects and cross-border trade routes are further boosting heavy-duty vehicle adoption in logistics and distribution networks worldwide.
- For instance, Euro VI caps NOx at 0.40 g/kWh (steady-state) and PM at 0.01 g/kWh; U.S. EPA 2010 sets 0.20 g/bhp-hr NOx and 0.01 g/bhp-hr PM.
Advancements in Powertrain and Emission Technology
Technological improvements in engines, hybrid systems, and emission control solutions are accelerating market growth. Manufacturers are integrating advanced turbocharged engines, after-treatment systems, and low-emission powertrains to meet global sustainability goals. Compliance with Euro VI and EPA emission standards drives demand for cleaner and more efficient trucks. OEMs are also investing in alternative fuel technologies like LNG and hydrogen, expanding the market for next-generation heavy-duty vehicles.
- For instance, Volvo Trucks reports cumulative fuel economy improvements of up to 13% for the I-Save package since its 2019 introduction, with independent tests showing reductions of up to 18% compared to a standard FH model from 2018.
Infrastructure and Industrial Growth
Expanding construction, mining, and energy sectors contribute significantly to the demand for heavy-duty trucks. Large-scale infrastructure projects require high-capacity vehicles for material handling and transportation. Urbanization in developing economies and growing investments in road development are fueling regional truck demand. Governments’ focus on industrial expansion and logistics modernization continues to strengthen the long-term growth outlook of the market.
Key Trends and Opportunities
Adoption of Electric and Hybrid Heavy Trucks
The market is witnessing a major shift toward electric and hybrid truck models as sustainability becomes a priority. Manufacturers are launching battery-electric variants suitable for medium and long-haul transport. Improvements in charging infrastructure, battery density, and cost reduction are making these vehicles commercially viable. This transition creates growth opportunities for OEMs and logistics companies targeting lower operational emissions.
- For instance, Freightliner eCascadia offers different configurations, including a 438 kWh battery pack with a typical 230-mile range and a 291 kWh pack with a typical 155-mile range.
Integration of Connected and Autonomous Technologies
The adoption of telematics, IoT, and autonomous driving systems is reshaping truck fleet management. Real-time data analytics improves route planning, fuel optimization, and safety performance. Advanced driver-assistance systems (ADAS) and remote diagnostics enhance efficiency and reduce downtime. This technological shift is opening new avenues for predictive maintenance and smart fleet operations.
- For instance, Volvo Trucks announced an FH Aero Electric variant targeting a 600 km (373 miles) range per charge, with orders scheduled to open in the second quarter of 2026.
Key Challenges
High Operating and Maintenance Costs
The heavy-duty truck market faces challenges due to the high costs associated with vehicle acquisition, maintenance, and fuel. Smaller fleet operators often struggle to manage rising expenses related to parts replacement, skilled labor, and emission compliance. Additionally, volatile fuel prices and inflationary pressures limit profit margins, pushing companies to focus on cost-efficient operations and fleet optimization.
Stringent Emission and Safety Regulations
Increasingly strict global emission norms and safety mandates present operational challenges for manufacturers. Meeting regulatory standards requires heavy investments in R&D, advanced materials, and testing technologies. While these measures improve environmental performance, they also increase production costs and delay product launches. Balancing sustainability with affordability remains a critical issue for the industry.
Regional Analysis
North America
North America held around 37% of the global heavy-duty trucks market share in 2024. The region’s dominance is supported by strong logistics networks, large-scale freight movement, and growing demand for advanced Class 8 trucks. The U.S. remains a key contributor due to fleet modernization and infrastructure upgrades under federal investment programs. Adoption of electric and hybrid models is increasing, driven by emission reduction mandates and sustainable freight initiatives. Canada and Mexico also experience steady demand, supported by cross-border trade and industrial expansion across mining, construction, and manufacturing sectors.
Europe
Europe accounted for nearly 28% of the heavy-duty trucks market share in 2024. Stringent emission norms and the rise of zero-emission zones are accelerating the adoption of electric and hybrid trucks. Countries such as Germany, France, and the U.K. are investing heavily in clean mobility infrastructure. The region’s advanced automotive manufacturing base and high adoption of telematics systems enhance efficiency and compliance. Fleet operators are upgrading to Euro VI-compliant vehicles, while logistics digitalization and government incentives for sustainable transport continue to drive steady growth.
Asia Pacific
Asia Pacific captured about 25% of the global heavy-duty trucks market in 2024, led by China, Japan, and India. Strong industrial output, urban infrastructure projects, and rising e-commerce logistics fuel market expansion. China dominates regional production with large-scale fleet replacement programs and increased focus on low-emission vehicles. India’s “Make in India” initiative and highway development projects drive strong domestic demand. Rapid urbanization, coupled with expanding cross-border trade, strengthens the region’s outlook. Investments in smart logistics and electric truck development further support sustained market growth.
Latin America
Latin America accounted for nearly 6% of the heavy-duty trucks market share in 2024. Brazil and Mexico are key contributors, driven by the recovery of construction and agricultural industries. Economic growth and expansion in mining and energy sectors create new opportunities for fleet purchases. However, volatile fuel prices and financing constraints limit rapid adoption. Manufacturers are targeting this market with fuel-efficient and durable models suitable for challenging terrains. Government programs to modernize transport infrastructure are expected to boost long-term demand.
Middle East and Africa
The Middle East and Africa region represented around 4% of the global heavy-duty trucks market in 2024. Growing oil and gas projects, infrastructure development, and mining operations drive steady demand for heavy trucks. The Gulf countries are investing in smart logistics corridors and renewable construction projects, supporting future sales. South Africa remains a key market in Sub-Saharan Africa, where commercial vehicle demand is rising for industrial applications. Although limited manufacturing capacity and cost barriers slow growth, regional diversification efforts continue to enhance import and fleet expansion activities.
Market Segmentations:
By Class
- Class 7
- Class 8
- Cab type
By Fuel
- Diesel
- Natural gas
- Hybrid electric
- Gasoline
By Horsepower
- Below 300HP
- 300HP-400HP
- 400HP-500HP
- Above 500HP
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Heavy Duty Trucks market features leading manufacturers such as Volvo Trucks, Navistar, MAN, Mack Trucks, Kenworth, Daimler, Isuzu Motors, Scania AB, Hyzon Motors, Freightliner, Peterbilt, and PACCAR (Peterbilt, Kenworth, DAF). These companies focus on developing energy-efficient, durable, and connected vehicle platforms to meet global demand for sustainable logistics solutions. The competitive environment is marked by continuous investment in advanced powertrains, electric mobility, and autonomous driving technologies. Manufacturers are strengthening production capabilities, expanding aftersales networks, and forming alliances with component suppliers and digital solution providers. Increasing emphasis on lightweight materials, digital fleet monitoring, and predictive maintenance is transforming product strategies. Firms are also aligning with regional emission norms, sustainability goals, and evolving customer needs through modular vehicle architectures. This competition drives technological innovation and enhances reliability, ensuring long-term growth opportunities in the global heavy-duty transport ecosystem.
Key Player Analysis
- Volvo Trucks
- Navistar
- MAN
- Mack Trucks
- Kenworth
- Daimler
- Isuzu Motors
- Scania AB
- Hyzon Motors
- Freightliner
- Peterbilt
- PACCAR (Peterbilt, Kenworth, DAF)
Recent Developments
- In 2024, Volvo Group (AB Volvo) Launched a major product overhaul, including the all-new Volvo VNL long-haul truck for North America, featuring a new platform for improved fuel efficiency.
- In 2024, PACCAR (Peterbilt, Kenworth, DAF) Exhibited next-generation commercial vehicles at CES, including hydrogen fuel cell (Kenworth), battery-electric (Peterbilt and DAF), and advanced driver-assist systems. Launched Amplify Cell Technologies, a U.S. battery manufacturing joint venture.
- In 2022, Daimler Truck (Freightliner, Western Star, Mercedes-Benz) Launched the new Western Star 57X on-highway truck in North America, featuring Detroit engines and DT12 automated manual transmissions for improved fuel efficiency.
Report Coverage
The research report offers an in-depth analysis based on Class, Fuel, Horsepower and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Electric and hybrid heavy-duty trucks will gain strong adoption due to stricter emission rules.
- Manufacturers will focus on lightweight materials to improve fuel efficiency and payload capacity.
- Autonomous driving and advanced driver-assistance systems will enhance fleet safety and reliability.
- Digital connectivity and telematics integration will become standard features for real-time monitoring.
- Hydrogen fuel cell trucks will emerge as a sustainable alternative for long-haul transport.
- Fleet electrification incentives and infrastructure development will accelerate clean mobility adoption.
- Aftermarket services and predictive maintenance solutions will see rising investment.
- Asia Pacific will continue leading global production and fleet deployment expansion.
- Partnerships between OEMs and logistics providers will strengthen digital fleet management.
- Ongoing R&D in energy storage and charging technology will redefine operational efficiency.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Freight Transportation Demand
Global trade growth and the expansion of e-commerce are increasing the need for robust heavy-duty trucks capable of long-haul and high-payload operations. This drives fleet operators to invest in advanced vehicles to optimize logistics and meet delivery timelines.
Advancements in Powertrain and Emission Technology
Continuous improvements in engine efficiency, hybrid systems, and emission control technologies are enabling manufacturers to meet stricter environmental regulations. These advancements make new trucks more attractive to buyers seeking compliance and lower operating costs.
Infrastructure and Industrial Growth
Large-scale infrastructure projects, urbanization, and industrial expansion in emerging and developed markets are fueling demand for heavy-duty trucks for construction, mining, and material transport applications.
Electrification and Alternative Fuels
The shift toward electric, hybrid, and alternative fuel trucks is gaining momentum as sustainability becomes a priority. OEMs are launching new models and investing in charging and fueling infrastructure, opening new growth avenues for the market.
Digital Connectivity and Autonomous Technologies
Integration of telematics, IoT, and autonomous driving systems is enhancing fleet management, safety, and operational efficiency. These technologies are increasingly becoming standard, driving adoption among logistics and transport companies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Heavy Duty Trucks Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Heavy Duty Trucks Market projected to grow between 2025 and 2032?
Which Heavy Duty Trucks Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Heavy Duty Trucks Market?
Who are the leading companies in the Heavy Duty Trucks Market?
Which region commanded the largest share of the Heavy Duty Trucks Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Fuel
- 1.2.1 Diesel
- 1.2.2 Natural gas
- 1.2.3 Hybrid electric
- 1.2.4 Gasoline
- 1.3 By Class
- 1.3.1 Class 7
- 1.3.2 Class 8
- 1.3.3 Cab type
- 1.4 By Horsepower
- 1.4.1 Below 300HP
- 1.4.2 300HP-400HP
- 1.4.3 400HP-500HP
- 1.4.4 Above 500HP
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 311.39 billion → 2032: USD 416.42 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Heavy Duty Truck Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Heavy Duty Truck Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Heavy Duty Truck Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Heavy Duty Truck Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Heavy Duty Truck Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Heavy Duty Truck Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Heavy Duty Truck Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Heavy Duty Truck Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 311.39 billion → 2032: USD 416.42 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Heavy Duty Truck Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Fuel - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Diesel
- 12.3.7.2 Natural gas
- 12.3.7.3 Hybrid electric
- 12.3.7.4 Gasoline
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Class - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Class 7
- 12.4.7.2 Class 8
- 12.4.7.3 Cab type
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Horsepower - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Below 300HP
- 12.5.7.2 300HP-400HP
- 12.5.7.3 400HP-500HP
- 12.5.7.4 Above 500HP
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Heavy Duty Truck Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Heavy Duty Truck Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Heavy Duty Truck Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Volvo Trucks
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Navistar
- 17.4 MAN
- 17.5 Mack Trucks
- 17.6 Kenworth
- 17.7 Daimler
- 17.8 Isuzu Motors
- 17.9 Scania AB
- 17.10 Freightliner
- 17.11 PACCAR
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

