
Market Overview:
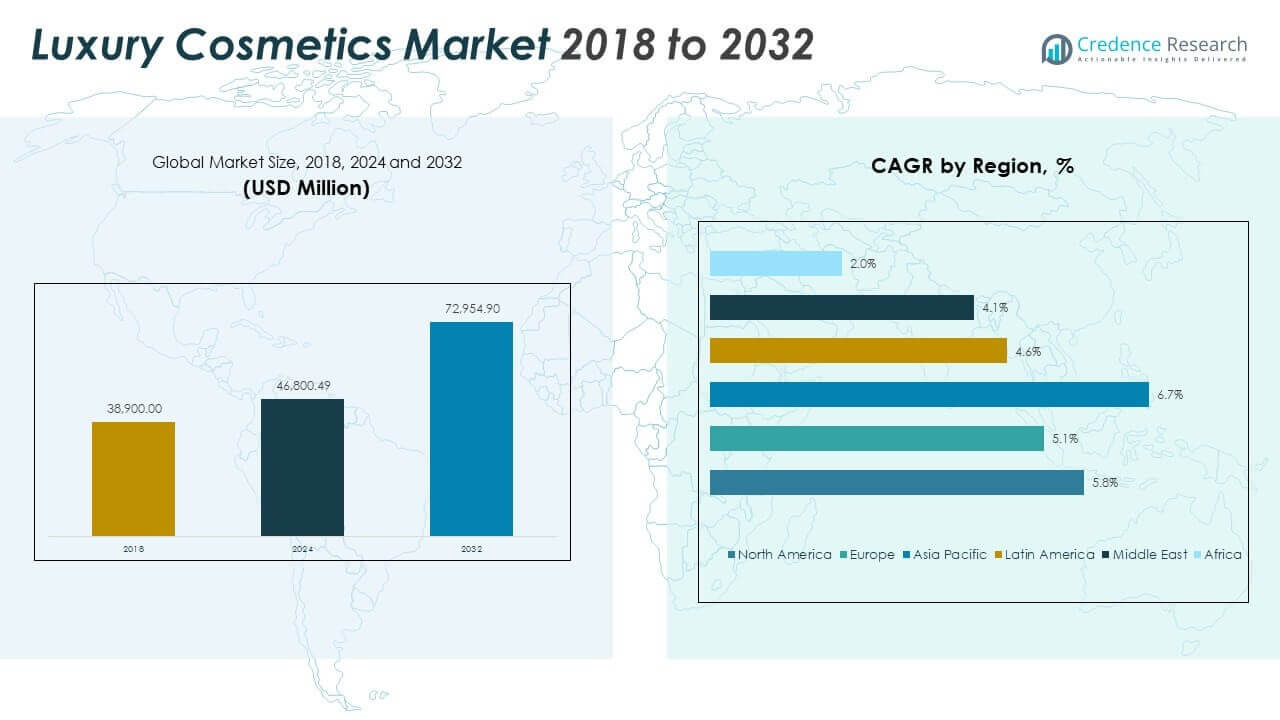
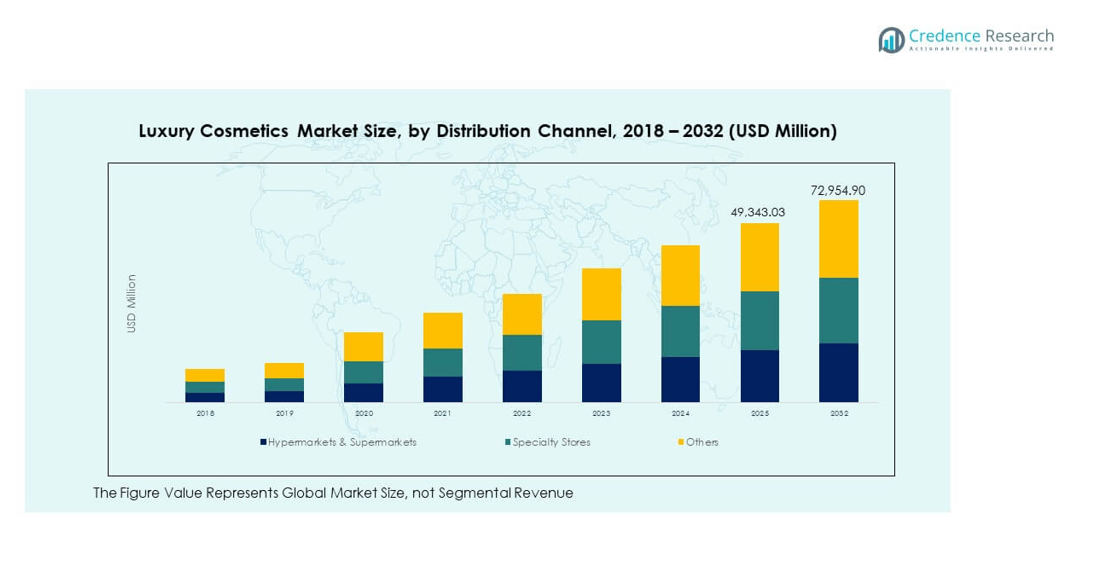
The Global Luxury Cosmetics Market size was valued at USD 38,900.00 million in 2018, reaching USD 46,800.49 million in 2024, and is anticipated to attain USD 72,954.90 million by 2032, registering a CAGR of 5.75% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Luxury Cosmetics Market Size 2024 | USD 46,800.49 million |
| Luxury Cosmetics Market, CAGR | 5.75% |
| Luxury Cosmetics Market Size 2032 | USD 72,954.90 million |
Market growth is driven by rising consumer demand for premium beauty products emphasizing quality, sustainability, and personalization. Increasing disposable income, urbanization, and brand consciousness among young consumers are fueling adoption. Digital platforms and influencer marketing are reshaping purchasing behavior, while innovations in skincare, anti-aging, and eco-friendly formulations are expanding brand portfolios and customer reach across both established and emerging markets.
Regionally, North America and Europe lead the market due to high luxury spending, strong brand presence, and advanced retail infrastructure. Asia-Pacific is emerging rapidly, supported by growing middle-class populations and rising beauty awareness in China, Japan, and South Korea. The Middle East also shows promising potential, driven by premium brand penetration and expanding retail channels.
Market Insights:
- The Global Luxury Cosmetics Market was valued at USD 38,900.00 million in 2018, reached USD 46,800.49 million in 2024, and is projected to attain USD 72,954.90 million by 2032, growing at a CAGR of 5.75% during 2025–2032.
- Asia Pacific (36%), Europe (29%), and North America (26%) together account for over 91% of the total market share, supported by established luxury brands, strong consumer awareness, and robust retail infrastructure.
- Asia Pacific (36%) remains the fastest-growing region, driven by rising middle-class spending, urbanization, and the surge of digital platforms expanding luxury beauty access across China, Japan, and South Korea.
- Specialty stores (42%) dominate distribution due to premium in-store experiences, brand exclusivity, and expert consultations that build consumer trust and loyalty.
- Online stores (33%) continue to gain traction, supported by influencer-led marketing, expanding luxury e-commerce platforms, and increased preference for convenient, contactless purchasing.
Market Drivers:
Rising Consumer Preference for Premium and Personalized Beauty Products
The Global Luxury Cosmetics Market is expanding due to growing consumer inclination toward high-quality and exclusive beauty items. Consumers increasingly associate luxury cosmetics with superior ingredients, unique formulations, and personal expression. Brands are focusing on customization options such as shade-matching and personalized skincare regimes. This individual-focused approach appeals to affluent and younger consumers seeking distinct identities. Premiumization strategies by major players have strengthened brand loyalty and repeat purchases. The trend aligns with the rising disposable income in urban regions. It also supports innovation in product development targeting niche consumer needs.
- For instance, Estée Lauder Companies has implemented generative AI and virtual try-on technologies-using platforms like Microsoft Azure AI Search-to recommend products and provide shoppers with tailored skincare routines, streamlining the process from trend detection to customer delivery. This engine analyzes consumer preferences, delivering individually matched beauty products and enhancing repeat purchases through its AI-powered skin analysis tools.
Growing Influence of Social Media and Digital Marketing Campaigns
Social media platforms are redefining how consumers interact with luxury brands. Influencers and beauty bloggers are shaping opinions through product reviews and tutorials. The Global Luxury Cosmetics Market benefits from visual platforms like Instagram and TikTok, where brands create immersive campaigns. Luxury companies are also adopting live shopping, AR filters, and AI tools for virtual try-ons. These digital innovations enhance user engagement and boost conversion rates. Younger audiences prefer purchasing through online channels due to convenience and transparency. It drives stronger online brand visibility and higher sales. Strategic influencer partnerships are amplifying brand awareness globally.
Expansion of E-Commerce and Omnichannel Retail Networks
The shift toward digital retail has accelerated luxury cosmetics adoption worldwide. Consumers prefer hybrid shopping experiences blending online and in-store interactions. The Global Luxury Cosmetics Market is witnessing strong sales through brand-owned websites and premium e-commerce platforms. Retailers are introducing virtual assistants and loyalty programs to strengthen customer retention. Enhanced delivery networks and exclusive online launches improve accessibility to high-end products. Brands are investing in digital storytelling to maintain a luxury feel online. Department stores and boutiques are also modernizing layouts to create immersive experiences. This integrated retail evolution increases both reach and brand equity.
Rising Awareness of Clean Beauty and Sustainable Ingredients
Sustainability has become a major growth pillar for luxury cosmetic brands. Consumers demand ethically sourced, cruelty-free, and eco-friendly formulations. The Global Luxury Cosmetics Market is responding with biodegradable packaging and plant-based ingredients. Luxury brands emphasize transparency regarding ingredient sourcing and manufacturing practices. Eco-conscious buyers are willing to pay a premium for sustainable products. Major players are integrating circular economy models to minimize waste. Sustainability certifications now influence purchasing decisions more than traditional endorsements. The clean beauty movement is fostering long-term loyalty among environmentally aware consumers.
Market Trends:
Increasing Integration of Technology in Product Development and Retail Experience
Technology is reshaping how luxury cosmetics are formulated, marketed, and sold. The Global Luxury Cosmetics Market embraces AI and data analytics to personalize customer experiences. Smart mirrors, AR tools, and skin diagnostic apps allow consumers to test products virtually. Brands are using predictive analytics to forecast demand and manage inventory efficiently. Biotechnology is also emerging in skincare, enabling active ingredients with proven results. Retail stores incorporate touchless checkout systems and interactive displays to enhance engagement. Technology-driven personalization builds deeper trust with customers. It positions luxury beauty brands at the forefront of digital transformation.
- For instance, Shiseido introduced facial analysis tech that studies nasal skeleton features to forecast future skin concerns and provide preventive care solutions; the company analyzed facial images of 424 women to refine this predictive technology. Shiseido also launched its AI-powered Voyager platform, digitizing over 500,000 data points for customized skincare and integrating touchless skin analyzers at retail locations for advanced diagnostics.
Growing Demand for Gender-Neutral and Inclusive Cosmetic Lines
Consumers are increasingly drawn toward inclusive beauty products that celebrate diversity. The Global Luxury Cosmetics Market is adapting by launching gender-neutral makeup and skincare ranges. Brands now feature models from varied ethnicities, genders, and skin tones in campaigns. This inclusivity aligns with changing social values emphasizing individuality and equality. Product lines are designed to cater to every complexion and identity. Retailers are also redesigning store sections to create a more open and inclusive experience. Celebrity-backed brands have accelerated this shift through targeted marketing and inclusive packaging. It drives a broader customer base and fosters social acceptance.
- For instance, Fenty Beauty by Rihanna launched the Eaze Drop Blur + Smooth Tint Stick in 2023, offering consumers a choice from 25 flexible shades designed for all skin tones, reflecting the brand’s commitment to inclusion as documented by the official Fenty site and product reviews.
Shift Toward Wellness-Focused and Holistic Beauty Products
Luxury consumers are linking beauty with wellness and emotional balance. The Global Luxury Cosmetics Market is evolving to meet the need for stress-relief and self-care products. Skincare and fragrances now include mood-enhancing and therapeutic ingredients. Brands highlight natural actives like adaptogens, botanicals, and probiotics. Consumers prefer multi-benefit products that nourish both skin and mind. Aromatherapy-based cosmetics and spa-inspired skincare ranges are gaining traction. This trend emphasizes preventive care rather than corrective treatment. It blends luxury indulgence with overall well-being.
Rise of Limited-Edition Collections and Collaborative Launches
Exclusivity remains a defining feature of luxury cosmetics. The Global Luxury Cosmetics Market is witnessing a surge in limited-edition releases and cross-industry collaborations. Brands are partnering with designers, artists, and celebrities to create collectible packaging and unique formulations. These collaborations create scarcity-driven excitement and brand prestige. Seasonal launches and themed collections attract collectors and loyal fans. The marketing strategy also supports higher margins through exclusivity. Online preorders and VIP access programs build anticipation before launch. It helps luxury brands sustain market visibility and consumer engagement.
Market Challenges Analysis:
High Product Costs and Counterfeit Market Threats Impacting Brand Integrity
The Global Luxury Cosmetics Market faces persistent challenges from high product pricing and widespread counterfeiting. Premium ingredients, packaging, and branding elevate costs, limiting access for price-sensitive consumers. Unauthorized sellers and fake products undermine brand trust and profit margins. Counterfeits also pose health risks, leading to stricter import and distribution controls. Brands are responding with digital authentication and traceability systems. Rising regulatory requirements further add compliance costs. It pressures smaller players to maintain profitability. Protecting intellectual property and brand image remains a top priority in sustaining growth.
Supply Chain Disruptions and Sustainability Compliance Pressures
The luxury cosmetics sector experiences vulnerability to global supply chain disruptions. The Global Luxury Cosmetics Market depends on rare ingredients and premium packaging sourced internationally. Any geopolitical tension or raw material shortage impacts production timelines. Companies also face pressure to achieve sustainability targets across sourcing and logistics. Balancing eco-friendly goals with performance standards is complex. Stringent environmental policies require redesigning formulations and packaging. Labor shortages and transport delays increase operational expenses. It demands stronger risk management and strategic partnerships to ensure long-term supply reliability.
Market Opportunities:
Expansion into Emerging Economies and Growing Middle-Class Population
The Global Luxury Cosmetics Market holds strong potential in emerging economies with rising income levels. Countries in Asia-Pacific, Latin America, and the Middle East are seeing an increase in beauty awareness and spending power. Consumers aspire to own premium products that reflect social status and self-expression. Urbanization and global brand exposure through e-commerce support this growth. Local partnerships and region-specific marketing can boost accessibility. It creates space for new entrants and international players to strengthen presence. Personalized retail experiences can further enhance brand appeal in these expanding markets.
Innovation in Eco-Friendly Packaging and Smart Cosmetic Technologies
Sustainability and technology are opening new growth frontiers in luxury cosmetics. The Global Luxury Cosmetics Market is moving toward refillable packaging, biodegradable containers, and AI-based skincare. Consumers value innovation that combines beauty with responsibility and convenience. Smart packaging with NFC tags or QR codes ensures authenticity and engagement. Research into bioactive ingredients and nanotechnology enhances product performance. Brands investing in R&D for sustainable luxury will gain a competitive edge. It enables differentiation and reinforces long-term loyalty among conscious consumers.
Market Segmentation Analysis:
By Product Type
The Global Luxury Cosmetics Market is categorized into skin care, hair care, make-up, and others. Skin care holds a dominant share due to rising awareness of premium anti-aging and hydration products. Consumers prioritize long-lasting formulas and natural ingredients that enhance skin health. Hair care is expanding with increased demand for salon-grade shampoos, serums, and scalp treatments. Make-up continues to attract attention through innovative textures, clean formulations, and limited-edition collections. The others category, including fragrances and body care, supports diversified growth through brand-driven exclusivity and seasonal product launches.
- For instance, Dior's Capture Totale Hyalushot Wrinkle Corrector underwent a clinical instrumental test on 30 people, which showed a 45% reduction in the appearance of wrinkles in under four hours. A board-certified dermatologist, Dr. Patricia Ogilvie, has endorsed and explained the science behind the product, which is often misinterpreted as formal, academic peer review.
By End-User
The market serves both female and male consumers, with women representing the largest revenue share. Growing beauty consciousness among men has created strong demand for luxury grooming and skincare lines. Brands are introducing gender-neutral and personalized product ranges to meet evolving consumer preferences. It reflects the shift toward inclusivity and self-expression across all demographics.
- For instance, Chanel did launch its Boy de Chanel makeup line in 2018, expanding it internationally with products including a tinted foundation, concealer, and eyebrow pencils. The line's marketing and intent supported a gender-fluid approach to beauty. However, the line has since been discontinued.
By Distribution Channel
Distribution channels include hypermarkets & supermarkets, specialty stores, online stores, and others. Specialty stores lead due to premium customer service and curated product experiences. Online platforms are rapidly expanding, driven by convenience and social media influence. Hypermarkets offer strong accessibility, while exclusive boutiques and beauty counters strengthen brand prestige. It showcases the balance between physical experience and digital convenience in luxury retail growth.
Segmentation:
By Product Type:
- Skin Care
- Hair Care
- Make-up
- Others
By End-User:
- Female
- Male
By Distribution Channel:
- Hypermarkets & Supermarkets
- Specialty Stores
- Online Stores
- Others
By Region:
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- Italy
- U.K.
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
The North America Global Luxury Cosmetics Market size was valued at USD 10,386.30 million in 2018, reaching USD 12,289.53 million in 2024, and is anticipated to attain USD 19,121.61 million by 2032, registering a CAGR of 5.8% during the forecast period. North America holds around 26% of the global market share, supported by strong consumer spending on premium beauty and skincare products. The region’s high disposable income and established retail infrastructure drive market penetration. U.S. brands lead with innovations in clean beauty, sustainable packaging, and inclusive product lines. Consumers seek high-performance formulations backed by dermatological research. Digital marketing and influencer collaborations strengthen customer engagement. Specialty stores and online platforms have become vital in brand outreach. It continues to witness strong brand competition and product diversification in luxury cosmetics.
Europe
The Europe Global Luxury Cosmetics Market size was valued at USD 12,136.80 million in 2018, reaching USD 14,123.11 million in 2024, and is anticipated to attain USD 20,992.97 million by 2032, recording a CAGR of 5.1% during the forecast period. Europe commands nearly 29% of the market share, led by heritage brands in France, Italy, and the U.K. The region’s strong fashion culture and artisanal expertise enhance its luxury cosmetics leadership. Consumers emphasize authenticity, craftsmanship, and ingredient transparency. Growing adoption of natural and vegan formulations reflects the shift toward ethical luxury. Premium fragrances and skincare remain major growth drivers. Regulatory standards maintain high product quality and consumer confidence. It continues to evolve with sustainability and cruelty-free certifications shaping future innovations.
Asia Pacific
The Asia Pacific Global Luxury Cosmetics Market size was valued at USD 12,681.40 million in 2018, reaching USD 15,764.55 million in 2024, and is projected to reach USD 26,504.57 million by 2032, registering a CAGR of 6.7% during the forecast period. Asia Pacific represents approximately 36% of the global share, making it the fastest-growing region. Expanding middle-class income and rising beauty consciousness fuel demand across China, Japan, South Korea, and India. The market benefits from a blend of global luxury and local K-beauty influences. E-commerce growth and digital engagement through influencers drive brand visibility. Urban consumers prefer skincare solutions targeting pollution and climate-related issues. Local production facilities support affordability and quicker delivery. It remains a strategic hub for global brands aiming for high-volume, sustainable growth.
Latin America
The Latin America Global Luxury Cosmetics Market size was valued at USD 2,022.80 million in 2018, reaching USD 2,405.08 million in 2024, and is forecasted to reach USD 3,419.40 million by 2032, at a CAGR of 4.6% during the forecast period. Latin America holds around 5% of the global share, driven by increasing urbanization and evolving beauty standards. Brazil and Mexico dominate regional consumption, supported by growing demand for premium skincare and make-up. Consumers prefer products suited for tropical climates and diverse skin tones. Retail expansion and influencer marketing contribute to brand exposure. Economic fluctuations and import duties pose pricing challenges. Brands are adapting with localized strategies and sustainable packaging. It continues to show steady momentum through social-driven luxury engagement.
Middle East
The Middle East Global Luxury Cosmetics Market size was valued at USD 1,205.90 million in 2018, reaching USD 1,338.19 million in 2024, and is projected to reach USD 1,831.57 million by 2032, with a CAGR of 4.1% during the forecast period. The region represents nearly 3% of the global share, driven by high-income consumers and cultural emphasis on personal grooming. Countries like the UAE and Saudi Arabia lead with luxury retail expansion and strong demand for perfumes and skincare. The rising number of beauty salons and online luxury stores enhances accessibility. Western and regional brands compete by blending modern aesthetics with cultural preferences. Premium fragrances remain a key growth segment. Travel retail channels also boost brand exposure among international shoppers. It maintains steady growth supported by tourism and lifestyle diversification.
Africa
The Africa Global Luxury Cosmetics Market size was valued at USD 466.80 million in 2018, reaching USD 880.04 million in 2024, and is anticipated to attain USD 1,084.78 million by 2032, growing at a CAGR of 2.0% during the forecast period. Africa contributes roughly 1% of the global market share, with potential in emerging urban centers. South Africa and Egypt are key contributors, leading in skincare and make-up categories. Rising disposable income and increasing social media exposure drive awareness of luxury beauty products. Limited retail infrastructure and high import costs remain major barriers. Local distributors are partnering with global brands to expand presence. Demand for inclusive shade ranges is increasing. It is gradually evolving into a developing market with long-term growth prospects in beauty and lifestyle sectors.
Key Player Analysis:
- L’Oréal S.A.
- Coty Inc.
- Shiseido Company Ltd.
- Estée Lauder Companies
- Puig
- Revlon Inc.
- Kao Corporation
- The Procter & Gamble Company
- Unilever Plc.
- Chanel International B.V.
- Pat McGrath Cosmetics LLC.
Competitive Analysis:
The Global Luxury Cosmetics Market features intense competition driven by innovation, brand prestige, and digital engagement. It includes established multinational corporations such as L’Oréal, Estée Lauder, Shiseido, and Unilever competing with niche luxury brands for market dominance. Companies focus on product differentiation through advanced formulations, sustainability, and exclusive collaborations. Digital platforms and influencer partnerships play a central role in consumer acquisition. Mergers, acquisitions, and portfolio expansions are common to enhance regional reach. It emphasizes long-term brand loyalty and customer experience as key differentiators in sustaining competitive advantage.
Recent Developments:
- In October 2025, L’Oréal S.A. entered a long-term strategic partnership with Kering, acquiring the House of Creed and securing beauty and fragrance licenses for Kering’s luxury houses, including Gucci, Bottega Veneta, and Balenciaga. The €4 billion ($4.7 billion) deal marks L’Oréal's biggest-ever acquisition, positioning Creed and other high-end brands under L’Oréal Luxe, with an exclusive joint venture exploring wellness and longevity experiences.
- In late September 2025, Coty Inc. launched a comprehensive strategic review of its Consumer Beauty business, with plans to integrate its Prestige and Mass Fragrance divisions more closely. This restructuring is aimed at accelerating Coty's growth in fragrance and may include partnerships, divestitures, or spin-offs for brands such as CoverGirl, Rimmel, and Max Factor. Gordon von Bretten was appointed President of Consumer Beauty to lead the transformation.
- Shiseido announced an absorption-type merger with its subsidiary ETWAS Co., Ltd. on July 1, 2025, as part of its strategic objectives to reinforce its brand foundation and operational governance. This move, set forth in Shiseido's 2025-2026 Action Plan, aims to enhance efficiency and profitability for its American and EMEA-origin brands, including NARS and ISSEY MIYAKE PARFUMS.
- Estée Lauder Companies expanded its presence in Mexico’s premium beauty market on October 21, 2025, with a strategic launch of its flagship brand in Amazon’s Premium Beauty online store. This initiative combines elevated brand experience with digital accessibility, aiming to reach consumers in large cities and remote regions.
Report Coverage:
The research report offers an in-depth analysis based on product type, end-user, and distribution channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing focus on clean, vegan, and cruelty-free product development.
- Expansion of luxury beauty retail in emerging economies.
- Integration of AI and AR tools to enhance personalization.
- Rising influence of male grooming and unisex cosmetic lines.
- Growth of eco-luxury brands emphasizing sustainable sourcing.
- Greater collaboration between luxury fashion and beauty labels.
- Enhanced role of e-commerce and social commerce in brand reach.
- Demand surge for wellness-based beauty and hybrid products.
- Investment in localized manufacturing to reduce supply risk.
- Shift toward circular packaging and refillable cosmetic solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Consumer Preference for Premium and Personalized Beauty Products
Affluent and younger consumers are increasingly seeking high-quality, exclusive cosmetics that offer customization and unique formulations. This trend is supported by rising disposable incomes and urbanization, driving demand for luxury brands that provide tailored skincare and make-up solutions.
Growing Influence of Social Media and Digital Marketing Campaigns
Influencer-led marketing and immersive digital campaigns on platforms like Instagram and TikTok are reshaping consumer engagement, boosting brand visibility, and accelerating online sales. Virtual try-ons and live shopping experiences are making luxury cosmetics more accessible and desirable to tech-savvy consumers.
Expansion of E-Commerce and Omnichannel Retail Networks
The integration of online and offline retail channels is enhancing consumer convenience and reach. Luxury brands are investing in premium e-commerce platforms, virtual assistants, and loyalty programs, while specialty stores continue to offer exclusive in-store experiences, together driving overall market growth.
Rising Awareness of Clean Beauty and Sustainable Ingredients
Consumers are increasingly prioritizing ethically sourced, cruelty-free, and eco-friendly luxury cosmetics. Brands responding with sustainable packaging and transparent ingredient sourcing are gaining long-term loyalty from environmentally conscious buyers, further expanding the market.
Increasing Integration of Technology in Product Development and Retail Experience
AI-powered personalization, AR tools for virtual product testing, and smart diagnostic devices are elevating the luxury cosmetics experience. These innovations not only improve customer satisfaction but also differentiate brands in a competitive market, fueling further growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Global Luxury Cosmetics Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Luxury Cosmetics Market projected to grow between 2025 and 2032?
Which Global Luxury Cosmetics Market segment held the largest share in 2024?
What is the major growth driving factors for global Luxury Cosmetics market?
Who are the leading companies in the Global Luxury Cosmetics Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Female
- 1.2.2 Male
- 1.3 By Product Type
- 1.3.1 Skin Care
- 1.3.2 Hair Care
- 1.3.3 Make-up
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 46,800.49 million → 2032: USD 72,954.90 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Luxury Cosmetics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Luxury Cosmetics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Luxury Cosmetics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Luxury Cosmetics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Luxury Cosmetics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Luxury Cosmetics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Luxury Cosmetics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Luxury Cosmetics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 46,800.49 million → 2032: USD 72,954.90 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Luxury Cosmetics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Female
- 12.3.7.2 Male
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Skin Care
- 12.4.7.2 Hair Care
- 12.4.7.3 Make-up
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Luxury Cosmetics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Luxury Cosmetics Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Luxury Cosmetics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Luxury Cosmetics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 L’Oréal S.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Estée Lauder Companies
- 18.4 Shiseido Company Ltd.
- 18.5 Coty Inc.
- 18.6 Chanel International B.V.
- 18.7 Unilever Plc.
- 18.8 Kao Corporation
- 18.9 Puig
- 18.10 Revlon Inc.
- 18.11 Pat McGrath Cosmetics LLC.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

