
Medical Image Exchange System Market Overview:
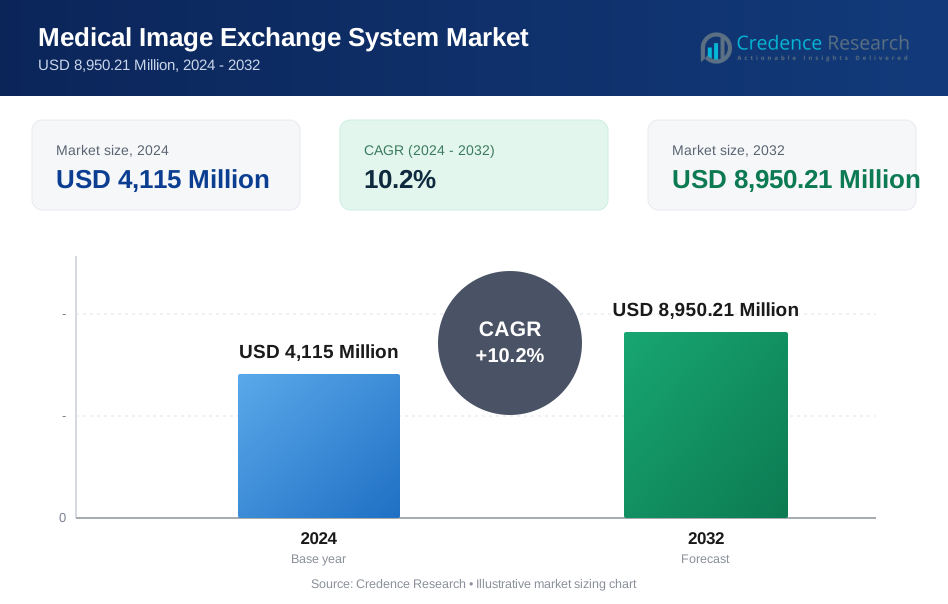
Medical Image Exchange System Market size was valued USD 4,115 Million in 2024 and is anticipated to reach USD 8,950.21 Million by 2032, at a CAGR of 10.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Medical Image Exchange System Market Size 2024 | USD 4,115 million |
| Medical Image Exchange System Market, CAGR | 10.2% |
| Medical Image Exchange System Market Size 2032 | USD 8,950.21 million |
Medical Image Exchange System Market Insights
- Market growth is supported by increasing demand for seamless data exchange, rising diagnostic imaging volumes, and expanding telemedicine services, with the software segment holding a 64.8% share in 2024 due to strong adoption of cloud-based solutions.
- Key trends shaping the market include rapid migration toward SaaS platforms, integration of artificial intelligence for advanced image management, and growing emphasis on real-time image sharing to improve clinical collaboration.
- Market development is restrained by concerns related to data security, patient privacy regulations, and integration complexity with legacy PACS and proprietary imaging systems.
- Regionally, North America led the Medical Image Exchange System Market with a 41.3% share in 2024, followed by Europe at 27.6% and Asia Pacific at 21.9%, while hospitals remained the dominant end users with a 52.6% share.

Medical Image Exchange System Market Segmentation Analysis:
By Solution:
The Medical Image Exchange System Market, by solution, is led by the software segment, which accounted for 64.8% of the total market share in 2024, driven by widespread adoption of cloud-based image exchange platforms, vendor-neutral archives, and interoperability solutions across healthcare networks. Software solutions enable secure image sharing, real-time access, integration with PACS and EHR systems, and compliance with data-protection regulations, making them essential for large-scale deployments. The services segment held 35.2% share, supported by demand for system integration, training, maintenance, and managed services, particularly among hospitals transitioning from legacy infrastructure.
- For instance, Intelerad's InteleShare platform integrates with PACS and EHR systems at St. Luke’s University Health Network, allowing cloud uploads of patient images in under three minutes.
By End User:
By end user, hospitals dominated the Medical Image Exchange System Market with a 52.6% share in 2024, supported by high imaging volumes, multi-departmental data exchange needs, and increasing focus on care coordination and telemedicine. Hospitals prioritize image exchange systems to reduce duplicate imaging, accelerate diagnosis, and improve clinical collaboration. Diagnostic centers followed with a 21.4% share, driven by referral-based image sharing, while laboratories accounted for 13.1%. Clinical research laboratories and educational institutes collectively represented 12.9%, supported by research collaboration and academic training requirements.
- For instance, diagnostic imaging centers utilize platforms like MEDICAI's cloud-based system for instant sharing of X-rays, CT scans, and MRIs with referring physicians, supporting rapid turnaround times for outpatient procedures through zero-footprint DICOM viewers.
Key Growth Drivers
Rising Demand for Interoperable Healthcare IT Systems
The Medical Image Exchange System Market is strongly driven by the growing demand for interoperable healthcare IT infrastructure across hospitals, diagnostic centers, and integrated delivery networks. Healthcare providers increasingly rely on seamless image sharing between PACS, EHRs, and vendor-neutral archives to support coordinated care, reduce diagnostic delays, and eliminate duplicate imaging procedures. Regulatory emphasis on interoperability, data standardization, and cross-institutional information exchange further accelerates adoption. As healthcare systems expand multi-site operations and regional health information exchanges, image exchange platforms become critical for ensuring continuity of care and improving clinical decision-making efficiency.
- For instance, the UK's Sectra Image Exchange Portal (IEP), deployed across 500 NHS and other institutions, enables secure sharing of x-rays, ultrasounds, CTs, MRIs, and PET scans without physical media like CDs.
Growth of Telemedicine and Remote Diagnostics
Rapid expansion of telemedicine and remote diagnostic services is a major growth driver for the Medical Image Exchange System Market. Virtual consultations, teleradiology, and remote specialist reviews require fast, secure access to high-quality medical images across geographies. Image exchange systems enable clinicians to access radiology, cardiology, and pathology images in real time, supporting faster diagnoses and treatment decisions. Increasing reliance on remote care models, especially in rural and underserved regions, continues to elevate demand for scalable image exchange solutions that support cloud access, mobile viewing, and secure data transmission.
- For instance, Philips' solution allows expert imaging technologists to remotely guide colleagues at satellite locations via real-time collaboration during scans.
Increasing Imaging Volumes and Chronic Disease Burden
Rising imaging volumes driven by the growing prevalence of chronic diseases and aging populations significantly fuel the Medical Image Exchange System Market. Conditions such as cardiovascular disorders, cancer, and neurological diseases require frequent imaging for diagnosis, monitoring, and follow-up care. Image exchange systems help manage large datasets efficiently by enabling centralized access, longitudinal image comparison, and cross-provider collaboration. Healthcare providers adopt these systems to improve workflow efficiency, enhance diagnostic accuracy, and reduce operational costs associated with repeated imaging and fragmented data storage.
Key Trends & Opportunities
Shift Toward Cloud-Based and SaaS Image Exchange Platforms
A key trend in the Medical Image Exchange System Market is the accelerating shift toward cloud-based and software-as-a-service image exchange platforms. Healthcare organizations increasingly prefer cloud deployment due to lower upfront costs, faster scalability, and reduced dependency on on-premise infrastructure. Cloud-based systems support real-time collaboration, disaster recovery, and remote access while simplifying system upgrades and maintenance. This trend creates significant opportunities for vendors to offer subscription-based models, advanced analytics, and AI-enabled image management features that enhance diagnostic workflows and operational efficiency.
- For instance, ClinFlows' decidemedical platform leverages OVHcloud's hybrid cloud architecture with dedicated servers and Object Storage to enable secure exchange of DICOM medical images for clinical trials in over 100 countries.
Integration of AI and Advanced Analytics
The integration of artificial intelligence and advanced analytics presents a strong growth opportunity in the Medical Image Exchange System Market. AI-powered tools enhance image indexing, automated routing, anomaly detection, and clinical decision support within exchange platforms. These capabilities improve diagnostic accuracy, reduce clinician workload, and enable faster triaging of critical cases. As healthcare providers increasingly adopt AI-driven imaging solutions, vendors offering intelligent image exchange systems gain a competitive advantage by delivering value beyond basic data transfer and storage.
- For instance, Viz.ai's platform uses over 50 FDA-cleared AI algorithms to analyze CT scans and other medical images in real-time, enabling automated detection of conditions like strokes and automated routing of alerts to care teams across hospital systems.
Key Challenges
Data Security and Privacy Concerns
Data security and patient privacy remain critical challenges in the Medical Image Exchange System Market. Medical images contain sensitive patient information, making them a prime target for cyberattacks and data breaches. Ensuring compliance with data protection regulations, implementing robust encryption, and maintaining secure access controls increase system complexity and cost. Healthcare providers often face difficulties balancing ease of access with stringent security requirements, which can slow adoption, especially among smaller facilities with limited IT resources.
Integration Complexity and Legacy System Compatibility
Integration complexity with existing legacy systems poses a major challenge for the Medical Image Exchange System Market. Many healthcare facilities operate fragmented IT environments with outdated PACS, proprietary imaging formats, and limited interoperability. Integrating modern image exchange platforms with these systems requires extensive customization, workflow redesign, and staff training. This complexity can lead to higher implementation costs and longer deployment timelines, discouraging adoption among budget-constrained healthcare organizations and slowing overall market penetration.
Regional Analysis
North America
North America dominated the Medical Image Exchange System Market with a 41.3% market share in 2024, driven by advanced healthcare IT infrastructure, high imaging volumes, and strong adoption of interoperable solutions across hospitals and diagnostic networks. The presence of large integrated delivery systems and regional health information exchanges accelerates deployment of image-sharing platforms. Regulatory emphasis on interoperability, data security, and value-based care further supports market growth. Widespread adoption of cloud-based solutions and telemedicine services strengthens demand, particularly in the United States, where healthcare providers focus on reducing duplicate imaging and improving care coordination.
Europe
Europe accounted for a 27.6% share of the Medical Image Exchange System Market in 2024, supported by increasing cross-border healthcare initiatives and national digital health strategies. Countries such as Germany, the United Kingdom, France, and the Nordic region emphasize interoperability and standardized data exchange across public healthcare systems. Rising investments in eHealth infrastructure and growing use of vendor-neutral archives drive adoption. The region also benefits from strong data protection frameworks that encourage secure image sharing. Expanding teleconsultation services and collaborative care models across healthcare networks continue to reinforce market expansion.
Asia Pacific
Asia Pacific held a 21.9% market share in 2024, reflecting rapid healthcare digitalization, expanding diagnostic imaging capacity, and rising healthcare expenditures across major economies. Countries including China, Japan, India, and South Korea are investing heavily in hospital IT modernization and cloud-based healthcare platforms. Growing patient volumes, increasing chronic disease prevalence, and the expansion of private diagnostic centers fuel demand for efficient image exchange systems. Government initiatives supporting digital health transformation and telemedicine adoption further accelerate growth, positioning Asia Pacific as the fastest-growing regional market.
Latin America
Latin America represented a 5.4% share of the Medical Image Exchange System Market in 2024, driven by gradual improvements in healthcare infrastructure and increasing adoption of digital imaging technologies. Brazil and Mexico lead regional demand due to expanding private healthcare networks and growing diagnostic service utilization. Healthcare providers increasingly adopt image exchange systems to improve referral efficiency and reduce operational costs. Rising awareness of interoperability benefits and expanding telemedicine programs support market development, although budget constraints and uneven IT maturity continue to limit faster adoption across smaller healthcare facilities.
Middle East & Africa
The Middle East & Africa accounted for a 3.8% market share in 2024, supported by healthcare infrastructure investments and digital transformation initiatives in Gulf Cooperation Council countries. Nations such as Saudi Arabia and the United Arab Emirates focus on smart healthcare systems, centralized data platforms, and advanced diagnostic services. Image exchange systems gain traction in large hospitals and specialty centers to support medical tourism and cross-facility collaboration. In Africa, adoption remains gradual, driven by donor-funded digital health projects and improving access to diagnostic imaging services in urban healthcare settings.
Medical Image Exchange System Market Segmentations:
By Solution
- Software
- Services
By End User
- Hospitals
- Clinical Research Laboratories
- Laboratories
- Diagnostic Centers
- Educational Institutes
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Medical Image Exchange System Market is characterized by the presence of established healthcare IT providers and specialized imaging interoperability vendors, including Koninklijke Philips N.V., GE Healthcare, IBM Corporation, Nuance Communications Inc., Sectra AB, PaxeraHealth, Trice Imaging Inc., eHealth Technologies Inc., IMEXHS, and Vaultara. The market demonstrates moderate to high consolidation, with leading companies focusing on interoperability, cloud-based deployment, and seamless integration with PACS, EHR, and vendor-neutral archive systems. Key players emphasize secure data exchange, scalability, and regulatory compliance to meet evolving healthcare requirements. Strategic partnerships with hospitals, diagnostic networks, and health information exchanges play a critical role in expanding market reach. Companies also invest in AI-enabled workflows, advanced analytics, and subscription-based service models to enhance differentiation, improve clinical efficiency, and strengthen long-term customer relationships.
Key Player Analysis
- Koninklijke Philips N.V.
- PaxeraHealth
- Sectra AB
- Nuance Communications Inc.
- Vaultara
- GE Healthcare (A General Electric Company)
- Trice Imaging Inc.
- IBM Corporation
- IMEXHS
- eHealth Technologies Inc
Recent Developments
- In May 2025, Intelerad announced a strategic partnership with RADPAIR to enhance radiology reporting by integrating generative AI-driven solutions into Intelerad’s medical imaging workflow platforms, aiming to improve reporting efficiency and automation for radiologists.
- In February 2025, SolutionHealth expanded its partnership with Intelerad by naming Intelerad the provider of its imaging solutions, enabling integration of IntelePACS®, InteleOrchestrator™, and InteleArchive™ systems to support reading of ~365,000 imaging studies annually across its healthcare network.
- In October 2025, QT Imaging announced a collaboration with Intelerad to deploy cloud PACS and InteleShare research platforms for clinical connectivity and research data exchange, expanding secure and compliant image sharing across research and clinical sites.
- In November 2025, GE HealthCare announced its agreement to acquire Intelerad, a leading medical imaging software and image exchange platform provider, in a $2.3 billion deal aimed at building a cloud-first, AI-driven imaging ecosystem across care settings (transaction expected to close in the first half of 2026).
Report Coverage
The research report offers an in-depth analysis based on Solution, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Medical Image Exchange System Market will continue to expand as healthcare providers increasingly prioritize interoperability across multi-facility healthcare networks.
- Adoption of cloud-based image exchange platforms will rise, enabling improved scalability, remote accessibility, and operational efficiency.
- Integration of artificial intelligence will strengthen image management, workflow automation, and clinical decision support capabilities.
- Growing reliance on telemedicine and teleradiology will accelerate demand for secure and real-time image sharing solutions.
- Hospitals will remain the primary adopters due to high imaging volumes and strong care coordination requirements.
- Diagnostic centers will increase adoption to streamline referrals and improve turnaround times.
- Regulatory emphasis on data security and patient privacy will drive sustained investment in advanced cybersecurity features.
- Vendor-neutral and standards-based platforms will gain preference over proprietary imaging systems.
- Emerging markets will witness faster adoption supported by healthcare IT modernization and digital health initiatives.
- Strategic partnerships and subscription-based service models will continue to shape long-term market evolution.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Medical Image Exchange System Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Medical Image Exchange System Market projected to grow between 2024 and 2032?
Which Medical Image Exchange System Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Medical Image Exchange System Market?
Who are the leading companies in the Medical Image Exchange System Market?
Which region commanded the largest share of the Medical Image Exchange System Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Medical Image Exchange System Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Medical Image Exchange System Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,115 Million → 2032: USD 8,950.21 Million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Medical Image Exchange System Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Medical Image Exchange System Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Medical Image Exchange System Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Medical Image Exchange System Market Drivers
- 3.3 Medical Image Exchange System Market Restraints & Challenges
- 3.4 Medical Image Exchange System Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Medical Image Exchange System Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Medical Image Exchange System Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Medical Image Exchange System category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Medical Image Exchange System Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Medical Image Exchange System Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Medical Image Exchange System market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Medical Image Exchange System Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Medical Image Exchange System Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Medical Image Exchange System Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Medical Image Exchange System (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Medical Image Exchange System Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Medical Image Exchange System Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Medical Image Exchange System Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Medical Image Exchange System Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Medical Image Exchange System Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Medical Image Exchange System Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Medical Image Exchange System Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Medical Image Exchange System Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Medical Image Exchange System Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
