
Market Overview:
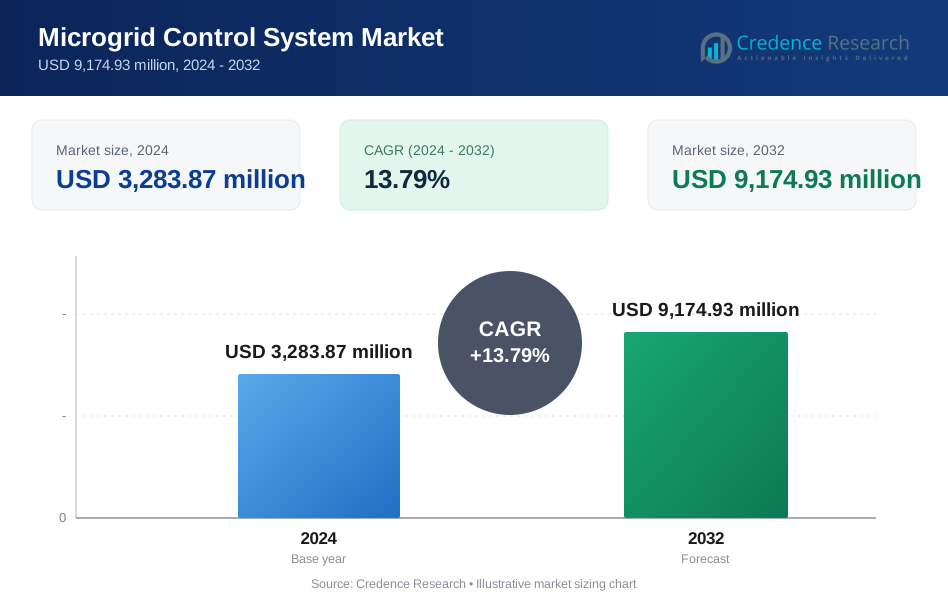
The Global Microgrid Control System Market size was valued at USD 2,100.00 million in 2018 to USD 3,283.87 million in 2024 and is anticipated to reach USD 9,174.93 million by 2032, at a CAGR of 13.79% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Microgrid Control System Market Size 2024 | USD 3,283.87 million |
| Microgrid Control System Market, CAGR | 13.79% |
| Microgrid Control System Market Size 2032 | USD 9,174.93 million |
The market is expanding due to increasing demand for grid resilience, renewable energy integration, and rural electrification. Governments promote decentralized energy infrastructure to enhance reliability and reduce transmission losses. Microgrid deployments grow across military, campus, industrial, and remote applications. Advancements in IoT and smart sensors enable real-time optimization and control. Energy cost savings and emissions reduction goals support adoption. Technological innovation improves system intelligence, automation, and interoperability. Utilities also pilot microgrids to manage peak load and disaster response scenarios. Private investments further accelerate commercial-scale projects.
North America leads the market, supported by policy incentives and widespread microgrid trials across states like California and Alaska. Europe follows, driven by renewable integration and energy security measures. Asia-Pacific shows the fastest growth, especially in India, China, and Southeast Asia, where rural electrification and disaster-resilient infrastructure are key priorities. Africa and Latin America are emerging markets, gaining attention through donor-backed and utility-driven pilot programs.
Market Insights: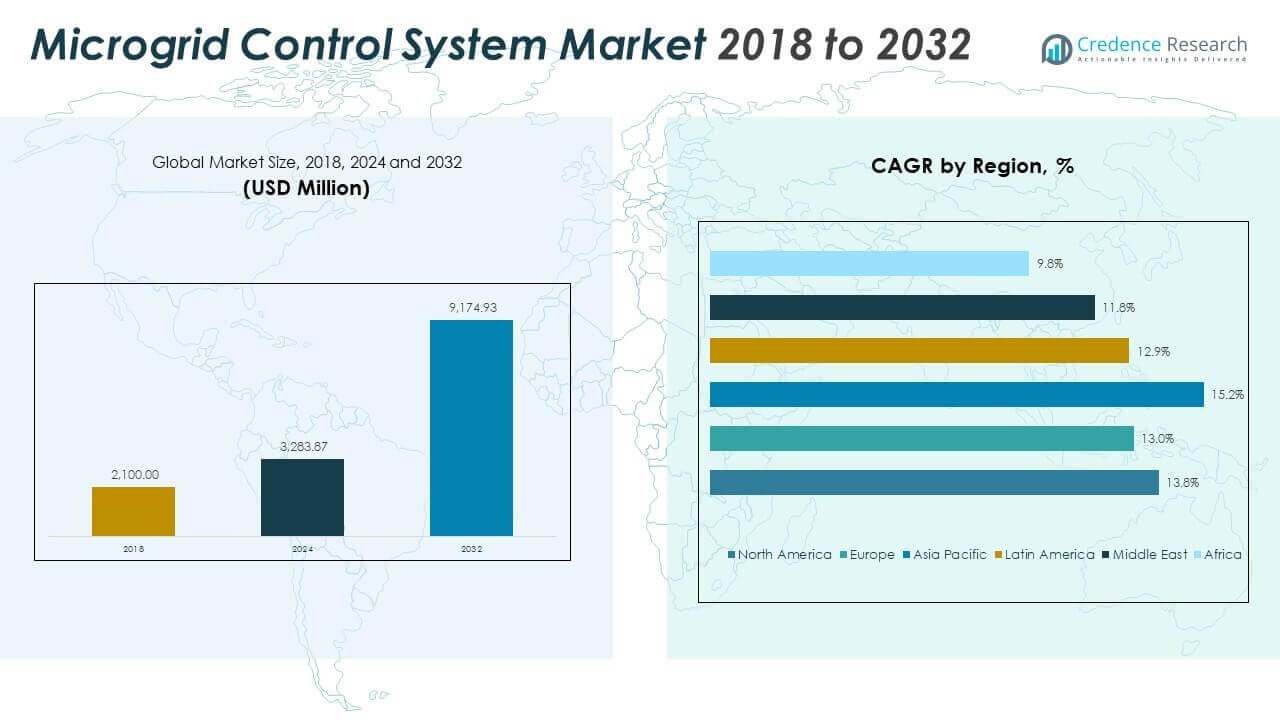
- The Global Microgrid Control System Market was valued at USD 2,100.00 million in 2018, reached USD 3,283.87 million in 2024, and is projected to hit USD 9,174.93 million by 2032, growing at a CAGR of 13.79% during the forecast period.
- North America holds the largest share at 36.3%, driven by strong utility adoption, grid modernization, and resilience needs. Asia Pacific follows with 28.3% due to rural electrification, renewable integration, and fast-paced infrastructure growth. Europe accounts for 24.9%, supported by decarbonization targets and smart city initiatives.
- Asia Pacific is the fastest-growing region with a CAGR of 15.2%, fueled by government-led electrification efforts, industrial automation, and distributed energy programs in China, India, and Southeast Asia.
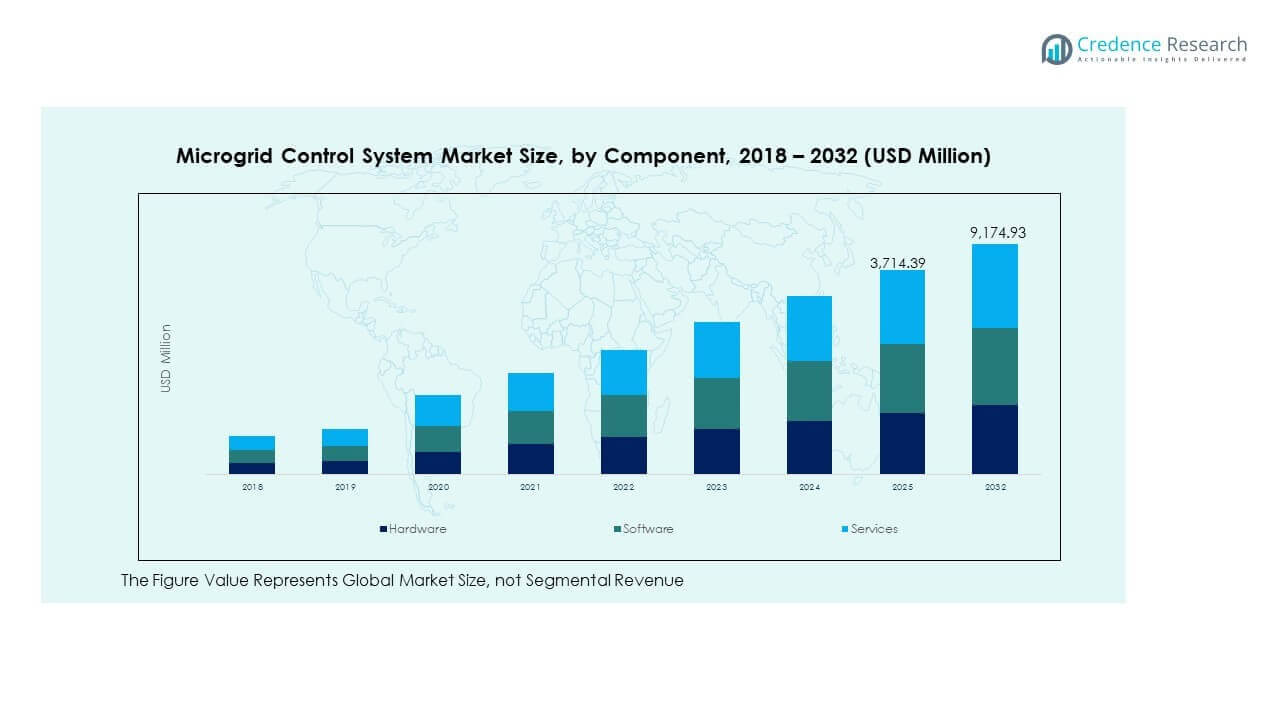
- In 2024, hardware contributed the largest revenue share among components, reflecting demand for control devices, communication units, and power electronics.
- Software is gaining strong traction, showing a rising share in the component mix by 2032 due to growing needs for grid visualization, analytics, and remote management capabilities.
Market Drivers:
Rising Demand for Energy Resilience in Remote and Disaster-Prone Locations
The Global Microgrid Control System Market benefits from rising demand for energy resilience across off-grid and vulnerable areas. Natural disasters often disrupt centralized grids, prompting investments in localized power control. Governments and NGOs prioritize remote electrification, requiring stable, automated microgrid management. Control systems ensure uninterrupted power flow during grid failure or voltage fluctuations. Energy access programs in Southeast Asia and Africa create strong use cases. Defense bases and critical facilities adopt microgrids to improve reliability and autonomy. Island nations prefer microgrid setups to reduce fuel imports. This resilience-oriented shift enhances long-term adoption of control systems.
- For instance, following Hurricane Maria, Schneider Electric deployed microgrid technologies in Puerto Rico, supplying roughly 1,000 hybrid inverters and control systems to improve facility resilience.
Growing Need to Optimize Distributed Renewable Energy Integration
The integration of solar, wind, and biomass systems drives control system adoption. The Global Microgrid Control System Market benefits from rising distributed energy deployments across commercial and community microgrids. Control software synchronizes variable generation with load demand in real time. It supports dynamic load sharing, peak shaving, and battery coordination. Renewable-heavy microgrids need smart dispatch to avoid curtailment and blackouts. Automated control enables predictive maintenance and asset optimization. Developers rely on control platforms to track generation data, grid export, and voltage management. Renewable project scalability aligns with advanced microgrid control features.
- For instance, ABB’s microgrid control platform at the King Island Renewable Energy Integration Project in Australia enabled renewables to supply over 65% of local electricity demand, reducing diesel generator runtime significantly.
Utility-Led Microgrid Pilots and Modernization Projects Support Growth
Utilities are deploying microgrids to reduce peak demand pressure, improve fault tolerance, and modernize legacy networks. Smart microgrid control systems allow real-time power re-routing, substation coordination, and load prioritization. The Global Microgrid Control System Market gains momentum from pilot initiatives in North America and Europe. Utilities implement microgrid projects in rural communities and fire-risk zones. These pilots test grid-interactive features and bidirectional energy flow. Control systems provide granular visibility into grid dynamics. Utilities adopt these platforms to accelerate decarbonization, demand response, and predictive load balancing strategies. System flexibility drives utility interest in smarter grid management.
Cost Savings and Operational Efficiency Drive Commercial Sector Uptake
Commercial campuses and industrial zones adopt microgrids for energy cost savings and operational control. Control systems help reduce peak-time grid usage and optimize internal energy distribution. It aligns load schedules with renewable generation and battery storage cycles. Automated microgrid control reduces downtime and boosts process continuity. Facilities lower energy bills by shifting to self-consumption. Control dashboards support emissions tracking and energy reporting. The Global Microgrid Control System Market benefits from ESG-linked investments in corporate energy autonomy. Commercial users seek long-term energy independence, pushing the demand for intelligent microgrid controllers.
Market Trends:
Advancements in AI and Machine Learning Transform Control Capabilities
AI-based predictive algorithms are reshaping microgrid controller performance. The Global Microgrid Control System Market reflects increasing integration of AI for fault detection, load forecasting, and energy dispatch. Machine learning supports adaptive responses to demand surges and generation drops. Controllers learn from usage patterns to optimize storage cycles. Fault isolation and self-healing become more effective with pattern recognition. AI boosts asset efficiency and minimizes downtime. Control vendors offer cloud-based learning platforms with continuous updates. These smart capabilities are becoming standard across enterprise and utility-scale systems.
- For instance, Siemens Energy reported that its AI-enabled microgrid management software improved load forecast accuracy by over 20% in pilot utility projects, enhancing dispatch efficiency and system reliability. These capabilities are becoming standard at scale.
Cybersecurity Enhancements Emerge as a Key Functional Focus
The digitization of microgrids increases exposure to cyber threats. Market participants strengthen cybersecurity protocols in control platforms. Firewalls, data encryption, and anomaly detection systems are integrated into control modules. The Global Microgrid Control System Market reflects rising demand for NERC CIP-compliant systems. Controllers now feature layered security with remote access tracking. Energy operators invest in breach simulations and recovery testing. Cyber-resilient architecture becomes a key procurement criterion. The need for uninterrupted and secure power flow drives this growing trend.
- For instance, Schweitzer Engineering Laboratories integrated secure-by-design control systems that meet NERC CIP standards and protect thousands of substations globally, with documented zero critical control breaches reported in public utility case studies.
Rise of Plug-And-Play and Modular Control Architectures
Vendors now offer modular and plug-and-play control systems to simplify deployment. Pre-engineered configurations reduce installation time and design cost. The Global Microgrid Control System Market shows rising use of standard communication protocols like IEC 61850. Modular platforms allow flexible system scaling without full redesign. Integrators choose controllers that support easy component expansion. System integrators benefit from reduced commissioning timelines. Off-the-shelf controllers are increasingly popular in remote microgrid projects. Faster deployment cycles encourage broader market participation.
Cloud-Based and Remote Monitoring Capabilities Gain Ground
Cloud-native platforms offer real-time insights and remote command functions. These features support fleet-level microgrid control from centralized dashboards. The Global Microgrid Control System Market sees growing adoption of remote SCADA and IoT integration. Cloud access enhances energy visibility and remote diagnostics. Operators track system status via mobile and web interfaces. Renewable-rich grids rely on cloud support for better intermittency management. Remote control reduces on-site manpower requirements. Cloud functionality is now standard across new controller offerings.
Market Challenges Analysis:
Complex Regulatory and Interconnection Barriers Slow Down Project Execution
The Global Microgrid Control System Market faces delays due to fragmented regulations and inconsistent interconnection policies. Utilities often lack clear frameworks for integrating islanded or semi-autonomous grids. Developers navigate multiple approval layers across states and countries. Interconnection standards differ across jurisdictions, leading to design incompatibility. These inconsistencies affect control system calibration and compliance costs. Projects get stalled due to unclear roles of utility versus private operators. Control vendors must customize systems to meet region-specific codes. Complex licensing, grid-sharing clauses, and cost-recovery models act as structural obstacles. Regulatory streamlining remains slow in emerging regions.
High Upfront Cost of Intelligent Control Systems Limits Adoption in Smaller Projects
Advanced control systems offer high functionality but come with a steep price tag. Small and community microgrids face challenges in justifying the initial investment. The Global Microgrid Control System Market sees uneven uptake due to budget constraints in developing areas. System customization, cybersecurity layers, and integration services add to capital costs. Lack of financing support further restricts adoption. ROI periods stretch when tariffs are low or grid power is subsidized. Many projects opt for basic controllers, limiting optimization benefits. Vendors are developing low-cost, simplified systems to address this pricing gap.
Market Opportunities:
Rapid Electrification and Infrastructure Push in Developing Economies
Emerging markets offer strong growth potential due to rural electrification programs and urban infrastructure expansion. Governments support mini-grid deployments to reduce grid extension costs. The Global Microgrid Control System Market benefits from public-private partnerships in Asia, Africa, and Latin America. Infrastructure stimulus and donor funding support controller installation in schools, hospitals, and community centers. Control vendors can localize offerings for these price-sensitive markets. Scalable, cloud-based systems can be deployed at speed to meet infrastructure demands.
Rising Corporate and Institutional Adoption of Energy-Independent Campuses
Commercial, educational, and healthcare institutions increasingly adopt microgrids to improve energy security. Sustainability goals push organizations to manage renewables and storage onsite. The Global Microgrid Control System Market gains from control systems that enable peak shaving, emissions tracking, and backup management. Private users prefer automated platforms with customizable dashboards. These deployments create repeat demand for controller upgrades and software updates. Vendors targeting large campuses and industrial parks can unlock recurring revenue.
Market Segmentation Analysis:
By Type
Grid-connected systems dominate due to their ability to work in tandem with utility grids, improving load balancing and energy flow control. Off-grid systems serve rural and island communities, supported by renewable integration and battery deployment. Hybrid systems grow steadily, blending both grid-connected and isolated operations. Their flexibility supports backup, load management, and energy cost optimization in both developed and developing economies.
- For instance, Eaton’s hybrid microgrid control deployments at U.S. military bases support seamless transition between grid-connected and islanded modes in under one cycle, according to defense energy program documentation. Type flexibility remains a key differentiator.
By Application
Utilities lead the market by deploying control systems across distributed energy networks for grid stability. Cities and municipalities integrate microgrid controls to manage urban energy demands, especially for EV charging, street lighting, and smart infrastructure. Defense applications prioritize microgrids for mission-critical resilience. Industrial facilities adopt control systems to reduce downtime, manage on-site generation, and optimize energy use. Others include academic institutions, healthcare, and commercial campuses seeking grid independence and efficiency.
- For instance, Honeywell’s microgrid control solution at the University of California San Diego manages over 40 MW of distributed energy assets, supporting campus operations with high reliability and real-time optimization.
By Component
Hardware holds the largest share due to demand for intelligent controllers, sensors, and power converters. Software follows closely, enabling real-time energy analytics, remote monitoring, and grid synchronization. Services grow with demand for system integration, remote maintenance, and lifecycle support. The Global Microgrid Control System Market reflects increasing convergence of hardware and software through IoT-enabled platforms and edge computing solutions.
Segmentation:
By Type
- Grid-Connected
- Off-Grid
- Hybrid
By Application
- Utilities
- Cities and Municipalities
- Defense
- Industrial
- Others
By Component
- Hardware
- Software
- Services
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Microgrid Control System Market size was valued at USD 772.80 million in 2018 to USD 1,194.00 million in 2024 and is anticipated to reach USD 3,331.43 million by 2032, at a CAGR of 13.8% during the forecast period. North America accounts for the highest share of the Global Microgrid Control System Market at approximately 36.3%. It leads due to early adoption of smart grid technologies and government incentives for distributed energy deployment. The U.S. drives most of the demand, backed by large utility pilots, military microgrids, and resilience mandates. States like California and Alaska are investing in autonomous grid controls for fire-prone and remote zones. Canada supports remote microgrids in indigenous and mining communities. Regulatory support and grid modernization programs push adoption further. Vendors in this region offer modular and cybersecurity-focused controllers. The mature infrastructure base supports rapid scaling of software-driven systems.
Europe
The Europe Microgrid Control System Market size was valued at USD 573.30 million in 2018 to USD 862.91 million in 2024 and is anticipated to reach USD 2,282.29 million by 2032, at a CAGR of 13.0% during the forecast period. Europe represents around 24.9% share of the Global Microgrid Control System Market. It benefits from strong energy transition policies and decentralization goals. Germany, France, and the UK lead deployment across renewable-rich regions. The EU Green Deal promotes local energy management and emissions reduction. Microgrid control systems support EV charging infrastructure and flexible demand in smart cities. Rural microgrids in the Nordics and Eastern Europe address energy access challenges. Grid integration of solar and wind energy creates need for intelligent control. Europe shows steady demand for software platforms aligned with EU compliance frameworks.
Asia Pacific
The Asia Pacific Microgrid Control System Market size was valued at USD 516.60 million in 2018 to USD 843.45 million in 2024 and is anticipated to reach USD 2,599.26 million by 2032, at a CAGR of 15.2% during the forecast period. Asia Pacific holds about 28.3% of the Global Microgrid Control System Market and grows at the fastest rate. China and India lead due to rising energy demand, renewable integration, and electrification targets. Southeast Asia scales deployment in islands and rural zones through donor-backed and public programs. Japan and South Korea deploy advanced microgrids in industrial zones and disaster-prone regions. Microgrid control systems help manage variable solar and wind supply. Software platforms support peak load shifting and energy cost optimization. Governments promote local manufacturing and R&D, accelerating market entry. The region favors compact, scalable control solutions for emerging projects.
Latin America
The Latin America Microgrid Control System Market size was valued at USD 151.20 million in 2018 to USD 234.44 million in 2024 and is anticipated to reach USD 613.53 million by 2032, at a CAGR of 12.9% during the forecast period. Latin America captures nearly 6.7% of the Global Microgrid Control System Market. Brazil, Chile, and Argentina drive adoption in mining sites, off-grid communities, and industrial parks. Renewable energy growth supports the need for grid-balancing controls. Governments promote hybrid microgrids in remote areas to lower diesel dependency. Rising electricity demand and grid instability push investments in smarter power distribution. Control systems assist with grid support, blackout prevention, and storage control. Local integrators partner with global vendors to meet regional customization needs. The market sees traction from commercial users seeking energy cost savings.
Middle East
The Middle East Microgrid Control System Market size was valued at USD 60.69 million in 2018 to USD 87.00 million in 2024 and is anticipated to reach USD 211.07 million by 2032, at a CAGR of 11.8% during the forecast period. The Middle East accounts for roughly 2.3% of the Global Microgrid Control System Market. GCC countries lead with microgrid control deployment in smart cities, industrial zones, and energy hubs. Saudi Arabia and the UAE invest in hybrid microgrids for energy diversification. Control systems are critical for integrating solar PV and reducing diesel usage in desert environments. Smart control solutions support real-time monitoring of remote assets. Utilities adopt these systems for better load control and outage response. Vendors target modular controllers for infrastructure and tourism projects. Energy digitalization trends accelerate platform-based control demand in urban developments.
Africa
The Africa Microgrid Control System Market size was valued at USD 25.41 million in 2018 to USD 62.08 million in 2024 and is anticipated to reach USD 137.34 million by 2032, at a CAGR of 9.8% during the forecast period. Africa holds close to 1.5% of the Global Microgrid Control System Market. It grows steadily, driven by rural electrification, energy poverty reduction, and donor-backed infrastructure. Countries like Nigeria, Kenya, and South Africa invest in solar-plus-storage microgrids. Control systems enable off-grid villages to manage generation and load with minimal technical input. NGOs and local utilities focus on plug-and-play control systems for easy deployment. Lack of skilled personnel drives demand for automated, low-maintenance platforms. International development funds support microgrid pilots across East and West Africa. System affordability and local service models shape long-term market success.
Key Player Analysis:
- Schneider Electric (France)
- General Electric (USA)
- ABB (Switzerland)
- Siemens (Germany)
- Eaton (Ireland)
- Schweitzer Engineering Laboratories, Inc. (USA)
- Honeywell International Inc. (USA)
- Caterpillar (USA)
- S&C Electric Company (USA)
- Power Analytics Corporation (USA)
- Cummins Inc. (USA)
- Tesla Energy (USA)
- Emerson Electric Co. (USA)
- Hitachi Energy Ltd. (Switzerland)
- Encorp (USA)
- Enchanted Rock (USA)
- AutoGrid Systems, Inc. (USA)
Competitive Analysis:
The Global Microgrid Control System Market shows moderate to high competition, led by global electrical and automation majors. Large players focus on integrated hardware and software portfolios with strong service capabilities. It benefits from vendors with deep utility relationships and global project experience. Companies compete on system reliability, cybersecurity strength, and grid interoperability. Strategic partnerships with utilities and EPC firms strengthen market reach. Innovation centers on AI-based control, cloud platforms, and modular architecture. Regional players remain active in localized and cost-sensitive projects. Entry barriers remain high due to technical complexity and compliance needs.
Recent Developments:
- Schneider Electric (France) On November 19, 2025, Schneider Electric and Switch signed a $1.9 billion supply capacity agreement. The deal focuses on powering "AI factories" and includes the first U.S. deployment of Schneider's Uniflairchillers and prefabricated power modules.
- ABB (Switzerland) In March 2023, ABB formed a strategic alliance and made a minority investment in Direct Energy Partners (DEP), a US start up advancing DC microgrids through digital technology via its venture capital arm. This partnership accelerates DC microgrid adoption, though no major 2025-2026 updates were identified in recent sources. ABB continues to compete strongly in microgrid controllers alongside peers.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application, Component, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Utilities will expand grid-interactive microgrid deployments to manage demand fluctuations and enhance grid resilience during outages and extreme weather events.
- AI-driven control platforms will gain traction, enabling predictive maintenance, load forecasting, and real-time energy dispatch optimization in diverse microgrid settings.
- Renewable-heavy microgrids will accelerate demand for intelligent controllers that stabilize variable generation and optimize storage, especially in solar- and wind-dominant systems.
- Cybersecure architectures will become mandatory as operators prioritize defense against cyber threats targeting energy infrastructure and grid communication networks.
- Cloud-based monitoring platforms will scale rapidly, supporting centralized control, remote diagnostics, and real-time analytics for multi-site and remote microgrids.
- Industrial users will invest in microgrids to reduce energy costs, ensure continuity in operations, and meet sustainability goals through localized energy generation.
- Rural electrification programs in developing countries will drive adoption of plug-and-play control systems for off-grid and underserved communities.
- Modular and scalable control system designs will become preferred for simplifying integration, reducing deployment time, and lowering engineering costs.
- Software-led business models will expand, offering recurring revenue opportunities through analytics, updates, control-as-a-service, and long-term system optimization.
- Strategic partnerships between technology firms, utilities, and governments will shape market direction, accelerate innovation, and expand reach into emerging economies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Microgrid Control System Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Microgrid Control System Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Global Microgrid Control System Market?
Who are the leading companies in the Global Microgrid Control System Market?
Which region commanded the largest share of the Global Microgrid Control System Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Microgrid Control System Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Microgrid Control System Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,283.87 million → 2032: USD 9,174.93 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Microgrid Control System Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Microgrid Control System Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Microgrid Control System Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Microgrid Control System Market Drivers
- 3.3 Microgrid Control System Market Restraints & Challenges
- 3.4 Microgrid Control System Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Microgrid Control System Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Microgrid Control System Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Microgrid Control System category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Microgrid Control System Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Microgrid Control System Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Microgrid Control System market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Microgrid Control System Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Microgrid Control System Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Microgrid Control System Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Microgrid Control System (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Microgrid Control System Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Microgrid Control System Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Microgrid Control System Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Microgrid Control System Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Microgrid Control System Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Microgrid Control System Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Microgrid Control System Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Microgrid Control System Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Microgrid Control System Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
