
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
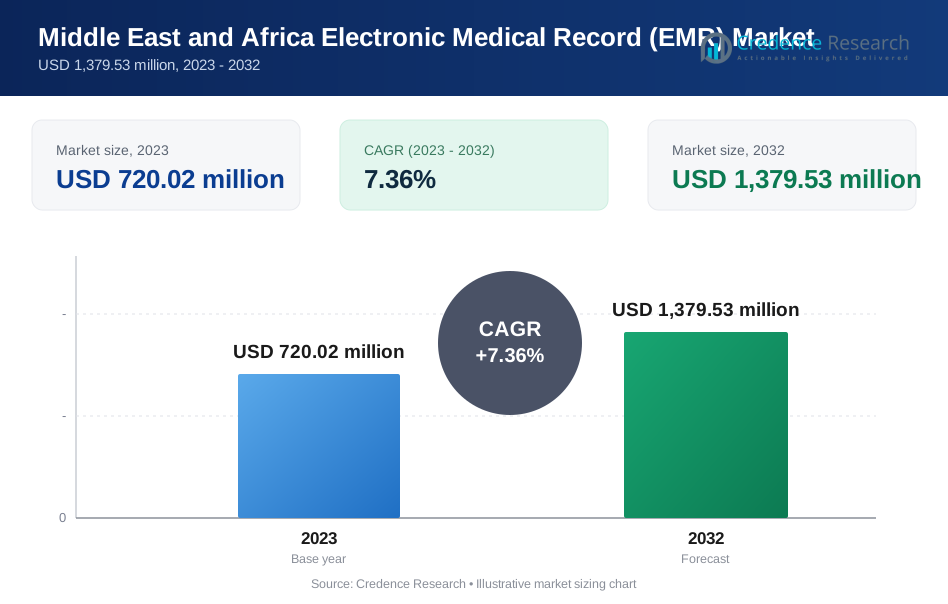
| Middle East and Africa Electronic Medical Record (EMR) Market Size 2023 | USD 720.02 million |
| Middle East and Africa Electronic Medical Record (EMR) Market, CAGR | 7.36% |
| Middle East and Africa Electronic Medical Record (EMR) Market Size 2032 | 1,379.53 million |
Market Overview
The Middle East and Africa Electronic Medical Record (EMR) Market is projected to grow from USD 720.02 million in 2023 to an estimated USD 1,379.53 million by 2032, with a compound annual growth rate (CAGR) of 7.36% from 2024 to 2032. This growth is driven by the increasing adoption of digital healthcare solutions, government initiatives to digitize healthcare systems, and the rising demand for efficient patient management systems across the region.
Key market drivers include the growing focus on improving healthcare infrastructure, the need for integrated healthcare services, and the rising awareness of the benefits of electronic medical records, such as improved patient data accuracy and accessibility. Additionally, advancements in technology and the integration of artificial intelligence in EMR systems are further propelling market growth.
Geographically, the market is dominated by countries like the United Arab Emirates, Saudi Arabia, and South Africa, which have advanced healthcare systems and strong government support for digital healthcare transformation. Key players in the Middle East and Africa EMR market include Cerner Corporation, Allscripts Healthcare Solutions, Inc., Epic Systems Corporation, McKesson Corporation, and MEDITECH. These companies are focusing on expanding their market presence through strategic partnerships and the introduction of innovative EMR solutions tailored to the region's needs.
Market Drivers
Growing Healthcare Digitization Initiatives:
Governments across the Middle East and Africa are increasingly prioritizing the digitization of healthcare systems. This is part of a broader effort to enhance the quality of healthcare services, streamline operations, and ensure better patient outcomes. National policies and strategies, such as Saudi Arabia's Vision 2030 and the UAE's Vision 2021, emphasize the integration of digital technologies in healthcare, including electronic medical records (EMR). For instance, many healthcare organizations in the Middle East and some in Africa have made EMR purchase decisions over the last five years, impacting over 320 hospitals. These initiatives are aimed at creating unified healthcare systems that can seamlessly share patient information across various healthcare providers, thus improving efficiency and reducing errors. The adoption of EMR systems is seen as a critical step towards achieving these goals, driving substantial investment in the sector.
Increasing Demand for Efficient Patient Management:
The healthcare sector in the Middle East and Africa is experiencing a rising demand for efficient patient management systems. This demand is fueled by factors such as the growing population, increasing prevalence of chronic diseases, and a greater focus on patient-centered care. EMR systems play a pivotal role in addressing these needs by providing healthcare providers with comprehensive and accurate patient data, which enhances the quality of care and improves patient outcomes. For example, hospitals account for nearly two-fifths of the total adoption of EMR systems in the region. These systems facilitate better communication among healthcare providers, reduce redundant testing, and ensure that patients receive timely and appropriate care. The shift towards more efficient and effective patient management practices is a significant driver of EMR adoption in the region.
Technological Advancements and Integration of AI:
The EMR market in the Middle East and Africa is benefiting from rapid advancements in technology, particularly in artificial intelligence (AI), machine learning, and cloud computing. These technologies are being integrated into EMR systems to enhance their functionality and usability. AI, for instance, is being used to develop predictive analytics tools that help healthcare providers identify potential health risks and make informed decisions. Machine learning algorithms can analyze large volumes of patient data to identify patterns and trends that may not be immediately apparent to human clinicians. Additionally, the use of cloud-based EMR solutions is gaining traction, offering healthcare providers greater flexibility, scalability, and cost savings. For instance, cloud solutions have been successfully deployed in Saudi Arabia's health clusters, driving high satisfaction among users. These technological advancements are not only improving the efficiency and effectiveness of EMR systems but also making them more accessible to a broader range of healthcare providers across the region.
Supportive Regulatory Environment and Standards:
A supportive regulatory environment is crucial for the widespread adoption of EMR systems. In the Middle East and Africa, governments and regulatory bodies are increasingly recognizing the importance of standardized healthcare information systems. This has led to the establishment of regulations and guidelines aimed at ensuring the interoperability and security of EMR systems. For example, the Health Data Protection Laws in the UAE and Saudi Arabia's Health Sector Transformation Program are focused on protecting patient data and promoting the use of digital health technologies. These regulatory frameworks provide a conducive environment for the adoption and implementation of EMR systems, reassuring healthcare providers and patients about the security and reliability of digital health records. This regulatory support is a key driver of market growth, as it encourages healthcare providers to invest in and transition to EMR systems.
Market Trends
Increased Adoption of Cloud-Based EMR Systems:
One of the most significant trends in the Middle East and Africa EMR market is the growing adoption of cloud-based EMR systems. This shift is driven by the numerous advantages that cloud technology offers, such as reduced upfront costs, scalability, and remote accessibility. Cloud-based EMR systems allow healthcare providers to store and access patient data securely from anywhere, facilitating better coordination and continuity of care, especially in regions with diverse and geographically dispersed populations. Additionally, these systems provide the flexibility to scale up or down based on the healthcare provider's needs, making them particularly attractive to small and medium-sized healthcare facilities that may not have the resources to invest in extensive IT infrastructure. This trend is further supported by the increasing availability of high-speed internet and improved data security measures, which address concerns about data breaches and patient privacy. For instance, the wider use of healthcare information systems and the easier integration and sharing of patient clinical information can facilitate broader access to medical records, improving the correctness and completeness of patient records.
Integration of Artificial Intelligence and Advanced Analytics:
Another prominent trend in the EMR market is the integration of artificial intelligence (AI) and advanced analytics into EMR systems. AI-powered tools are being used to enhance the functionality of EMR systems by enabling predictive analytics, automated data entry, and natural language processing. These advancements help healthcare providers to better analyze patient data, identify potential health risks, and make more informed clinical decisions. For instance, AI algorithms can predict patient outcomes or flag abnormalities in medical records that may require further investigation. Advanced analytics also provide healthcare organizations with valuable insights into patient demographics, treatment outcomes, and resource utilization, which can be used to optimize operational efficiency and improve patient care. The incorporation of AI and analytics is not only enhancing the capabilities of EMR systems but also transforming how healthcare is delivered across the region, making it more proactive and data-driven. This trend underscores the market's evolution towards more intelligent and integrated healthcare solutions. For example, AI-powered hospital EMRs are revolutionizing healthcare services in Africa by improving the quality of care, such as IBM's Watson for Oncology, which assists in diagnosing and treating cancer patients by analyzing patient data and identifying potential treatment options based on evidence-based medical literature and oncology guidelines.
Market Restraints and Challenges
High Implementation Costs and Limited Infrastructure:
A major challenge in the Middle East and Africa EMR market is the high cost associated with the implementation and maintenance of EMR systems. These costs include not only the software and hardware investments but also expenses related to training healthcare staff, customizing systems to meet local requirements, and ongoing support and upgrades. This financial burden can be particularly prohibitive for small and medium-sized healthcare providers, especially in countries with limited healthcare budgets. Additionally, the infrastructure required to support robust EMR systems, such as reliable internet connectivity and adequate data storage facilities, is often lacking in many parts of the region. This limitation hinders the widespread adoption of EMR systems, particularly in rural and underdeveloped areas where healthcare providers may not have access to the necessary technology or resources.
Data Privacy Concerns and Regulatory Challenges:
Data privacy and security concerns present another significant challenge for the adoption of EMR systems in the Middle East and Africa. Patients and healthcare providers alike are wary of the potential risks associated with storing sensitive health information digitally, such as unauthorized access, data breaches, and misuse of personal data. These concerns are exacerbated by varying levels of data protection regulations across the region, which can lead to inconsistencies in how data privacy is managed and enforced. Additionally, the lack of standardized regulations and guidelines for EMR implementation and interoperability creates challenges for healthcare providers attempting to integrate EMR systems with existing healthcare IT infrastructure. Navigating these regulatory challenges requires significant effort and resources, which can be a deterrent for healthcare organizations considering the adoption of EMR systems.
Market Segmentation Analysis
By Product Type
The Hospital EMR segment leads the EMR market, driven by the comprehensive services offered in hospitals that require robust and integrated solutions capable of handling large volumes of data, supporting complex clinical workflows, and facilitating multidisciplinary collaboration. In contrast, Ambulatory EMR systems cater to outpatient settings, including specialized clinics and general physician offices. These systems are streamlined for efficiency, making them easier to implement and maintain, which appeals to smaller healthcare providers. The growing emphasis on outpatient care and chronic disease management further fuels the demand for ambulatory EMR systems, contributing to their expansion in the market.
By Component
The EMR Software segment includes essential systems for managing electronic medical records, featuring modules for patient registration, billing, scheduling, and clinical documentation. Innovations in this area are driven by the demand for advanced features such as analytics, decision support, and interoperability. Complementing this, EMR Services encompass implementation, consulting, training, maintenance, and support, which are critical for the effective deployment and ongoing optimization of EMR systems. As healthcare providers aim to leverage the full potential of EMR technology, the demand for these specialized services is increasing, highlighting their importance in the overall healthcare IT landscape.
Segments
Based on Product Type
- Hospital EMR
- Ambulatory EMR
Based on Component
- EMR Software
- EMR Services
Based on Application
- Client Server Setup EMR
- Hybrid Server Setup EMR
- Cloud-Based EMR
Based on End User
- Hospitals
- Specialized Clinics
- Ambulatory Surgical Centers
- General Physician Clinics
- Others
Based on Region
- Gulf Cooperation Council (GCC) countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Gulf Cooperation Council (GCC) Countries (45%):
The GCC region, comprising Saudi Arabia, the United Arab Emirates, Qatar, Kuwait, Oman, and Bahrain, holds the largest share of the EMR market, accounting for approximately 45% of the market. This dominance is driven by robust healthcare infrastructure, high levels of investment in digital health technologies, and proactive government policies promoting the adoption of electronic medical records. Saudi Arabia and the UAE are the frontrunners, with significant investments in healthcare digitization as part of broader national strategies like Saudi Vision 2030 and UAE Vision 2021. These initiatives aim to enhance healthcare services, improve patient outcomes, and reduce costs through the implementation of advanced EMR systems.
South Africa (20%):
South Africa represents about 20% of the EMR market in the Middle East and Africa region. The country's healthcare sector is relatively advanced compared to other African nations, with a growing emphasis on modernizing healthcare facilities and improving data management practices. The South African government and private sector are increasingly investing in EMR systems to enhance patient care, streamline operations, and comply with evolving data protection regulations. The presence of a well-established IT infrastructure and a skilled workforce further supports the growth of the EMR market in this region.
Key players
- Epic Systems Corp
- Cerner Corp
- Medical Information Technology, Inc.
- NabdaCare
- Pepperl+Fuchs Comtrol, Inc.
- Uplogic Technologies Pvt Ltd
- InterSystems Corporation
- CureMD Healthcare
- Infor-Med-Inc.
- Oracle
- Veradigm LLC
- CareCloud, Inc.
- Agfa-Gevaert Group
- Napier Healthcare Solutions Pte. Ltd.
- Health Catalyst
- Practo Technologies Pvt. Ltd.
Competitive Analysis
The Middle East and Africa EMR market is characterized by a competitive landscape with a mix of established global players and emerging regional companies. Major players like Epic Systems Corp and Cerner Corp lead the market, offering comprehensive and customizable EMR solutions. They are known for their advanced technological features and extensive customer support, which cater to large healthcare institutions. Companies like NabdaCare and Uplogic Technologies Pvt Ltd are gaining traction with innovative, cost-effective solutions tailored to the region's specific needs. These companies leverage local market knowledge and flexible product offerings to compete effectively. The presence of global IT giants like Oracle and regional specialists such as Practo Technologies Pvt. Ltd. further intensifies competition, as they introduce integrated and scalable EMR solutions that appeal to various healthcare providers. This competitive environment drives continuous innovation, improving the quality and accessibility of EMR systems in the region.
Recent Developments
In October 2023, Altera Digital Health, a prominent leader in health IT, announced that its dbMotion Solution achieved the No. 1 ranking on Black Book Research's list for clinical data integration and interoperability solutions. This recognition is based on a comprehensive survey conducted by Black Book among 4,021 health information management users across various medical practices, hospitals, and healthcare organizations. The accolade highlights the solution's effectiveness in seamlessly integrating clinical data, facilitating interoperability, and enhancing healthcare delivery.
In June 2023, Oracle successfully integrated Cerner's electronic health records (EHR) system across Hamad Medical Corporation and Qatar Biobank. This strategic integration marks a significant milestone in advancing scientific research and enhancing healthcare delivery in Qatar. The collaboration aims to improve patient referrals and healthcare services, aligning with Qatar's Vision 2030 to establish a world-class, universally accessible healthcare system. The initiative underscores the commitment to leveraging advanced technology to elevate healthcare standards in the region.
In February 2023, Veradigm LLC's FollowMyHealth was honored as the Most Improved Software Product by KLAS, reflecting substantial improvements in customer satisfaction. This recognition highlights the software's pivotal role in enhancing patient care and experience over the past year. It also underscores Allscripts' dedication to continuous improvement and the significant positive impact FollowMyHealth has had on user satisfaction and healthcare outcomes, solidifying its position as a key player in the healthcare IT market.
In August 2023, WellSky acquired Experience Care, known for its NetSolutions EHR platform, which serves 150 long-term care clients across 850 facilities. This acquisition is expected to enhance efficiency and resident care through the use of data-driven insights provided by the NetSolutions platform. The merger aligns with WellSky's strategic focus on expanding its healthcare solutions portfolio and improving care delivery in long-term care settings, emphasizing its commitment to leveraging technology for better healthcare outcomes.
In July 2023, NextGen Healthcare partnered with the American Podiatric Medical Association (APMA) to introduce exclusive podiatry blueprints within its NextGen Office EHR system. This collaboration addresses a range of foot health issues, including diabetes and dermatitis, by providing specialized solutions tailored to podiatric practices. The initiative empowers small practices by offering tools specifically designed to manage and treat foot health conditions, thereby enhancing the quality of care and supporting specialized medical needs in the community.
Market Concentration and Characteristics
The Middle East and Africa Electronic Medical Record (EMR) Market is characterized by moderate market concentration, with a mix of global and regional players competing for market share. Key characteristics include a growing emphasis on digital health transformation driven by government initiatives and increasing healthcare expenditure. The market is witnessing significant investments in advanced technologies such as cloud-based EMR systems, artificial intelligence, and interoperability solutions. While established global companies like Epic Systems Corp and Cerner Corp hold substantial market shares due to their comprehensive product offerings and established reputations, regional firms are gaining traction by providing cost-effective, localized solutions. The market is also marked by a high degree of customization to meet diverse regulatory and healthcare needs across different countries in the region.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Component, Application, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Cloud-based EMR systems are expected to gain prominence, offering scalability, cost-effectiveness, and ease of access, making them ideal for diverse healthcare settings.
- The integration of artificial intelligence and machine learning into EMR systems will enhance predictive analytics and decision support, improving clinical outcomes and operational efficiency.
- Continued government investments and policy support in digital health infrastructure will accelerate EMR adoption, particularly in emerging markets within the region.
- Efforts to improve interoperability and data integration across healthcare systems will become critical, enabling seamless data exchange and comprehensive patient care.
- The rise of telemedicine and remote care solutions will drive the need for robust EMR systems that support virtual consultations and remote patient monitoring.
- As data privacy concerns grow, there will be significant investments in cybersecurity measures to protect sensitive patient information within EMR systems.
- Vendors will increasingly focus on customizing EMR systems to meet specific regional regulatory requirements and cultural preferences, enhancing user adoption.
- The use of EMR systems in ambulatory settings, including clinics and outpatient facilities, is expected to expand, driven by the need for efficient patient management.
- There will be a rise in specialized EMR solutions catering to niche medical fields, such as oncology and pediatrics, providing tailored functionalities and workflows.
- Strategic partnerships and collaborations among technology providers, healthcare institutions, and governments will be key to developing innovative EMR solutions and expanding market reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Middle East and Africa EMR market?
What are the key drivers of the EMR market in this region?
Which countries dominate the EMR market in the Middle East and Africa?
What challenges does the EMR market face in this region?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Middle East and Africa Electronic Medical Record (EMR) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Middle East and Africa Electronic Medical Record (EMR) Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 720.02 million → 2032: USD 1,379.53 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Middle East and Africa Electronic Medical Record (EMR) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Middle East and Africa Electronic Medical Record (EMR) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Middle East and Africa Electronic Medical Record (EMR) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Middle East and Africa Electronic Medical Record (EMR) Market Drivers
- 3.3 Middle East and Africa Electronic Medical Record (EMR) Market Restraints & Challenges
- 3.4 Middle East and Africa Electronic Medical Record (EMR) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Middle East and Africa Electronic Medical Record (EMR) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Middle East and Africa Electronic Medical Record (EMR) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Middle East and Africa Electronic Medical Record (EMR) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Middle East and Africa Electronic Medical Record (EMR) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Middle East and Africa Electronic Medical Record (EMR) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Middle East and Africa Electronic Medical Record (EMR) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Middle East and Africa Electronic Medical Record (EMR) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Middle East and Africa Electronic Medical Record (EMR) Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Middle East and Africa Electronic Medical Record (EMR) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Middle East and Africa Electronic Medical Record (EMR) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Middle East and Africa Electronic Medical Record (EMR) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Middle East and Africa Electronic Medical Record (EMR) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Middle East and Africa Electronic Medical Record (EMR) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Middle East and Africa Electronic Medical Record (EMR) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Middle East and Africa Electronic Medical Record (EMR) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Middle East and Africa Electronic Medical Record (EMR) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Middle East and Africa Electronic Medical Record (EMR) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Middle East and Africa Electronic Medical Record (EMR) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Middle East and Africa Electronic Medical Record (EMR) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
