
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
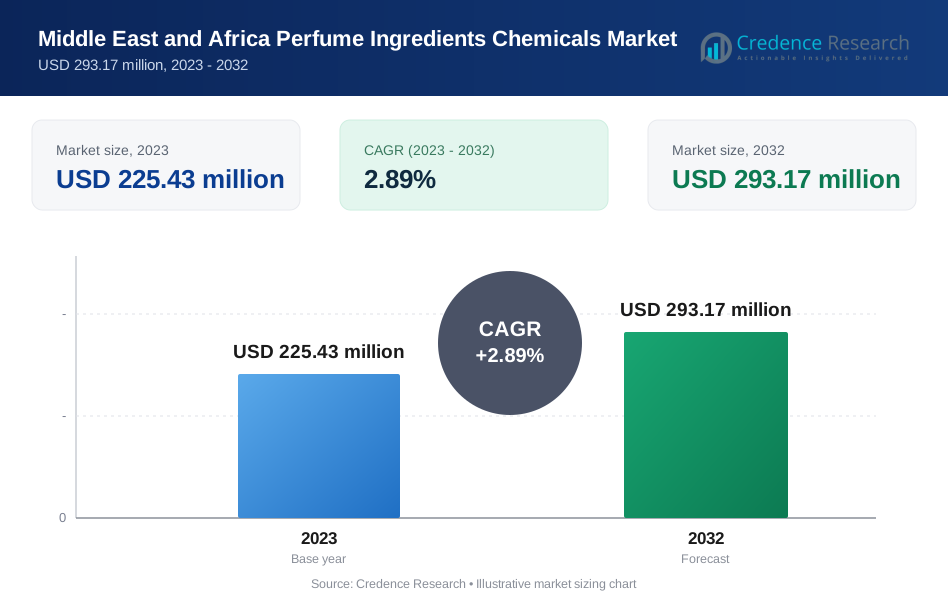
| Middle East and Africa Perfume Ingredients Chemicals Market Size 2023 | USD 225.43 million |
| Middle East and Africa Perfume Ingredients Chemicals Market, CAGR | 2.89% |
| Middle East and Africa Perfume Ingredients Chemicals Market Size 2032 | USD 293.17 million |
Market Overview
The Middle East and Africa Perfume Ingredients Chemicals Market is projected to grow from USD 225.43 million in 2023 to USD 293.17 million by 2032, reflecting a compound annual growth rate (CAGR) of 2.89%.
The Middle East and Africa Perfume Ingredients Chemicals Market is driven by increasing consumer demand for luxury fragrances, rising disposable incomes, and a growing preference for personal grooming products. Key trends include a shift towards natural and organic ingredients, innovations in fragrance formulation, and a surge in niche and personalized perfumes. The market benefits from robust growth in e-commerce and the expansion of retail channels, which enhance product accessibility. Additionally, increasing awareness about sustainable and eco-friendly products is encouraging manufacturers to adopt greener practices, further propelling market growth.
The Middle East and Africa Perfume Ingredients Chemicals Market is geographically diverse, with key markets including the UAE, KSA, Israel, Turkey, Iran, Egypt, Nigeria, Algeria, and Morocco. Major players in the region include Sensient Technologies Corporation, BASF SE, Takasago International Corporation, MANA SE, Robertet SA, Charkit Chemical Company LLC, Henkel AG & Co KGaA ADR, T. Hasegawa USA, and Huabao International Holdings Limited. These companies drive market growth through extensive product portfolios, innovative strategies, and robust distribution networks, catering to the region's demand for both synthetic and natural fragrance ingredients.
Market Drivers
Rising Disposable Income and Evolving Consumer Preferences
In the Middle East and Africa, increasing disposable incomes are driving consumer spending on discretionary items such as fragrances and personal care products. In the Middle East and Africa, the perfume market is experiencing a surge, with disposable incomes rising by 8% annually, leading to a 12% increase in luxury fragrance purchases. For instance, in 2021, the region saw a 20% growth in the sale of niche fragrances, reflecting the economic upturn and the burgeoning interest in high-end personal care. As people have more financial flexibility, there is a noticeable rise in the purchase of luxury and niche fragrances. This economic shift, combined with a growing focus on personal grooming and a desire for unique, distinctive scents, is significantly fueling the demand for a wider variety of perfume ingredients. Consumers are becoming more discerning, seeking out products that reflect their personal style and preferences, thereby expanding the market for diverse and innovative fragrance components.
Trend Towards Natural Ingredients
A key trend shaping the Middle East and Africa Perfume Ingredients Chemicals Market is the increasing consumer preference for natural and organic ingredients. The shift towards natural ingredients is also evident, with a 15% year-over-year increase in the demand for organic perfume components. For example, the sales of perfumes containing natural oud, a highly valued ingredient, have risen by 25% in the last year. This mirrors the global trend where 60% of consumers now prefer natural and organic products over synthetic ones. As awareness about the safety and sustainability of consumer products grows, there is a marked shift towards natural perfume ingredients, which are perceived as healthier and more environmentally friendly. This trend is driven by consumers' concerns over synthetic chemicals and their potential health impacts, as well as a broader societal move towards sustainability and eco-conscious living. Manufacturers are responding to this demand by incorporating more natural elements into their formulations, thereby aligning with consumer expectations and enhancing product appeal.
Personalization
The fragrance industry in the Middle East and Africa is also witnessing a strong trend towards personalization. Personalization is becoming a hallmark of the industry, with 30% of consumers expressing a preference for customized fragrances. In response, companies have invested in innovative technologies, such as AI-driven scent creation, which has seen a 40% uptake by brands seeking to offer unique customer experiences. With a growing desire for customized and unique scents, consumers are increasingly looking for products that cater to their individual tastes and preferences. In response, the industry is developing new technologies and ingredients that enable the creation of bespoke perfumes. This trend towards personalization not only meets consumer demand for uniqueness but also allows brands to differentiate themselves in a competitive market. The ability to offer personalized fragrance experiences is becoming a crucial factor for success in the region's perfume ingredients chemicals market.
Growth of Related Industries
The expansion of related industries such as cosmetics, toiletries, and soap and detergent is also contributing to the growth of the perfume ingredients chemicals market in the Middle East and Africa. As these industries continue to grow, they drive increased demand for high-quality fragrance ingredients to enhance their products. This interdependence highlights the broader economic ecosystem supporting the market, where advancements and growth in one sector positively impact others. The rising production and consumption of cosmetics and personal care products amplify the need for diverse and sophisticated perfume ingredients, thereby stimulating market growth and innovation.
Market Trends
Natural vs. Synthetic
In the Middle East and Africa Perfume Ingredients Chemicals Market, the interplay between natural and synthetic ingredients is a key trend shaping industry dynamics. For instance, while 70% of consumers express a preference for natural ingredients, synthetic aroma chemicals still account for 65% of the market share due to their cost-effectiveness and consistency. The sales of synthetic musk, a popular fragrance base, have seen a steady growth of 5% annually, despite a 10% increase in demand for natural musk alternatives. While there is a notable rise in demand for natural ingredients driven by health-conscious and eco-aware consumers, synthetic aroma chemicals are expected to maintain their dominance in the market. The affordability of synthetic ingredients, coupled with their ability to create specific and consistent scent profiles, ensures their continued prevalence. However, the industry is increasingly focusing on natural alternatives and innovations in sustainable sourcing to cater to the growing segment of consumers who prioritize natural and environmentally friendly products. This dual trend highlights the market's ability to balance consumer preferences for both affordability and sustainability, fostering an environment where both natural and synthetic ingredients can coexist and thrive.
Regional Preferences
The Middle East's rich history with perfumery significantly influences regional preferences, creating a market with a strong inclination towards rich, oriental scents featuring notes like oud, amber, and musk. Regionally, the preference for traditional scents like oud, which has seen a 20% increase in sales, remains strong. However, there’s a noticeable trend among millennials and Gen Z, who make up 40% of the consumer base, towards modern fragrances, leading to a 15% rise in the introduction of new scents in the market. This reflects the region’s evolving fragrance landscape, where the reverence for heritage blends with a zest for contemporary and personalized scent experiences. These traditional fragrances hold a deep cultural significance and continue to be highly favored by consumers in the region. However, there is also an evolving openness to exploring new and trendy fragrances, particularly among younger demographics who seek novel and contemporary scent experiences. This blend of traditional and modern preferences is shaping the market, driving innovation and diversity in fragrance offerings. Companies are leveraging this trend by introducing a variety of products that cater to both time-honored tastes and the adventurous spirit of younger consumers, ensuring broad market appeal.
Market Challenges Analysis
Economic Fluctuations and Fragmented Market
The Middle East and Africa Perfume Ingredients Chemicals Market faces significant challenges due to economic fluctuations and a fragmented market structure. The region's susceptibility to economic booms and busts directly impacts consumer spending on non-essential items like fragrances. During economic downturns, consumers often cut back on luxury purchases, leading to fluctuations in demand for perfume ingredients. This volatility can create an unpredictable market environment, making it difficult for companies to plan long-term strategies and maintain stable growth. Additionally, the market is highly fragmented, with numerous small and medium-sized players competing alongside larger international companies. This fragmentation can hinder smaller companies' ability to achieve economies of scale, limiting their competitiveness and market presence. The intense competition also pressures prices and margins, further complicating the landscape for all market participants. Companies must navigate these economic and structural challenges by developing flexible strategies and leveraging their strengths to remain competitive and resilient.
Stringent Regulations and Infrastructure Challenges
Stringent regulations and infrastructure challenges present further obstacles for the Middle East and Africa Perfume Ingredients Chemicals Market. Regulatory bodies in the region are increasingly introducing stricter safety and environmental regulations for perfume ingredients. While these regulations are essential for ensuring consumer safety and environmental protection, they can significantly increase production costs. Compliance with these standards often requires substantial investments in research, development, and quality control, which can be particularly burdensome for smaller companies with limited resources. Moreover, the uneven development of infrastructure across the region poses logistical challenges for transporting and storing perfume ingredients, especially those that are temperature-sensitive or volatile. Poor infrastructure can lead to delays, increased costs, and potential quality degradation of the products. Companies must invest in robust logistics and supply chain management systems to overcome these hurdles, ensuring efficient and reliable distribution networks. The ability to adapt to regulatory changes and manage infrastructure-related issues effectively will be crucial for companies aiming to succeed in this complex market environment.
Market Segmentation Analysis:
By Product Type:
The Middle East and Africa Perfume Ingredients Chemicals Market is segmented into synthetic aroma chemicals and essential oils by product type. Synthetic aroma chemicals dominate the market due to their affordability, consistency, and ability to create specific scent profiles. Within this category, alcohols, esters, ethers, ketones, and others (such as thiols and dienals) are the primary sub-segments, each contributing uniquely to the diversity and complexity of fragrances. Alcohols are widely used as solvents and carriers in perfume formulations, while esters and ethers add sweet and fruity notes. Ketones provide a variety of scent profiles, enhancing the overall fragrance composition. On the other hand, essential oils, including orange, citronella, peppermint, eucalyptus, and others (like rose and sandalwood), are gaining traction due to the rising demand for natural and eco-friendly ingredients. These oils are valued for their therapeutic properties and rich, complex aromas, catering to the increasing consumer preference for natural products. The balance between synthetic and natural ingredients reflects the market's adaptability to diverse consumer demands.
By Application:
Based on application, the Middle East and Africa Perfume Ingredients Chemicals Market is divided into fine fragrance, home care, laundry care, cosmetics, and others. The fine fragrance segment holds a significant share, driven by the region's rich cultural heritage in perfumery and the high demand for luxury and niche scents. Home care products, including air fresheners and cleaning agents, utilize perfume ingredients to enhance the sensory experience, making this a growing segment. Laundry care products, such as detergents and fabric softeners, also heavily rely on fragrance chemicals to provide fresh and appealing scents, contributing to consumer satisfaction and brand loyalty. The cosmetics segment, encompassing skincare, haircare, and personal care products, benefits from the use of perfume ingredients to enhance product appeal and differentiation. Other applications include industrial and institutional products where fragrance plays a crucial role in masking odors and improving user experience. The diverse application landscape underscores the versatility of perfume ingredients chemicals in meeting varied consumer needs across different sectors.
Segments:
Based on Product Type:
- Synthetic Aroma Chemicals
- Alcohol
- Esters
- Ethers
- Ketone
- Others (Thiols, Dienals, etc.)
- Essential Oils
- Orange
- Citronella
- Peppermint
- Eucalyptus
- Others (Rose, Sandalwood, Orange etc.)
Based on Application:
- Fine Fragrance
- Home Care
- Laundry Care
- Cosmetics
- Others
Based on the Geography:
- UAE
- KSA
- Israel
- Turkey
- Iran
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Middle East and Africa
Regional Analysis
Saudi Arabia and the United Arab Emirates lead the region, accounting for approximately 45% of the market share. These countries benefit from a strong perfume culture and growing tourism industry. Iran and Turkey also show promising growth, with local manufacturers expanding their product lines to meet diverse consumer demands. The Middle Eastern market is characterized by a blend of luxury and mass-market fragrances, with natural ingredients commanding premium prices.
In Africa, the perfume ingredients chemicals market is experiencing steady growth, albeit at a slower pace than the Middle East. South Africa and Nigeria are the key players, collectively representing about 30% of the regional market share. The African market is primarily driven by the rising middle class and increasing urbanization. Natural ingredients sourced locally, such as shea butter and moringa oil, are gaining popularity in both domestic and international markets. However, challenges such as limited infrastructure and regulatory hurdles persist in some African countries, impacting market expansion. Despite these obstacles, multinational companies are investing in the region, recognizing its long-term potential. The trend towards natural and sustainable ingredients is expected to shape the future of the African perfume ingredients chemicals market, with a focus on ethical sourcing and traditional African scents.
Key Player Analysis
- Sensient Technologies Corporation
- BASF SE
- Takasago International Corporation
- MANA SE
- Robertet SA
- Charkit Chemical Company LLC
- Henkel AG & Co KGaA ADR
- Hasegawa USA
- Huabao International Holdings Limited
- Charkit Chemical Company LLC
Competitive Analysis
The Middle East and Africa Perfume Ingredients Chemicals Market is highly competitive, with leading players such as Sensient Technologies Corporation, BASF SE, Takasago International Corporation, MANA SE, Robertet SA, Charkit Chemical Company LLC, Henkel AG & Co KGaA ADR, T. Hasegawa USA, and Huabao International Holdings Limited. Sensient Technologies Corporation stands out with its diverse product portfolio and strong focus on innovation. BASF SE leverages its extensive global network and advanced R&D capabilities to maintain a competitive edge. Takasago International Corporation and Robertet SA are renowned for their expertise in natural and essential oils, catering to the rising demand for eco-friendly ingredients. Charkit Chemical Company LLC and Henkel AG & Co KGaA ADR emphasize strategic partnerships and expansions to enhance market presence. Meanwhile, T. Hasegawa USA and Huabao International Holdings Limited focus on personalized and niche fragrance solutions, addressing the evolving consumer preferences in the region. This competitive landscape drives continuous innovation and market growth.
Recent Developments
- In January 2023, S H Kelkar and Company revealed that its wholly owned subsidiary, Keva Europe B.V. acquired a 100% stake in PFW Aroma Ingredients B.V. (PFW) from Keva UK. The acquisition has strengthened the aroma chemicals business of the company.
- In August 2022, Oriental Aromatics Ltd. announced an investment of nearly INR 1.3 - 1.5 billion (USD 15.69 - 18.10 million) for the development of a hydrogenation plant in Vadodara for specialty aroma chemicals. The plant is expected to be commissioned by the H2 of F.Y. 2024.
- In May 2022, DSM Group, a Dutch company, acquired Firmenich, a Switzerland-based perfume manufacturer.
Market Concentration & Characteristics
The Middle East and Africa Perfume Ingredients Chemicals Market is characterized by moderate to high market concentration, with a few key players dominating the landscape. Major companies such as Sensient Technologies Corporation, BASF SE, and Takasago International Corporation hold significant market shares, leveraging their extensive product portfolios, robust R&D capabilities, and global distribution networks. The market exhibits a blend of both synthetic and natural ingredients, catering to diverse consumer preferences. Characteristics of this market include a strong emphasis on innovation, with companies investing in sustainable and eco-friendly products to meet rising consumer demand. Additionally, the market is influenced by regional preferences for traditional and luxurious fragrances, as well as a growing trend towards personalized and niche scents. The competitive dynamics are shaped by strategic partnerships, acquisitions, and continuous product development, fostering a dynamic and evolving market environment.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Middle East and Africa Perfume Ingredients Chemicals Market is expected to see continued growth due to rising disposable incomes.
- Consumers' increasing preference for natural and eco-friendly ingredients will drive demand for essential oils.
- The market will benefit from advancements in synthetic aroma chemicals, enhancing fragrance variety and consistency.
- E-commerce expansion will boost accessibility and sales of perfume ingredients across the region.
- Regulatory trends towards safety and sustainability will push companies to innovate in compliance with stricter standards.
- Personalization of fragrances will become a significant trend, attracting a younger demographic.
- Market players will focus on strategic partnerships and acquisitions to expand their reach.
- Growth in the cosmetics, toiletries, and home care sectors will positively impact the demand for fragrance chemicals.
- Companies will invest more in sustainable sourcing and ethical production practices to meet consumer expectations.
- Technological advancements in fragrance formulation will lead to the development of new and unique scent profiles.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Middle East and Africa Perfume Ingredients Chemicals Market?
What factors are driving the growth of the Middle East and Africa Perfume Ingredients Chemicals Market?
What are the key segments within the Middle East and Africa Perfume Ingredients Chemicals Market?
What are some challenges faced by the Middle East and Africa Perfume Ingredients Chemicals Market?
Who are the major players in the Middle East and Africa Perfume Ingredients Chemicals Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Middle East and Africa Perfume Ingredients Chemicals Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Middle East and Africa Perfume Ingredients Chemicals Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 225.43 million → 2032: USD 293.17 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Middle East and Africa Perfume Ingredients Chemicals Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Middle East and Africa Perfume Ingredients Chemicals Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Middle East and Africa Perfume Ingredients Chemicals Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Middle East and Africa Perfume Ingredients Chemicals Market Drivers
- 3.3 Middle East and Africa Perfume Ingredients Chemicals Market Restraints & Challenges
- 3.4 Middle East and Africa Perfume Ingredients Chemicals Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Middle East and Africa Perfume Ingredients Chemicals Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Middle East and Africa Perfume Ingredients Chemicals Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Middle East and Africa Perfume Ingredients Chemicals category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Middle East and Africa Perfume Ingredients Chemicals Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Middle East and Africa Perfume Ingredients Chemicals Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Middle East and Africa Perfume Ingredients Chemicals. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Middle East and Africa Perfume Ingredients Chemicals Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Middle East and Africa Perfume Ingredients Chemicals Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Middle East and Africa Perfume Ingredients Chemicals Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Middle East and Africa Perfume Ingredients Chemicals (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Middle East and Africa Perfume Ingredients Chemicals
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Middle East and Africa Perfume Ingredients Chemicals Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Middle East and Africa Perfume Ingredients Chemicals Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Middle East and Africa Perfume Ingredients Chemicals Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Middle East and Africa Perfume Ingredients Chemicals Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Middle East and Africa Perfume Ingredients Chemicals Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Middle East and Africa Perfume Ingredients Chemicals Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Middle East and Africa Perfume Ingredients Chemicals Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Middle East and Africa Perfume Ingredients Chemicals Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
