
Smaller incisions move more surgery to outpatient care
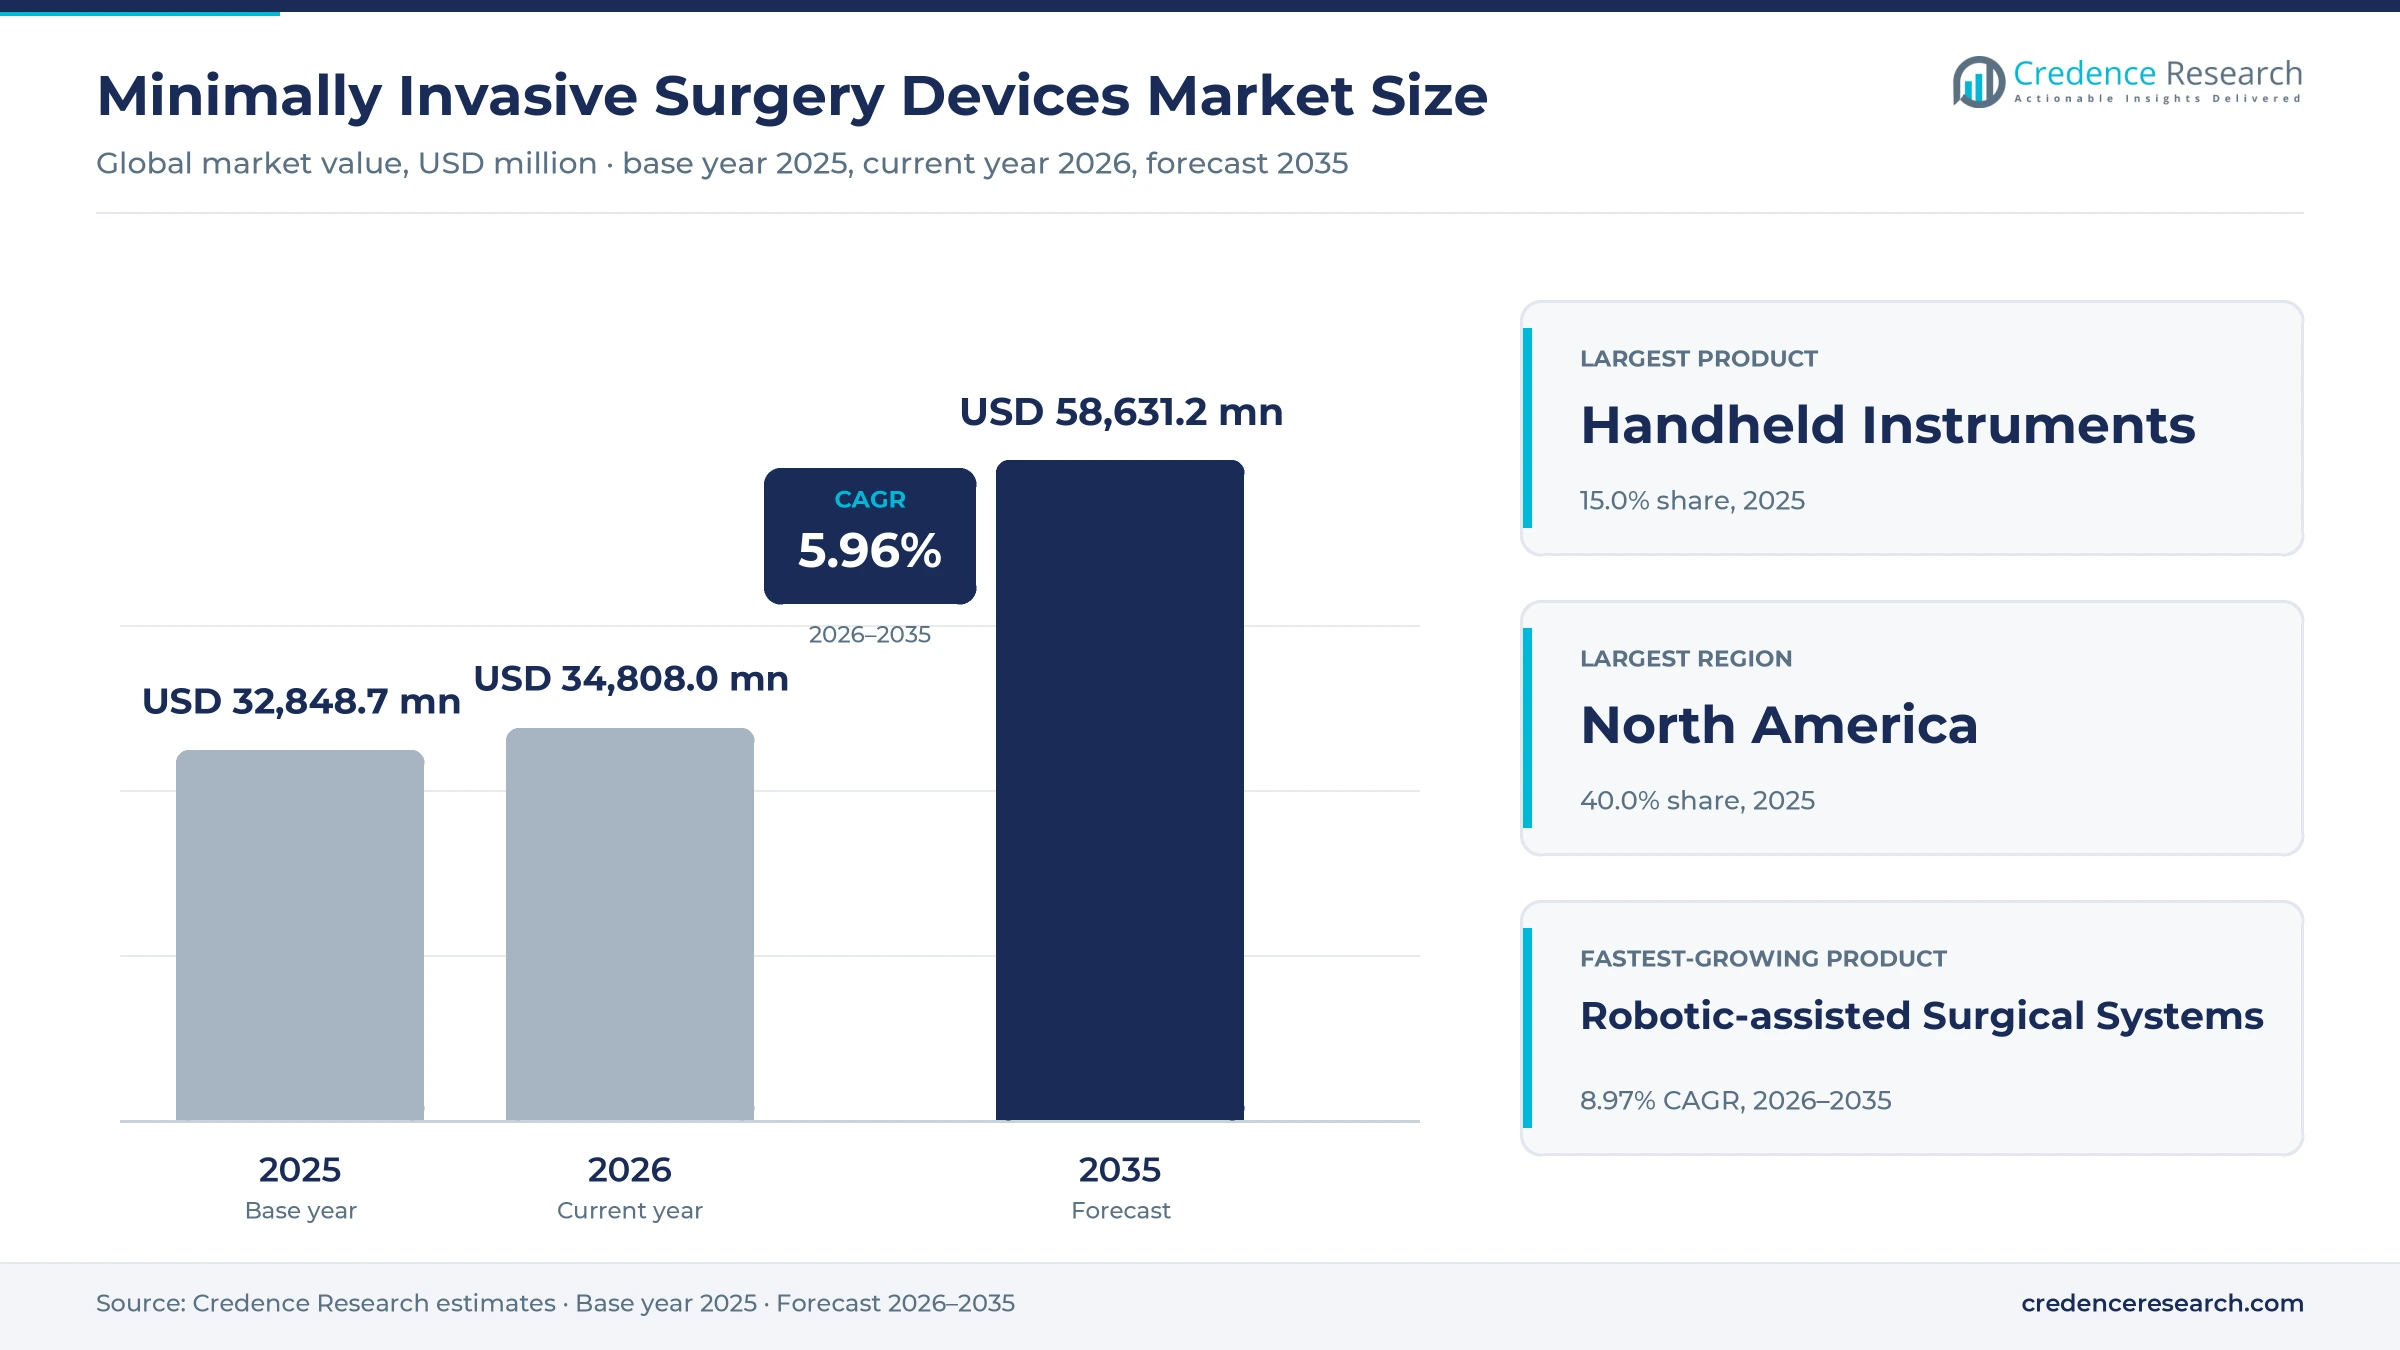
The global minimally invasive surgery devices market was valued at USD 32.85 billion in 2025 and is projected to increase from USD 34.81 billion in 2026 to USD 58.63 billion by 2035, registering a CAGR of 5.96% during 2026–2035. Demand comes from hospitals, ambulatory surgical centers and clinics that replace open procedures with small-incision, catheter-based and endoscopic approaches, because patients recover faster and leave the hospital sooner. North America held the largest regional share, 40.0% in 2025, as high procedure volumes, broad insurance coverage and early adoption of surgical robots support spending. Asia Pacific is the fastest-growing region at 7.22% a year, as China, India and Southeast Asian countries add operating rooms and train more laparoscopic surgeons. The main change is wider competition in robotic platforms, with new systems from established device makers reaching U.S. hospitals in 2024 and 2025.
Which products and procedures count toward market value?
The market counts manufacturer revenue from instruments, energy systems, scopes, visualization equipment, ablation and laser systems and robotic platforms used to operate through small incisions or natural openings. It covers cardiovascular, gastrointestinal, gynecological, orthopedic, urological, neurological and aesthetic procedures. Buyers include hospitals, ambulatory surgical centers and specialty clinics that purchase capital equipment and recurring disposables.
Single-use and reusable instruments account for a steady flow of revenue, because each procedure consumes trocars, staplers, energy tips or catheters. The scope excludes open surgical instruments, implants sold on their own and hospital service fees, and the value chain runs from component suppliers and device makers through distributors to surgical teams.
Minimally Invasive Surgery Devices Market Insights
- The minimally invasive surgery devices market grows from USD 32.85 billion in 2025 to USD 58.63 billion by 2035, a 5.96% CAGR over 2026–2035, as robotics and outpatient surgery expand.
- North America held 40.0% of global value in 2025, supported by high procedure volumes, insurance coverage and a large installed base of surgical robots.
- Handheld instruments led product types with 15.0% of 2025 value, because almost every laparoscopic and endoscopic procedure consumes graspers, scissors and trocars.
- The FDA cleared Intuitive's da Vinci 5 in March 2024 and Medtronic's Hugo system for urologic procedures in December 2025, widening robotic choice.
- Device makers keep buying catheter-based platforms, as Stryker completed its purchase of Inari Medical in February 2025 to enter peripheral vascular care.
Handheld tools, cardiac care and hospitals lead spending
Why do handheld instruments lead while robots grow fastest?
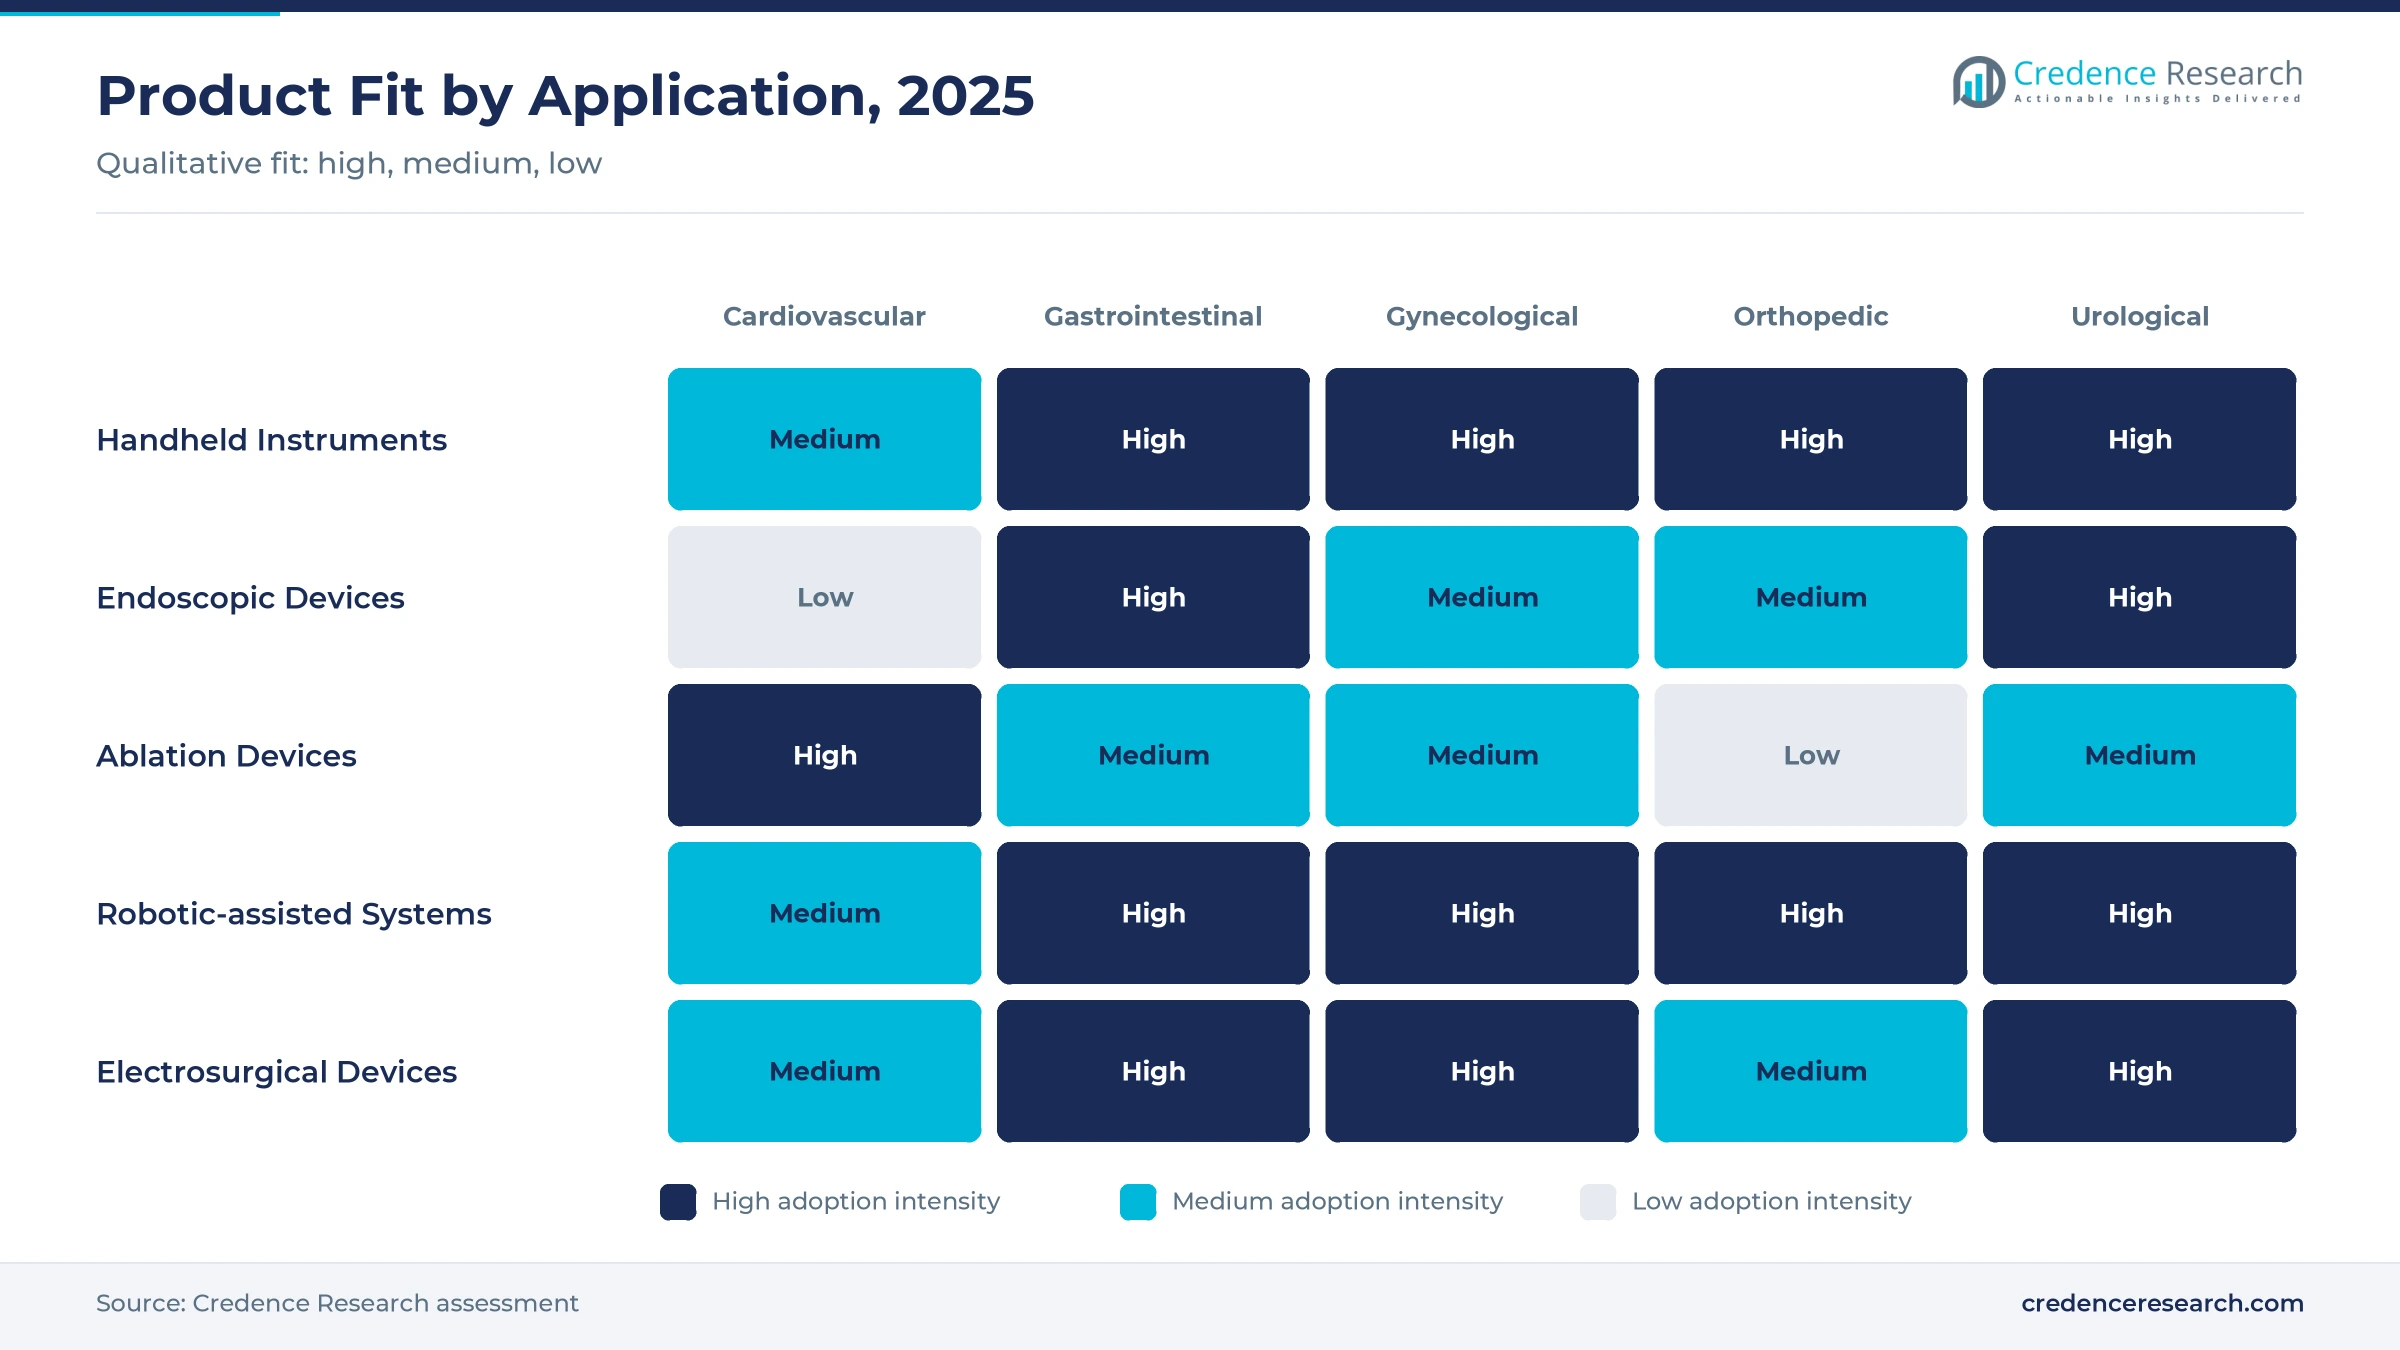
Based on product, the market is categorized into handheld instruments, guiding devices, electrosurgical devices, endoscopic devices, laparoscopic devices, monitoring and visualization devices, ablation devices, laser-based devices, robotic-assisted surgical systems and others. Handheld Instruments led with a 15.0% share of 2025 value, because graspers, dissectors and trocars are used in nearly every procedure. Robotic-assisted Surgical Systems grow fastest at 8.97% a year, as hospitals add consoles and buy instruments for each robotic case.
Why do cardiovascular procedures lead application spending?
Based on application, the market is categorized into aesthetic, cardiovascular, gastrointestinal, gynecological, orthopedic, urological, neurological and other applications. Cardiovascular procedures led with a 24.0% share of 2025 value, because catheter ablation, valve repair and vascular interventions use costly single-use systems. Urological procedures grow fastest at 7.33% a year, as robotic prostatectomy, nephrectomy and cystectomy spread to more hospitals.
Where are these procedures performed?
Based on end user, the market is categorized into hospitals, ASCs, clinics and others. Hospitals led with a 62.0% share of 2025 value, because complex cardiac, cancer and robotic cases need full operating suites and inpatient beds. ASCs grow fastest at 7.63% a year, as payers move more orthopedic, gastrointestinal and urological procedures to lower-cost outpatient settings.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product | Handheld Instruments | 15.0% | Robotic-assisted Surgical Systems | 8.97% |
| By Application | Cardiovascular | 24.0% | Urological | 7.33% |
| By End User | Hospitals | 62.0% | ASCs | 7.63% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Faster recovery, aging patients and new robotic systems
How does faster recovery shift surgeons away from open procedures?
Small-incision procedures usually cause less blood loss, less pain and shorter hospital stays than open surgery, which lowers the total cost of care for hospitals and payers. Patients also return to work sooner, so they increasingly ask for these options when they compare surgeons. As a result, laparoscopic and endoscopic techniques have become the standard approach for gallbladder removal, hernia repair and many colorectal and gynecological operations. This preference keeps instrument demand rising in both mature and emerging health systems, because each of these operations uses several access ports and a set of single-use tools.
Why does an aging population raise procedure volumes?
Older adults need more cardiac, orthopedic, urological and cancer procedures, and they benefit most from approaches that shorten recovery. World Bank data show that people aged 65 and over made up about 29.8% of Japan's population and 17.9% of the U.S. population in 2024. Because older patients often carry several chronic conditions, surgeons favor techniques that reduce trauma and complications. In turn, hospitals in aging countries such as Japan, where the share is 1.7 times the U.S. level, keep expanding capacity for catheter-based and laparoscopic care.
How do new robotic systems widen access to robotic surgery?
Hospitals now have more choice in surgical robots, which supports wider adoption and stronger price competition. In March 2024, Intuitive announced FDA 510(k) clearance for its fifth-generation da Vinci 5 system, which adds optional force feedback instruments. Medtronic then received FDA clearance for its Hugo system for urologic procedures in December 2025. As a result, more hospitals can evaluate surgical robotics programs from several suppliers through 2035.
Why does catheter-based ablation lift cardiovascular spending?
Cardiologists increasingly treat atrial fibrillation through catheters instead of open surgery, which raises demand for mapping systems and single-use ablation catheters. Boston Scientific received FDA approval for its FARAPULSE pulsed field ablation system in January 2024 for drug-refractory paroxysmal atrial fibrillation. Because pulsed field energy targets heart tissue while sparing nearby structures, electrophysiology labs have adopted it quickly. This shift keeps cardiovascular procedures the largest application through 2035.
Robotics, pulsed field ablation and outpatient shifts
Why is competition in surgical robots rising?
The robotic segment is shifting from a near single-supplier field toward several competing platforms, which gives hospitals more negotiating power. Medtronic said its Hugo system is now cleared for prostatectomy, nephrectomy and cystectomy, procedures that account for about 230,000 surgeries a year in the U.S. Johnson & Johnson MedTech completed the first clinical cases with its Ottava system in April 2025 under an FDA investigational device exemption. This rise in choice should lower entry costs for mid-sized hospitals.
How are outpatient centers changing device demand?
Payers and surgeons are moving more joint, spine, hernia and endoscopic procedures from hospitals into ambulatory surgical centers, because outpatient care costs less and frees inpatient beds. These centers prefer compact towers, single-use instruments and fast-turnover energy systems that suit high daily case volumes. As a result, suppliers now design smaller electrosurgical generators and visualization stacks for outpatient rooms. This shift gives ASCs the fastest growth among end users.

Where is the opening in catheter-based vascular care?
Venous and arterial clot removal without drugs is a clear opening, because many patients with blood clots still receive only medication. Stryker completed its acquisition of Inari Medical in February 2025, adding mechanical thrombectomy systems for venous thromboembolism. Because these devices remove clots through small punctures, they suit interventional suites and short hospital stays. Companies with catheter platforms and trained field teams can capture this growth as clinical evidence builds.
Can emerging markets open room for value-priced systems?
Hospitals in India, Southeast Asia, Latin America and Africa want small-incision surgery but cannot always fund premium robots and towers. This gap creates an opening for reusable instruments, refurbished scopes and value-priced robotic platforms with lower per-case costs. Suppliers that pair equipment with surgeon training and local service networks can win public tenders. In turn, wider training programs expand the pool of surgeons who can perform these procedures.
Capital cost, training gaps and quality compliance
How does capital cost slow robot adoption?
Surgical robots require large upfront payments, service contracts and dedicated instruments, which strains budgets at smaller and public hospitals. Many health systems must show higher case volumes before they can justify a second or third console. As a result, adoption remains concentrated in large urban hospitals in North America, Western Europe and East Asia. Suppliers respond with leasing, per-procedure pricing and refurbished systems, although these options still require steady case loads.
Why do training gaps limit procedure growth?
Small-incision and robotic techniques have long learning curves, which means surgeons need simulation time, proctored cases and regular practice to stay proficient. Training capacity is limited in many countries, especially outside large teaching hospitals. These gaps slow the spread of advanced procedures to regional hospitals. In turn, device makers invest in simulators and training centers, although this adds cost to every new platform launch.
How do quality problems disrupt supply?
Manufacturing and reprocessing failures can halt shipments and force hospitals to change suppliers at short notice. In October 2026, the FDA announced an import alert for certain Olympus devices made in Japan, including some ureterorenoscopes, bronchoscopes, laparoscopes and enteroscopes. Because the alert stops future shipments of listed models, buyers must plan replacements and check reprocessing steps. This case shows how quality compliance now shapes purchasing decisions at many hospitals.
Why does reprocessing and infection risk weigh on reusable scopes?
Reusable scopes have narrow channels that are hard to clean, which raises infection concerns when reprocessing steps are missed. Hospitals must invest in staff training, automated reprocessors and tracking systems to meet cleaning standards. This burden pushes some buyers toward single-use endoscopes for selected procedures. However, disposable scopes raise per-case costs and medical waste, so most hospitals still use a mix of both.
U.S. hospitals lead as Asian surgical capacity grows
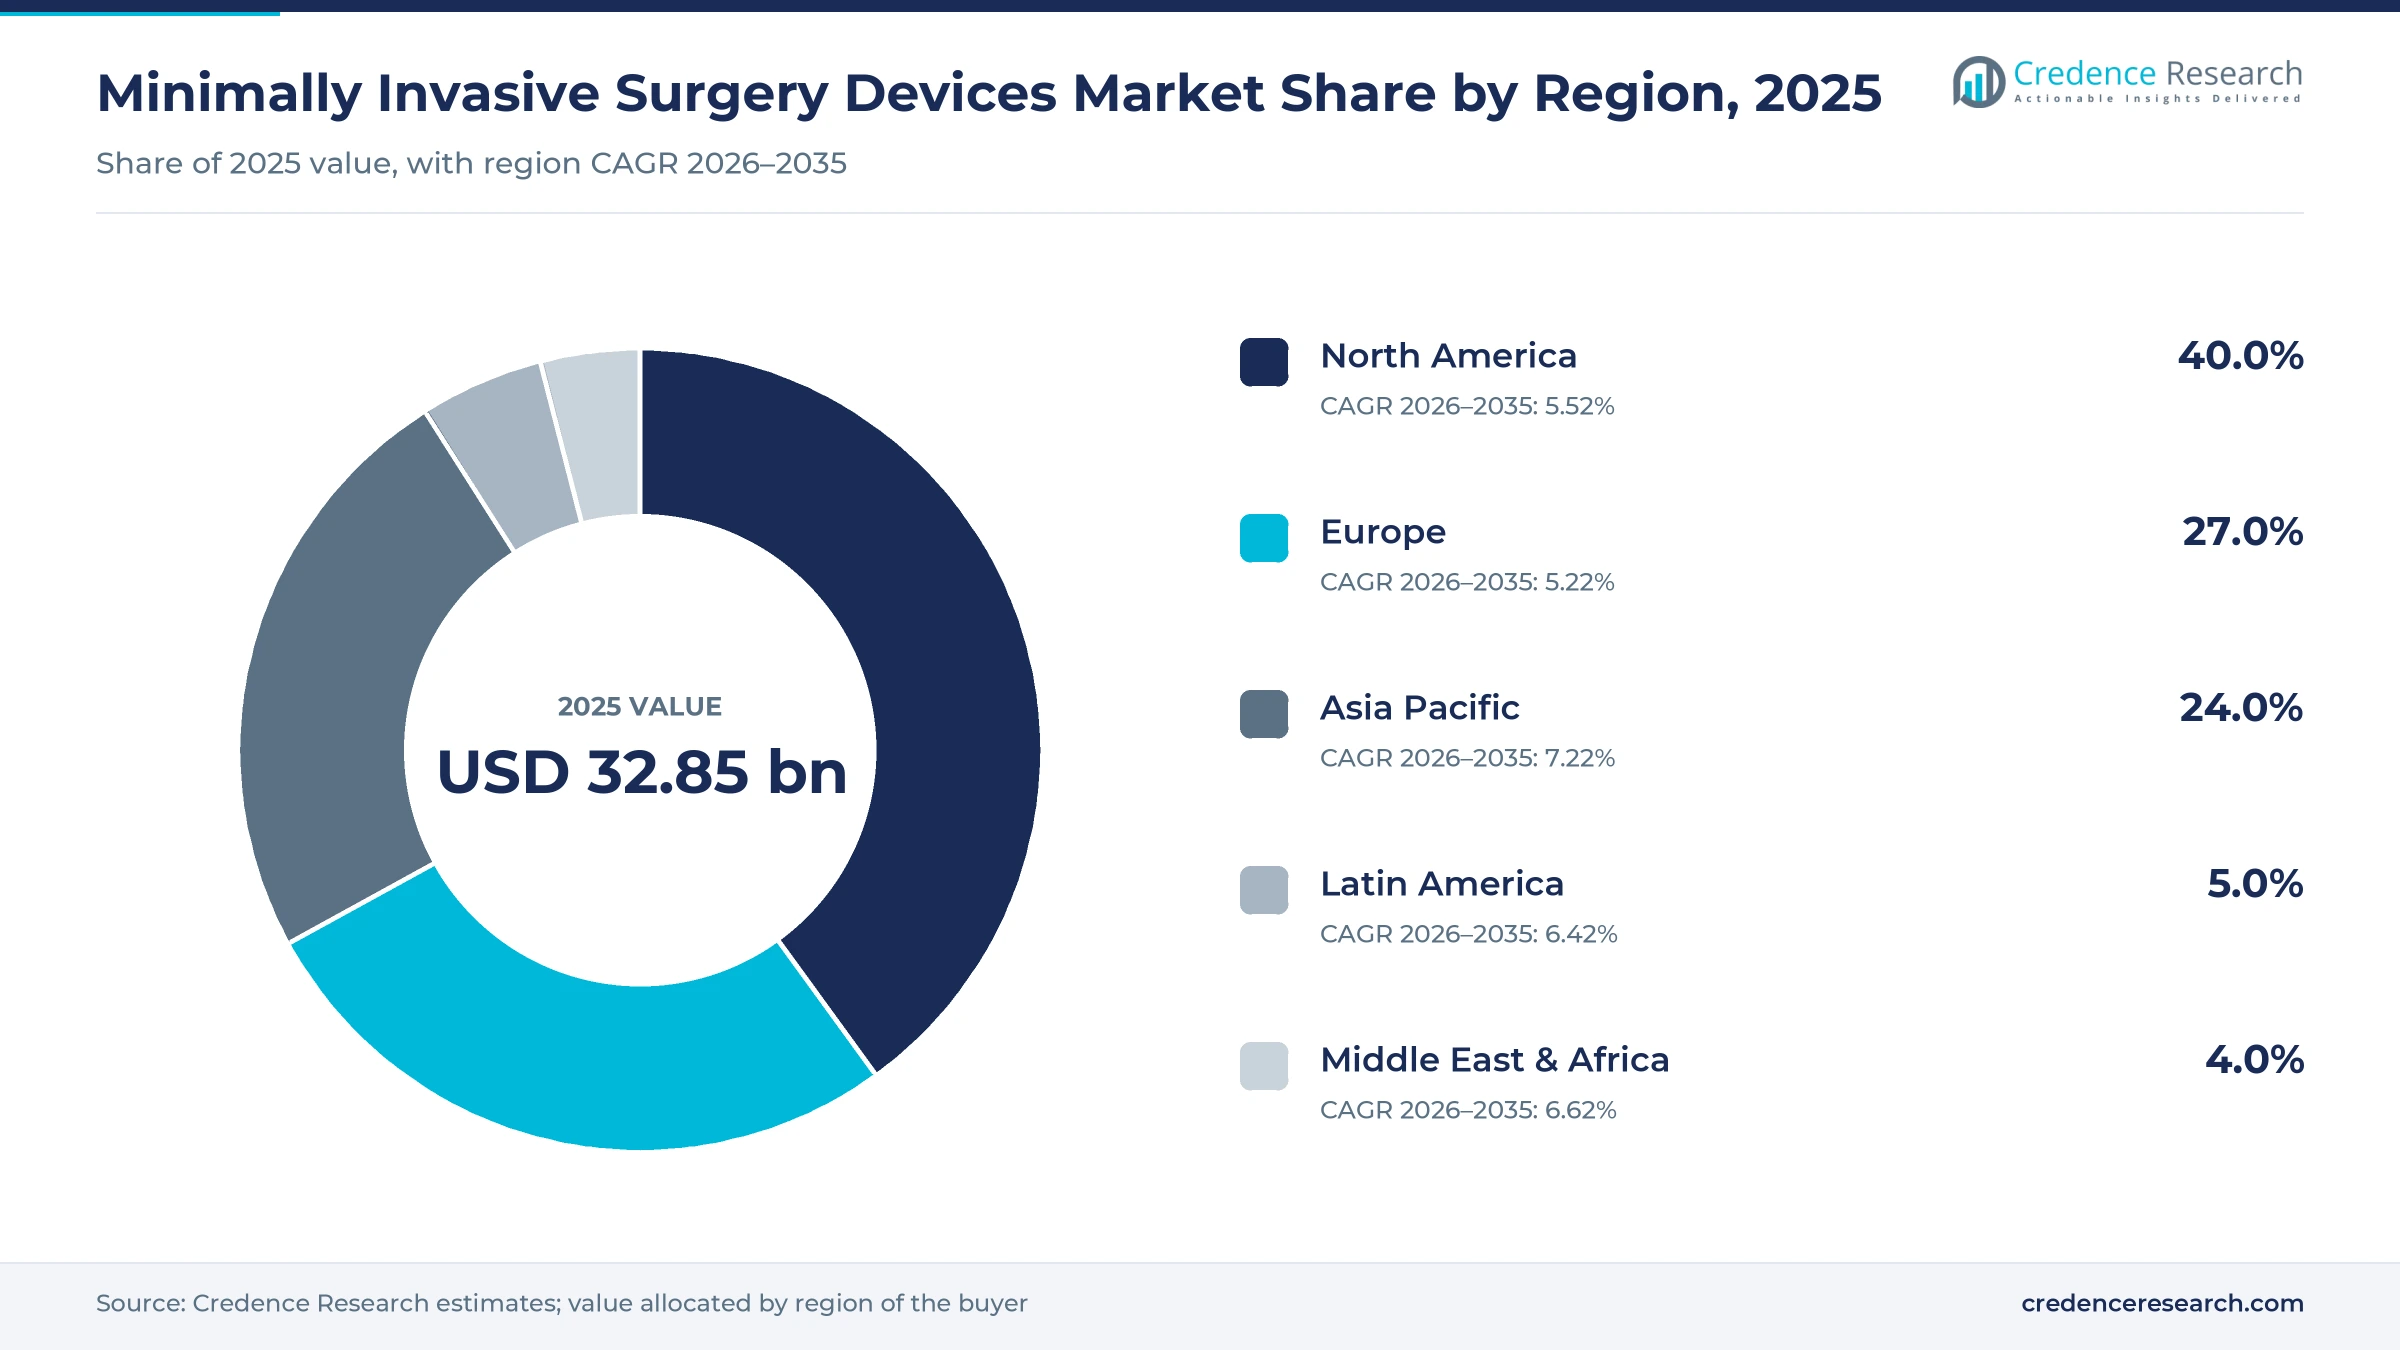
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 13.14 | 40.0% | 5.52% |
| Europe | 8.87 | 27.0% | 5.22% |
| Asia Pacific | 7.88 | 24.0% | 7.22% |
| Latin America | 1.64 | 5.0% | 6.42% |
| Middle East & Africa | 1.31 | 4.0% | 6.62% |
North America leads on robotic installed base
North America held a 40.0% share of 2025 value and grows at 5.52% a year through 2035. The U.S. leads spending, because hospitals run large numbers of robotic, cardiac and laparoscopic procedures under broad insurance coverage. New robotic clearances in 2024 and 2025 widen supplier choice for U.S. hospitals. However, cost controls by payers push more cases into outpatient centers, which favors compact equipment. Medtronic estimates that about 230,000 prostatectomy, nephrectomy and cystectomy procedures take place each year in the U.S., a large base for robotic urology.
Europe balances tenders and outpatient growth
Europe held a 27.0% share of 2025 value and grows at 5.22% a year, the slowest pace among the five regions. Germany, France, Italy, Spain and the U.K. account for most demand, with public hospital groups buying through competitive tenders. As a result, suppliers compete on price per procedure, while day-case surgery programs lift demand for compact laparoscopic towers. Germany also has one of the oldest populations in the region, with 23.2% of residents aged 65 and over in 2024.

Asia Pacific grows on new operating rooms
Asia Pacific held a 24.0% share of 2025 value and is the fastest-growing region at 7.22% a year. China and India are adding hospitals and training more laparoscopic surgeons, while Japan and South Korea have high robotic adoption. Local manufacturers in China compete on price for instruments and robots. In turn, global suppliers focus on premium platforms and training partnerships. China had 14.7% of its population aged 65 and over in 2024, which points to rising cardiac, orthopedic and cancer surgery demand.
Latin America relies on private hospital groups
Latin America held a 5.0% share of 2025 value and grows at 6.42% a year through 2035. Brazil and Mexico account for most demand, where private hospital groups buy robots and towers for urban centers. Currency swings and public budget limits slow equipment purchases in many countries.
Middle East and Africa invest in flagship hospitals
The Middle East & Africa held a 4.0% share of 2025 value and grows at 6.62% a year. Gulf states invest in robotic programs at flagship public and private hospitals. In much of Africa, limited surgeon training and equipment budgets keep adoption low outside large cities.
Robotic clearances and device deals from 2024 to 2026
| Development | Status and market relevance |
|---|---|
| In January 2024, Boston Scientific received FDA approval for the FARAPULSE pulsed field ablation system. | Approved. Treats drug-refractory paroxysmal atrial fibrillation through a catheter. |
| In March 2024, Intuitive announced FDA 510(k) clearance for the da Vinci 5 robotic system. | Cleared. Adds optional force feedback instruments. |
| In February 2025, Stryker completed its acquisition of Inari Medical. | Completed. Adds clot removal systems for venous thromboembolism. |
| In December 2025, Medtronic received FDA clearance for the Hugo system for urologic procedures. | Cleared. Covers prostatectomy, nephrectomy and cystectomy. |
| In October 2026, the FDA announced an import alert for certain Olympus scopes and devices made in Japan. | In force. Blocks future U.S. shipments of listed models. |
Force feedback and better imaging raise precision
- Force feedback instruments on the da Vinci 5 let surgeons sense tissue pressure, and preclinical tests showed up to 43% less force on tissue.
- Pulsed field ablation uses short electrical pulses to isolate heart tissue through ablation catheters with less heat damage.
- Modular robotic arms such as those on the Hugo system can be positioned around the patient to suit different operating rooms.
- High-definition and 3D visualization give surgeons clearer views of anatomy through small ports and natural openings.
- Mechanical thrombectomy catheters remove blood clots from veins without the use of clot-dissolving drugs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Robot makers and instrument suppliers fight for share
Competition in minimally invasive surgery devices rests on installed robotic and visualization systems, broad instrument portfolios and surgeon training. Intuitive Surgical leads robotic surgery with a large installed base of da Vinci systems, while Medtronic and Johnson & Johnson (Ethicon) compete with new robots, staplers and energy devices. Boston Scientific focuses on catheter-based cardiology, urology and endoscopy, and Stryker builds on orthopedic robotics and vascular devices. Olympus and HOYA Corporation supply flexible and rigid scopes, while Koninklijke Philips N.V. offers image-guided therapy systems. Zimmer Biomet, Smith & Nephew and CONMED compete in orthopedic and arthroscopic tools, and Renishaw supplies neurosurgical robotics. Because hospitals rarely switch platforms, suppliers win share through new systems, training and acquisitions.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Intuitive Surgical Inc. | Robotics leader | da Vinci systems, including the da Vinci 5 cleared in 2024 |
| Medtronic | Diversified medical technology | Hugo robotic system, energy devices and cardiac ablation |
| Johnson & Johnson (Ethicon) | Surgery and robotics | Staplers, energy devices and the Ottava robot in clinical study |
| Boston Scientific Corporation | Interventional specialist | FARAPULSE ablation, endoscopy and urology devices |
| Stryker Corporation | Orthopedics and vascular | Orthopedic robotics and Inari clot removal systems |
| Olympus Corporation | Endoscopy specialist | Flexible and rigid scopes, subject to a 2026 U.S. import alert |
| Koninklijke Philips N.V. | Imaging and therapy | Image-guided therapy systems for catheter procedures |
| Zimmer Biomet Holdings Inc. | Orthopedics | Robotic and arthroscopic tools for joint procedures |
| HOYA Corporation | Optics and endoscopy | Flexible endoscopes for gastrointestinal care |
| CONMED Corporation | Surgical devices | Arthroscopy, energy and laparoscopic instruments |
| Renishaw plc | Engineering and robotics | Neurosurgical robotics for stereotactic procedures |
| Smith & Nephew plc | Orthopedics and sports medicine | Arthroscopic tools and orthopedic robotics |
Robotics and outpatient care set the growth pace
Credence Research's view is that robotics and outpatient care will set the growth pace for minimally invasive surgery devices through 2035. Handheld instruments keep the largest share because every procedure consumes them, but robotic systems add value faster as more suppliers win clearances and hospitals add consoles. Catheter-based ablation and clot removal widen the role of small-incision care in cardiology and vascular medicine. Quality compliance remains a key risk, as the 2026 Olympus import alert shows. Suppliers with broad portfolios and strong training programs are best placed to grow.
Procedure volumes and device prices anchor the model
The report uses 2025 as the base year and forecasts market value to 2035, with growth rates stated for 2026–2035. Market values come from the Credence Research market model, which combines procedure volumes by application, installed systems and average device prices by region and end user. Splits by product, application, end user and region are Credence Research estimates. Sources used include FDA notices, SEC filings, World Bank population data and company press releases. No primary interviews or surveys were used to build the estimates in this report.
Robotic and catheter-based care gain share by 2035
By 2035, the market reaches USD 58.63 billion, with handheld instruments still providing the largest share of product value. Robotic systems gain share as competing platforms reach more hospitals, and urological procedures grow fastest among applications. ASCs take a larger share of cases as payers push lower-cost settings. Asia Pacific adds capacity as China and India build operating rooms, while North America remains the largest region. Suppliers keep investing in training, imaging and catheter platforms to defend their positions.
Frequently Asked Questions
How big is the minimally invasive surgery devices market?
Which product type leads the market?
Which product type grows fastest?
Which region holds the largest share?
Which new surgical robots have been cleared?
Why are ambulatory surgical centers growing fastest?
Who are the leading companies?
What are the main challenges?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Handheld Instruments
- 1.2.2 Guiding Devices
- 1.2.3 Electrosurgical Devices
- 1.2.4 Endoscopic Devices
- 1.2.5 Laparoscopic Devices
- 1.2.6 Monitoring & Visualization Devices
- 1.2.7 Ablation Devices
- 1.2.8 Laser-based Devices
- 1.2.9 Robotic-assisted Surgical Systems
- 1.2.10 Others
- 1.3 By Application
- 1.3.1 Cardiovascular
- 1.3.2 Gastrointestinal
- 1.3.3 Orthopedic
- 1.3.4 Gynecological
- 1.3.5 Urological
- 1.3.6 Other Applications
- 1.3.7 Aesthetic
- 1.3.8 Neurological
- 1.4 By End User
- 1.4.1 Hospitals
- 1.4.2 ASCs
- 1.4.3 Clinics
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 32.85 billion → 2035: USD 58.63 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Minimally Invasive Surgery Devices Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Minimally Invasive Surgery Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Minimally Invasive Surgery Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Minimally Invasive Surgery Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Minimally Invasive Surgery Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Minimally Invasive Surgery Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Minimally Invasive Surgery Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Minimally Invasive Surgery Devices Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 32.85 billion → 2035: USD 58.63 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Minimally Invasive Surgery Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Handheld Instruments
- 12.3.7.2 Guiding Devices
- 12.3.7.3 Electrosurgical Devices
- 12.3.7.4 Endoscopic Devices
- 12.3.7.5 Laparoscopic Devices
- 12.3.7.6 Monitoring & Visualization Devices
- 12.3.7.7 Ablation Devices
- 12.3.7.8 Laser-based Devices
- 12.3.7.9 Robotic-assisted Surgical Systems
- 12.3.7.10 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cardiovascular
- 12.4.7.2 Gastrointestinal
- 12.4.7.3 Orthopedic
- 12.4.7.4 Gynecological
- 12.4.7.5 Urological
- 12.4.7.6 Other Applications
- 12.4.7.7 Aesthetic
- 12.4.7.8 Neurological
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hospitals
- 12.5.7.2 ASCs
- 12.5.7.3 Clinics
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Minimally Invasive Surgery Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Minimally Invasive Surgery Devices Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Minimally Invasive Surgery Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Minimally Invasive Surgery Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Boston Scientific Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Intuitive Surgical Inc.
- 18.4 Medtronic
- 18.5 Johnson & Johnson (Ethicon)
- 18.6 Stryker Corporation
- 18.7 Olympus Corporation
- 18.8 Koninklijke Philips N.V.
- 18.9 Zimmer Biomet Holdings Inc.
- 18.10 HOYA Corporation
- 18.11 CONMED Corporation
- 18.12 Renishaw plc
- 18.13 Smith & Nephew plc
- 18.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

