
Market Overview
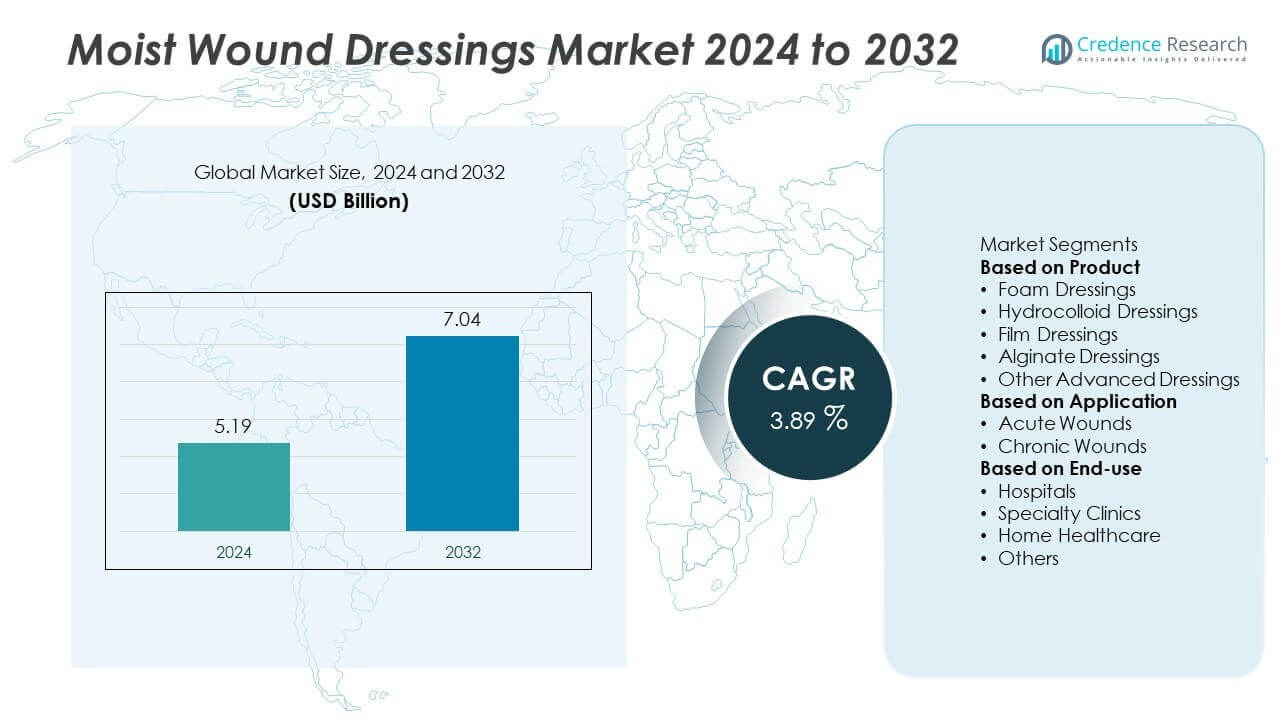
The Moist Wound Dressings market size was valued at USD 5.19 billion in 2024 and is projected to reach USD 7.04 billion by 2032, growing at a CAGR of 3.89% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Moist Wound Dressings Market Size 2024 | USD 5.19 Billion |
| Moist Wound Dressings Market, CAGR | 3.89% |
| Moist Wound Dressings Market Size 2032 | USD 7.04 Billion |
The Moist Wound Dressings Market grows through rising cases of chronic wounds, diabetes, and pressure ulcers that require advanced treatment. Hospitals adopt these products to reduce infection risks, accelerate recovery, and minimize hospital stays.
The Moist Wound Dressings Market demonstrates strong geographical diversity, with North America leading due to advanced healthcare systems, high chronic wound prevalence, and supportive reimbursement structures. Europe follows with widespread adoption of innovative wound care solutions supported by established clinical practices and R&D investments. Asia-Pacific emerges as the fastest-growing region, driven by rising diabetes cases, healthcare infrastructure expansion, and increasing awareness of advanced wound care. Latin America and the Middle East & Africa show gradual but steady growth through hospital expansions and private sector investments. Key players shaping the market include 3M, Smith & Nephew, Coloplast A/S, and Convatec, Inc., each focusing on technological advancements, product innovations, and strategic partnerships. Medline Industries, Cardinal Health, and B. Braun Medical Inc. contribute to supply chain strength and global distribution networks, while Acelity, Systagenix, and Derma Sciences, Inc. expand their portfolios to meet evolving patient needs across chronic and acute wound segments.
Market Insights
- The Moist Wound Dressings Market was valued at USD 5.19 billion in 2024 and is projected to reach USD 7.04 billion by 2032, growing at a CAGR of 3.89%.
- Rising prevalence of chronic wounds, diabetes, and pressure ulcers drives strong demand for advanced dressings.
- Technological innovations in foams, hydrocolloids, alginates, and hydrogels improve healing efficiency and patient comfort.
- Leading players such as 3M, Smith & Nephew, Coloplast, and Convatec expand portfolios through product innovation and global partnerships.
- High product cost and limited reimbursement in emerging economies act as restraints, slowing adoption in price-sensitive markets.
- North America dominates due to advanced healthcare infrastructure, while Asia-Pacific shows fastest growth supported by expanding healthcare access and awareness.
- Growing interest in home healthcare, antimicrobial solutions, and smart wound monitoring technologies represents a key trend shaping future opportunities.
Market Drivers
Rising Prevalence of Chronic and Acute Wounds
The growing incidence of chronic conditions such as diabetes, venous leg ulcers, and pressure ulcers drives demand for advanced wound care solutions. Patients with these conditions require long-term treatment that promotes moisture balance to speed recovery. Acute injuries from accidents, burns, and surgical procedures further expand the need for effective dressings. Hospitals and clinics adopt these products to reduce infection risks and improve healing outcomes. The Moist Wound Dressings Market benefits directly from the rising number of patients who need specialized care. It reinforces the role of dressings in improving patient recovery rates and lowering healthcare costs.
- For instance, clinical studies have shown Smith & Nephew's ALLEVYN LIFE dressings can reduce hospital-acquired pressure injuries and generate significant cost savings, adding the dressings to a prevention protocol reduced sacral pressure injuries by up to 71% in one study.
Technological Advancements in Dressing Materials
Manufacturers introduce dressings with advanced features such as antimicrobial coatings, oxygen permeability, and bioactive compounds. These innovations enhance wound healing efficiency while reducing complications. Hydrocolloids, alginates, foams, and hydrogel-based products offer diverse solutions for different wound types. Companies also focus on materials that reduce pain during removal, improving patient compliance. Continuous R&D investment ensures the availability of dressings that combine comfort with clinical effectiveness. It strengthens the appeal of moist wound dressings among healthcare professionals worldwide.
- For instance, ConvaTec's information, AQUACEL® Ag+ Extra is a silver-containing hydrofiber dressing for infected wounds. It contains 1.2% ionic silver, which is released in a controlled manner upon contact with wound fluid to combat infection.
Supportive Government and Healthcare Initiatives
Government programs and reimbursement policies encourage the use of advanced wound care technologies. Many healthcare systems promote early adoption of these products to minimize hospital stays and readmission rates. Policies that focus on reducing the burden of chronic wounds fuel the uptake of moisture-retentive solutions. Hospitals benefit from cost savings when wound healing accelerates under these technologies. The Moist Wound Dressings Market gains from favorable policies that align with improved patient outcomes. It ensures consistent demand across both developed and developing regions.
Growing Aging Population and Healthcare Infrastructure Expansion
An aging population increases susceptibility to chronic wounds and pressure ulcers, creating sustained demand. Elderly patients represent a large share of the consumer base for advanced wound dressings. Expanding healthcare infrastructure in emerging economies further supports adoption. Hospitals, long-term care facilities, and home healthcare providers integrate moist dressings into routine practices. Investments in advanced treatment centers accelerate product penetration across underserved regions. It broadens the global footprint of moist wound dressing solutions while improving access to quality care.
Market Trends
Shift Toward Advanced and Customized Wound Care Solutions
Healthcare providers increasingly adopt advanced dressings tailored to specific wound types and healing stages. Customized solutions such as foam dressings for exudating wounds and hydrocolloids for pressure ulcers gain traction. Patients prefer products that reduce dressing changes and minimize pain. The Moist Wound Dressings Market reflects this trend by offering diverse product lines for targeted applications. It helps healthcare facilities improve treatment efficiency and enhance patient satisfaction. Manufacturers focus on differentiation to meet growing demand for specialized solutions.
- For instance, Smith & Nephew reported that their Allevyn® Gentle Border foam dressings reduced dressing change frequency to every 5–7 days for exudating wounds, improving patient comfort.
Integration of Antimicrobial and Bioactive Technologies
Dressings with antimicrobial properties such as silver, iodine, or honey-based formulations gain strong acceptance. These technologies lower infection risks while supporting faster healing. Bioactive dressings that release growth factors or stimulate cell regeneration also expand their role in modern wound care. Hospitals and clinics recognize their value in reducing complications and shortening recovery times. The trend encourages consistent R&D investment in combining moisture retention with infection control. It reinforces the appeal of advanced dressings in high-risk patient groups.
- For instance, ConvaTec AQUACEL® Ag+ Extra dressings release ionic silver in a controlled manner as they absorb wound fluid. This technology effectively reduces infection risks in chronic wounds by targeting harmful bacteria and biofilm.
Rising Adoption of Home Healthcare and Self-Care Practices
Patients and caregivers increasingly choose home-based wound management due to convenience and cost benefits. Easy-to-apply moist dressings that require minimal supervision support this shift. Companies develop user-friendly packaging and instructions to aid non-professional use. The Moist Wound Dressings Market grows as self-care becomes an important trend in wound management. It reduces the burden on hospitals while ensuring continuity of care. Aging populations and patients with chronic conditions fuel consistent demand for home-use products.
Digitalization and Smart Wound Management Solutions
Integration of digital technologies into wound care introduces smart dressings capable of monitoring wound conditions. Sensors embedded in dressings track parameters such as moisture levels, pH, and temperature. These insights help clinicians adjust treatment strategies in real time. Research partnerships drive innovations that combine wearable health tech with traditional dressings. The trend highlights the future direction of the industry toward precision wound care. It enhances both treatment outcomes and long-term healthcare efficiency.
Market Challenges Analysis
High Cost of Advanced Dressing Products and Limited Reimbursement
The elevated cost of advanced moist wound dressings poses a barrier in many healthcare systems. Hospitals and clinics in low-income regions struggle to afford premium products. Limited reimbursement coverage in certain countries further restricts patient access. Price-sensitive markets often rely on traditional dressings despite slower healing outcomes. The Moist Wound Dressings Market faces pressure to balance innovation with affordability. It challenges manufacturers to create cost-effective solutions without compromising quality or clinical performance.
Awareness Gaps and Shortage of Skilled Professionals
Lack of awareness about advanced wound care among patients and healthcare workers limits adoption. Many caregivers continue to use outdated methods due to limited training. Shortages of skilled wound care specialists in emerging economies intensify the issue. Patients in rural areas often have poor access to advanced treatment options. The Moist Wound Dressings Market struggles to expand in these regions despite rising demand. It underscores the importance of education programs and workforce development to drive adoption globally.
Market Opportunities
Expansion in Emerging Healthcare Markets
Rapid improvements in healthcare infrastructure across Asia-Pacific, Latin America, and the Middle East create significant growth opportunities. Rising government investments and private sector involvement enhance access to advanced wound care. Hospitals and clinics in these regions adopt modern dressings to reduce infection rates and improve outcomes. The Moist Wound Dressings Market gains traction as awareness of specialized products increases. It allows manufacturers to expand product reach through partnerships with local distributors and healthcare providers. Growing medical tourism also accelerates adoption of advanced wound care technologies in developing economies.
Innovation in Smart and Sustainable Dressing Solutions
The integration of digital health features into wound dressings presents new avenues for growth. Smart dressings with sensors that monitor healing progress appeal to both clinicians and patients. Sustainability-focused innovations, such as biodegradable materials, align with global environmental goals. Companies that prioritize eco-friendly and technology-driven solutions can capture strong demand. The Moist Wound Dressings Market benefits from combining clinical effectiveness with sustainability and digital innovation. It encourages firms to invest in research pipelines that address evolving healthcare and regulatory needs.
Market Segmentation Analysis:
By Product
Moist wound dressings are categorized into hydrocolloids, hydrogels, alginates, foams, and films. Foam dressings hold a significant share due to their ability to absorb high exudate levels while maintaining moisture balance. Hydrocolloids remain popular for pressure ulcer treatment because of their strong adherence and long wear time. Hydrogels support healing in dry wounds by rehydrating tissue, which is vital in burn and necrotic cases. Alginates, derived from seaweed, are widely used for moderate to heavily exuding wounds. The Moist Wound Dressings Market grows as each product category addresses different clinical needs. It enables providers to select specialized options based on wound type and healing stage.
- For instance, The Mölnlycke Mepilex® Border foam dressing can be worn for up to seven days, depending on the wound, effectively reducing the frequency of dressing changes.
By Application
Applications cover chronic wounds, acute wounds, and surgical wounds. Chronic wounds such as diabetic ulcers and venous leg ulcers dominate usage due to the rising global burden of lifestyle-related diseases. Acute injuries from trauma and burns also drive consistent demand for advanced dressings. Surgical wounds represent a growing segment as hospitals prioritize faster recovery and reduced infection risk. The Moist Wound Dressings Market reflects strong adoption in chronic care, where patients require long-term management. It strengthens the role of these dressings in improving clinical outcomes across diverse medical conditions.
- For instance, studies have shown ConvaTec's AQUACEL Ag dressings can reduce the incidence of superficial surgical site infections in certain procedures. A 2024 trial found that these dressings led to a 40% relative reduction of superficial infections after gastrointestinal surgery, especially in the lower GI tract.
By End-use
Hospitals account for the largest share due to high patient inflow and demand for advanced wound care. Specialty clinics and wound care centers also contribute strongly as they provide focused treatment programs. Home healthcare emerges as a high-potential segment supported by rising preference for self-care and outpatient treatment. Long-term care facilities use moist dressings to manage pressure ulcers and chronic conditions among elderly populations. The Moist Wound Dressings Market benefits from the growing diversity of end-use settings. It ensures product penetration across both institutional and home-based care environments, expanding overall market reach.
Segments:
Based on Product
- Foam Dressings
- Hydrocolloid Dressings
- Film Dressings
- Alginate Dressings
- Other Advanced Dressings
Based on Application
- Acute Wounds
- Chronic Wounds
Based on End-use
- Hospitals
- Specialty Clinics
- Home Healthcare
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America accounted for 38% of the Moist Wound Dressings Market in 2024, leading global adoption. Strong prevalence of diabetes and obesity in the U.S. drives chronic wound cases that require continuous treatment. Hospitals and outpatient facilities across the region integrate advanced dressings to improve recovery outcomes and reduce infection risks. Government-backed reimbursement frameworks support the adoption of higher-cost, technologically advanced solutions. The presence of global players and active research initiatives further strengthen market penetration. It also benefits from the rising adoption of home healthcare practices, which encourages consistent demand for user-friendly products.
Europe
Europe held 27% of the global share, supported by advanced healthcare systems and strict regulatory guidelines. Countries such as Germany, France, and the UK prioritize the use of high-quality wound care products to reduce hospital stays. Growing elderly populations across Western Europe increase the incidence of pressure ulcers, fueling the need for moisture-retentive dressings. Reimbursement policies in several European nations encourage wider use of innovative solutions. The Moist Wound Dressings Market benefits from strong R&D investments and product approvals that align with EU healthcare standards. It also gains traction in Eastern Europe, where expanding healthcare budgets improve access.
Asia-Pacific
Asia-Pacific represented 22% of the global share and emerged as the fastest-growing regional market. Rising diabetes prevalence in China and India contributes to higher rates of chronic wounds. Healthcare infrastructure expansion across Southeast Asia improves access to advanced dressings in hospitals and specialty clinics. Local manufacturers and international players focus on partnerships to address growing demand. The Moist Wound Dressings Market expands as governments invest in wound care awareness and treatment programs. It benefits from a growing middle-class population with higher healthcare spending power. It also sees opportunities from medical tourism, particularly in countries like Thailand and India.
Latin America
Latin America captured 7% of the global share, with Brazil and Mexico leading regional adoption. Expanding healthcare services and rising investments in hospital infrastructure contribute to greater use of advanced dressings. Chronic conditions such as venous ulcers and diabetic wounds remain key drivers of demand. Limited reimbursement in some countries creates challenges, but rising awareness supports gradual adoption. The Moist Wound Dressings Market in Latin America benefits from collaborations between local distributors and multinational companies. It also grows through the increasing presence of private healthcare providers across urban areas.
Middle East & Africa
The Middle East & Africa accounted for 6% of the global share, showing gradual but steady adoption. High rates of lifestyle diseases such as diabetes in Gulf countries drive market growth. Hospitals in the UAE and Saudi Arabia adopt advanced dressings to reduce post-surgical complications and speed recovery. Africa faces challenges from limited awareness and affordability, but donor-backed healthcare projects improve access in select regions. The Moist Wound Dressings Market gains momentum through government-led investments in modern healthcare infrastructure. It ensures long-term growth opportunities, particularly in urban centers and specialized care facilities.
Key Player Analysis
- Derma Sciences, Inc.
- Smith & Nephew
- 3M
- Systagenix
- Convatec, Inc.
- Cardinal Health
- Coloplast A/S
- Braun Medical Inc.
- Medline Industries, Inc.
- Acelity
Competitive Analysis
Competitive landscape of the Moist Wound Dressings Market features leading players including 3M, Smith & Nephew, Coloplast A/S, Convatec Inc., Medline Industries, Cardinal Health, B. Braun Medical Inc., Acelity, Systagenix, and Derma Sciences Inc. These companies hold strong positions through broad product portfolios, innovation in advanced materials, and established distribution networks. They focus on expanding product lines with technologies such as antimicrobial coatings, bioactive compounds, and smart monitoring features to address diverse clinical needs. Strategic mergers, acquisitions, and partnerships help strengthen their market reach and accelerate research capabilities. Leading firms invest heavily in R&D to deliver dressings that improve healing outcomes while reducing patient discomfort, aligning with the growing demand for efficient and patient-friendly solutions. Expansion in emerging markets remains a priority, supported by collaborations with local distributors and healthcare providers. Sustainability initiatives, such as developing eco-friendly and biodegradable dressing materials, also gain prominence. Competitive pressure encourages continuous innovation, pricing strategies, and regulatory compliance efforts. The Moist Wound Dressings Market therefore reflects a dynamic environment where innovation, product differentiation, and global presence remain central to sustaining leadership and capturing long-term growth opportunities.
Recent Developments
- In August 2025, Smith & Nephew initiated the U.S. launch of ALLEVYN Ag+ SURGICAL, a new antimicrobial silver foam dressing featuring ComfortSTAY™ silicone adhesion and HighFLEX™ flexibility for improved patient movement.
- In May 2025, Coloplast A/S reported that its Advanced Wound Dressings segment grew 3%, with Kerecis (fish-skin-based technology acquired in 2023) growing 30%.
- In January 2024, Medline Industries, Inc. launched OptiView® Transparent Dressing with HydroCore™ technology. This first-of-its-kind clear wound dressing redistributes pressure and cools the skin, while letting caregivers observe the wound without removal.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, End-use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Growing global prevalence of chronic wounds will continue to boost demand.
- Innovations in antimicrobial and bioactive technologies will enhance treatment efficacy.
- Rise in smart dressings with sensor capabilities will support precision wound management.
- Sustainable and biodegradable materials will gain traction across markets.
- Expansion of home healthcare services will encourage adoption of user-friendly products.
- Emerging economies will drive strong growth through infrastructure development.
- Partnerships between global and local players will broaden distribution reach.
- Increased focus on patient comfort and reduced dressing changes will influence designs.
- Regulatory support and reimbursement reforms will enable wider access to advanced dressings.
- Digital health integration will improve monitoring and optimize healing outcomes.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Chronic and Acute Wounds
Increasing cases of diabetes, venous leg ulcers, and pressure ulcers, as well as acute injuries from trauma and surgery, are driving demand for moist wound dressings that promote faster healing and reduce infection risk.
Technological Advancements in Dressing Materials
Innovations such as antimicrobial coatings, hydrocolloids, foams, and hydrogels enhance healing efficiency, patient comfort, and infection control, making advanced dressings more attractive to healthcare providers.
Supportive Government and Healthcare Initiatives
Favorable reimbursement policies and government programs encourage the adoption of advanced wound care products, helping hospitals minimize hospital stays and improve patient outcomes.
Expansion of Healthcare Infrastructure and Aging Population
Growth in healthcare facilities and an increasing elderly population, especially in emerging markets, are expanding the consumer base for advanced wound dressings and improving access to modern wound care.
Shift Toward Home Healthcare and Self-Care
The growing trend of home-based wound management and self-care, supported by user-friendly dressings, is increasing market penetration beyond traditional hospital settings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Moist Wound Dressings, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Moist Wound Dressings market projected to grow between 2025 and 2032?
Which Moist Wound Dressings market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Moist Wound Dressings market?
Who are the leading companies in the Moist Wound Dressings market?
Which region commanded the largest share of the Moist Wound Dressings market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-use
- 1.2.1 Hospitals
- 1.2.2 Specialty Clinics
- 1.2.3 Home Healthcare
- 1.2.4 Long-term Care Facilities
- 1.3 By Product
- 1.3.1 Foam Dressings
- 1.3.2 Hydrocolloid Dressings
- 1.3.3 Film Dressings
- 1.3.4 Alginate Dressings
- 1.3.5 Other Advanced Dressings
- 1.4 By Application
- 1.4.1 Acute Wounds
- 1.4.2 Chronic Wounds
- 1.4.3 Surgical Wounds
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5.19 billion → 2032: USD 7.04 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Moist Wound Dressings Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Moist Wound Dressings Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Moist Wound Dressings Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Moist Wound Dressings Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Moist Wound Dressings Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Moist Wound Dressings Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Moist Wound Dressings Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Moist Wound Dressings Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5.19 billion → 2032: USD 7.04 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Moist Wound Dressings Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Specialty Clinics
- 12.3.7.3 Home Healthcare
- 12.3.7.4 Long-term Care Facilities
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Foam Dressings
- 12.4.7.2 Hydrocolloid Dressings
- 12.4.7.3 Film Dressings
- 12.4.7.4 Alginate Dressings
- 12.4.7.5 Other Advanced Dressings
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Acute Wounds
- 12.5.7.2 Chronic Wounds
- 12.5.7.3 Surgical Wounds
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Moist Wound Dressings End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Moist Wound Dressings Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Moist Wound Dressings Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Moist Wound Dressings Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 3M
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Smith & Nephew
- 18.4 Coloplast A/S
- 18.5 Convatec, Inc.
- 18.6 Medline Industries, Inc.
- 18.7 Cardinal Health
- 18.8 B. Braun Medical Inc.
- 18.9 Acelity
- 18.10 Systagenix
- 18.11 Derma Sciences, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

