
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
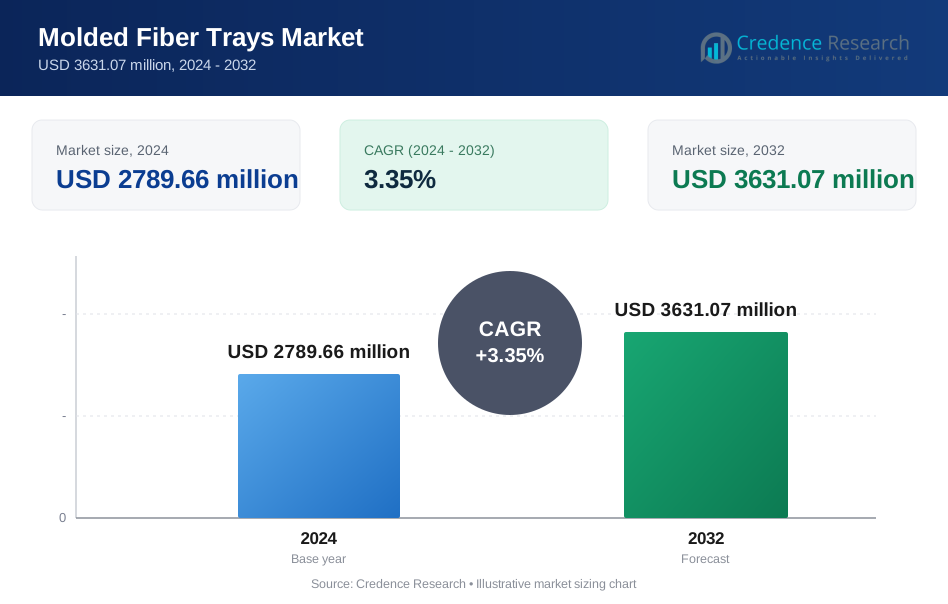
| Molded Fiber Trays Market Size 2024 | USD 2789.66 Million |
| Molded Fiber Trays Market, CAGR | 3.35% |
| Molded Fiber Trays Market Size 2032 | USD 3631.07 Million |
Market Overview
The Molded Fiber Trays Market is projected to grow from USD 2789.66 million in 2024 to USD 3631.07 million by 2032, reflecting a compound annual growth rate (CAGR) of 3.35%.
The Molded Fiber Trays Market is driven by increasing consumer demand for sustainable and eco-friendly packaging solutions, as well as stringent environmental regulations aimed at reducing plastic usage. Key trends include advancements in manufacturing technologies that improve the durability and versatility of molded fiber trays, making them suitable for a wide range of applications. The growth of the e-commerce sector and the rising need for protective packaging during transportation also propel market expansion. Additionally, the shift towards circular economy practices and the emphasis on recyclability and compostability of packaging materials further stimulate market growth.
The Molded Fiber Trays Market is experiencing significant growth across various regions, with North America and Europe leading due to stringent environmental regulations and high consumer demand for sustainable packaging. The Asia-Pacific region is rapidly expanding, driven by urbanization and increasing awareness of eco-friendly solutions. Key players such as Huhtamaki Oyj, Brødrene Hartmann A/S, and Eco-Products, Inc. dominate the market, leveraging advanced technologies and extensive distribution networks. These companies are pivotal in driving innovation and setting industry standards, ensuring the widespread adoption of molded fiber trays globally.
Market Drivers
Rising Consumer Demand for Sustainable Packaging
Consumers are increasingly aware of the environmental impact of packaging and are opting for eco-friendly alternatives, driving the demand for molded fiber trays. For instance, 73% of consumers say they want to change their consumption habits to reduce their environmental impact. This shift is reinforced by regulatory pressures, as governments worldwide impose stricter regulations on plastic packaging, encouraging the adoption of sustainable options. Companies are also recognizing the importance of sustainability in enhancing their brand image, leading them to adopt eco-friendly packaging solutions like molded fiber trays. This trend not only satisfies consumer preferences but also aligns with corporate social responsibility goals, creating a positive market dynamic.
Growth in E-commerce and Online Retail
The rise of e-commerce and online retail significantly boosts the demand for molded fiber trays, which offer excellent cushioning and protection during shipping, thus reducing damage rates. For example, 20.1% of retail purchases are expected to take place online in 2024. These trays are lighter than traditional packaging materials, making them a cost-effective option by reducing shipping costs. Additionally, the sustainability appeal of molded fiber trays resonates with consumers who are increasingly concerned about the environmental impact of their online shopping habits. As a result, the adoption of these trays supports both logistical efficiency and environmental responsibility, enhancing their attractiveness in the market.
Advancements in Molded Fiber Technology
Technological advancements have significantly improved the performance of molded fiber trays, enhancing their strength, durability, and water resistance. For instance, continuous innovations in molded fiber are resulting in new types of packaging that companies say are more customizable and cost-competitive than plastic. These improvements make them a viable alternative to traditional packaging materials. Manufacturers now offer customization options, creating molded fiber trays in various shapes, sizes, and designs to meet specific product requirements. Additionally, improved production processes have made these trays more cost-competitive, further driving their adoption. These technological innovations are crucial in addressing the evolving needs of consumers and businesses, ensuring the continued growth of the molded fiber trays market.
Expansion of the Food and Beverage Industry
The food and beverage industry is a major driver for the molded fiber trays market, particularly for packaging fresh produce, meal kits, and ready-to-eat meals. Molded fiber trays provide excellent ventilation and moisture absorption, making them ideal for packaging fresh fruits and vegetables. The growing popularity of meal kits and ready-to-eat meals has further increased the demand for sustainable and functional packaging solutions. Moreover, molded fiber trays offer good barrier properties, protecting food products from contamination and ensuring consumer safety, which is paramount in the food industry.
Market Trends
Increased Focus on Sustainability and Circular Economy
The Molded Fiber Trays Market is increasingly driven by a heightened focus on sustainability and the circular economy. For instance, a survey across 11 countries revealed that 73% of consumers want to change their consumption habits to reduce their environmental impact. Industry players are exploring the use of bio-based materials such as sugarcane bagasse and bamboo to enhance the eco-friendliness of their products. Incorporating higher percentages of recycled fiber into molded fiber trays is another growing trend, reflecting a commitment to reducing reliance on virgin materials and supporting recycling initiatives. In fact, only 14% of the plastic packaging used globally is recycled, while a worrying 40% ends its useful life in landfills. Additionally, there is significant development in compostable molded fiber trays to address end-of-life concerns and provide a sustainable disposal option for consumers. This focus on sustainability is not only about meeting regulatory requirements but also about aligning with consumer values and corporate sustainability goals. The transition to bio-based and recycled content materials is a critical step in minimizing environmental impact and promoting a circular economy, where products are designed to be reused, recycled, or composted at the end of their life cycle.
Product Innovation and Customization
Product innovation and customization are key trends shaping the Molded Fiber Trays Market. Manufacturers are incorporating functional enhancements such as barrier coatings, anti-slip surfaces, and dividers to improve product protection and presentation. These features are crucial in meeting the diverse needs of different market segments, from food packaging to industrial applications. For instance, Footprint, an Arizona-based materials science technology firm, launched a plant-based recyclable, dyed fiber razor tray in partnership with Gillette to package the GilletteLabs Razor with Exfoliating Bar. Customized tray designs tailored to specific product requirements and branding needs are becoming increasingly popular, allowing companies to differentiate their offerings and enhance brand recognition. Furthermore, value-added services such as design, prototyping, and testing are being offered to customers, ensuring that the final product meets their exact specifications and performance standards. These innovations not only improve the functionality and aesthetic appeal of molded fiber trays but also provide competitive advantages to manufacturers by enabling them to cater to niche markets and specific customer demands. As the market evolves, continuous innovation and customization will be essential in addressing emerging challenges and opportunities, driving the overall growth and competitiveness of the molded fiber trays industry.
Market Challenges Analysis
High Initial Investment and Raw Material Availability
The Molded Fiber Trays Market faces significant challenges due to the high initial investment required for equipment and tooling. Establishing a production facility necessitates substantial capital for molding equipment, which can be a barrier to entry for new players. For instance, the cost of a high-capacity automatic pulp molding machine can exceed $25,000, as indicated by industry listings. Additionally, ongoing investment in research and development is crucial for developing new products and improving production processes, further increasing financial commitments. Another major challenge is the availability and cost of raw materials. Fluctuations in the supply chain, particularly in the availability of recycled paper and other essential materials, can disrupt production schedules and impact product availability. Rising costs of pulp and other raw materials also pose a threat to profitability, making it difficult for manufacturers to maintain competitive pricing while ensuring high-quality standards. These financial and material constraints necessitate strategic planning and efficient resource management to sustain growth in the molded fiber trays market.
Technical Limitations and Consumer Perception
Technical limitations inherent to molded fiber trays present additional hurdles. For instance, these trays can be susceptible to moisture, which may affect product integrity and suitability for certain applications. Overcoming moisture sensitivity requires advancements in coating technologies and material enhancements, which can be both time-consuming and costly. The complexity of designing intricate shapes and structures further complicates production, requiring sophisticated tooling and extended development timelines. On the consumer front, limited awareness and price sensitivity are notable challenges. Despite the environmental benefits, some consumers remain unfamiliar with molded fiber trays and their advantages, leading to slower adoption rates. Additionally, the premium pricing associated with sustainable packaging can deter cost-conscious consumers, impacting market penetration.
Market Segmentation Analysis:
By Molded Pulp Type:
The Molded Fiber Trays Market is segmented by molded pulp type into Thick Wall, Transfer Molded, Thermoformed Fiber, and Processed Pulp, each serving distinct market needs. Thick Wall molded pulp is utilized primarily for heavy-duty packaging due to its robust structure, offering superior protection for consumer durables and industrial applications. Transfer Molded pulp, known for its lightweight properties, is ideal for packaging delicate items, including food and healthcare products. Thermoformed Fiber stands out for its smooth finish and precision, making it suitable for high-end consumer goods and electronics. Processed Pulp is favored for its versatility and cost-effectiveness, catering to a wide range of applications from foodservice to automotive components. This segmentation allows manufacturers to tailor their products to specific industry requirements, enhancing market adaptability and customer satisfaction.
By Product:
In terms of product segmentation, the Molded Fiber Trays Market is divided into Single Cavity and Multi Cavity trays. Single Cavity trays are commonly used for individual product packaging, providing secure and customized containment for items such as fruits, electronics, and healthcare supplies. These trays are designed to prevent movement and damage, ensuring product integrity during transportation and storage. Multi Cavity trays, on the other hand, are essential for packaging multiple items simultaneously, optimizing space and reducing material usage. They are widely used in the food industry for packing assortments of produce, baked goods, and meal kits, as well as in automotive and consumer electronics sectors for organizing and protecting multiple components. The ability to offer both single and multi-cavity solutions enhances the versatility of molded fiber trays, meeting diverse market demands efficiently.
Segments:
Based on Molded Pulp Type:
- Thick Wall
- Transfer Molded
- Thermoformed Fiber
- Processed Pulp
Based on Product:
- Single Cavity
- Multi Cavity
Based on End Use:
- Consumer Durables
- Food
- Healthcare
- Automotive
- Foodservice
- Others
Based on the Geography:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis
North America
North America leads the global molded fiber trays market, commanding a significant 35% market share. This dominance is primarily driven by the United States and Canada, where stringent environmental regulations, growing consumer awareness of sustainable packaging, and a robust food service industry fuel market growth. For instance, the U.S. accounted for 75.1% of the North American market share in 2022, largely due to the high demand for out-of-home food services, including catering and fast-food outlets. The region's molded fiber tray market is characterized by high demand for eco-friendly packaging solutions across various sectors, including food and beverage, electronics, and healthcare. Key factors contributing to North America's market leadership include the presence of major molded fiber manufacturers, continuous innovations in material composition and production techniques, and strong retail and e-commerce sectors. The region has witnessed a surge in demand for molded fiber trays as a sustainable alternative to plastic packaging, particularly in the food delivery and takeaway segments. Additionally, the increasing adoption of molded fiber trays in the electronics industry for product protection during shipping has further boosted market growth. North American manufacturers are at the forefront of developing advanced molded fiber trays with enhanced strength, moisture resistance, and customizable designs, catering to diverse industry needs while maintaining a focus on sustainability.
Asia-Pacific
Asia-Pacific emerges as the fastest-growing region in the molded fiber trays market, currently holding a 30% market share. This rapid growth is attributed to several factors, including increasing urbanization, rising disposable incomes, and growing environmental consciousness in countries like China, India, and Japan. For instance, the demand for transfer molded products in China and India has surged due to the increase in electronics goods production. The region's market is characterized by a shift towards sustainable packaging solutions, driven by government initiatives to reduce plastic waste and promote eco-friendly alternatives. Key industries contributing to Asia-Pacific's market growth include food packaging, consumer electronics, and healthcare. The region has seen significant investments in molded fiber production capacity, with local manufacturers adopting advanced technologies to improve product quality and production efficiency. Moreover, the expanding e-commerce sector in Asia-Pacific has created new opportunities for molded fiber trays in protective packaging applications. As sustainability becomes a key focus for businesses and consumers alike, the demand for molded fiber trays is expected to surge, potentially positioning Asia-Pacific to challenge North America's market leadership in the coming years.
Key Player Analysis
- Eco-Products, Inc.
- Brødrene Hartmann A/S
- Huhtamaki Oyj
- UFP Technologies, Inc.
- Pacific Pulp Molding, Inc.
- Pactiv LLC
- Henry Molded Products, Inc.
- Fabri-Kal Corporation
- Genpak, LLC
- Pro-Pac Packaging Limited
Competitive Analysis
In the competitive landscape of the Molded Fiber Trays Market, leading players like Huhtamaki Oyj, Brødrene Hartmann A/S, and Eco-Products, Inc. dominate due to their strong focus on sustainability and innovation. Huhtamaki Oyj leverages its extensive global network and technological expertise to offer high-quality, eco-friendly packaging solutions. Brødrene Hartmann A/S stands out with its deep commitment to environmental responsibility, providing advanced molded fiber products that meet stringent regulatory standards. Eco-Products, Inc. is recognized for its innovative approach to compostable and recyclable packaging, appealing to environmentally conscious consumers. These companies maintain a competitive edge through continuous investment in research and development, ensuring their products meet evolving market demands for sustainable packaging. Additionally, strategic partnerships and acquisitions further bolster their market positions, allowing them to expand their product portfolios and enhance their global reach. As a result, these key players set industry benchmarks and drive the overall growth and advancement of the molded fiber trays market.
Recent Developments
- In June 2024, Eco-Products launched a new line of compostable clamshells, cups, lids, cutlery, bowls, and containers under the Veridian™ brand. These products are designed to comply with Colorado's new Compostable Product Labeling Act, effective July 1, 2024. The Veridian line features over 50 items, all certified by BPI as compostable and clearly marked to ensure proper waste stream management.
- In October 2023, Thornico, through its subsidiary Thornico Food & Food Technology, offered to acquire all shares of Brødrene Hartmann at DKr360 per share. This acquisition aims to continue Hartmann’s existing strategies and activities.
- In April 2024, Brødrene Hartmann introduced a new range of vibrant colors for their packaging solutions in Europe.
- In July 2024, UFP Technologies acquired Welch Fluorocarbon, enhancing its capabilities in designing and manufacturing comprehensive solutions for medical devices.
- In January 2024, Genpak launched a new sustainable fiber packaging line without adding PFAS. The new Harvest Fiber line consists of hinged food service containers, trays, and tableware.
Market Concentration & Characteristics
The Molded Fiber Trays Market exhibits moderate market concentration, characterized by a mix of established global players and emerging regional manufacturers. Leading companies like Huhtamaki Oyj, Brødrene Hartmann A/S, and Eco-Products, Inc. hold significant market shares due to their extensive product portfolios, innovation capabilities, and strong distribution networks. The market is driven by increasing consumer demand for sustainable and eco-friendly packaging solutions, advancements in molding technology, and stringent environmental regulations. Despite the dominance of major players, smaller firms and new entrants find opportunities by focusing on niche markets and offering customized, eco-friendly solutions. This competitive environment fosters continuous innovation, efficiency improvements, and the adoption of sustainable practices, contributing to the overall growth and development of the molded fiber trays market.
Report Coverage
The research report offers an in-depth analysis based on Molded Pulp Type, Product, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Molded Fiber Trays Market will see increased adoption of bio-based and compostable materials.
- Technological advancements will improve the durability and functionality of molded fiber trays.
- Regulatory pressures will drive further innovation in eco-friendly packaging solutions.
- Expansion in e-commerce will boost demand for protective and sustainable packaging.
- Growth in the food and beverage industry will continue to propel market expansion.
- Customization of molded fiber trays to meet specific industry needs will become more prevalent.
- Investment in automation and digital design tools will enhance production efficiency.
- Emerging markets will present new growth opportunities for molded fiber tray manufacturers.
- Companies will focus on reducing production costs while maintaining high sustainability standards.
- Strategic partnerships and acquisitions will play a crucial role in expanding market presence and capabilities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Molded Fiber Trays Market?
What factors are driving the growth of the Molded Fiber Trays Market?
What are the key segments within the Molded Fiber Trays Market?
What are some challenges faced by the Molded Fiber Trays Market?
Who are the major players in the Molded Fiber Trays Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Molded Fiber Trays Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Molded Fiber Trays Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2789.66 million → 2032: USD 3631.07 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Molded Fiber Trays Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Molded Fiber Trays Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Molded Fiber Trays Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Molded Fiber Trays Market Drivers
- 3.3 Molded Fiber Trays Market Restraints & Challenges
- 3.4 Molded Fiber Trays Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Molded Fiber Trays Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Molded Fiber Trays Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Molded Fiber Trays category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Molded Fiber Trays Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Molded Fiber Trays Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Molded Fiber Trays market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Molded Fiber Trays Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Molded Fiber Trays Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Molded Fiber Trays Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Molded Fiber Trays (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Molded Fiber Trays Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Molded Fiber Trays Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Molded Fiber Trays Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Molded Fiber Trays Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Molded Fiber Trays Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Molded Fiber Trays Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Molded Fiber Trays Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Molded Fiber Trays Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Molded Fiber Trays Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
