
Market Overview
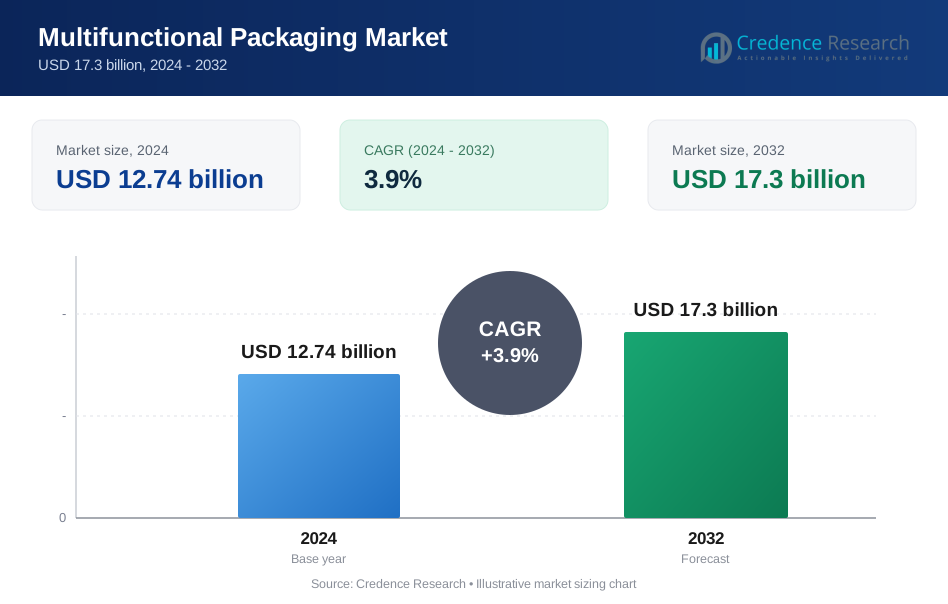
Multifunctional Packaging Market size was valued at USD 12.74 billion in 2024 and is anticipated to reach USD 17.3 billion by 2032, at a CAGR of 3.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Multifunctional Packaging Market Size 2024 | USD 12.74 Million |
| Multifunctional Packaging Market, CAGR | 3.9% |
| Multifunctional Packaging Market Size 2032 | USD 17.3 Million |
The multifunctional packaging market grows due to rising demand for extended shelf life, safety, and convenience in food, healthcare, and personal care sectors. Trends include the integration of smart technologies, active barrier materials, and sustainable packaging formats. Manufacturers focus on lightweight, recyclable, and digitally printed solutions to meet regulatory and consumer expectations. Demand from e-commerce and direct-to-consumer channels further accelerates adoption. These drivers shape ongoing innovation and expansion across flexible and rigid packaging formats globally.
North America leads the multifunctional packaging market due to strong adoption in food, pharmaceutical, and personal care industries. Europe follows with innovation in recyclable and bio-based packaging driven by strict regulations. Asia Pacific shows fast growth with rising urbanization, e-commerce, and expanding manufacturing bases. Latin America and the Middle East & Africa adopt functional packaging in key sectors like food and healthcare. Key players operating across these regions include Amcor, Mondi, Berry Global, and Westrock.
Market Insights
- The multifunctional packaging market was valued at USD 12.74 billion in 2024 and is projected to reach USD 17.3 billion by 2032, growing at a CAGR of 3.9%.
- Rising demand for extended shelf life, tamper-evidence, and product safety drives adoption across food, pharmaceutical, and personal care sectors.
- Smart packaging trends with QR codes, freshness indicators, and RFID tags continue to reshape product interaction and tracking.
- Leading players such as Amcor, Mondi, Sealed Air, and Berry Global focus on functional innovations, recyclability, and regional expansion strategies.
- High production and material costs, combined with limited recycling infrastructure, pose challenges to broader adoption in cost-sensitive markets.
- North America remains the leading region due to strong demand in healthcare and food packaging, while Asia Pacific sees fast growth through urbanization and e-commerce expansion.
- Europe drives innovation in sustainable and bio-based multifunctional formats supported by regulatory pressure and strong recycling frameworks.
Market Drivers
Rising Demand for Extended Shelf Life and Food Safety in the Food Industry
Growing consumer preference for fresh, minimally processed food drives demand for advanced packaging. Multifunctional packaging helps maintain product freshness and reduce spoilage by integrating barrier layers and antimicrobial agents. The food industry prioritizes shelf-life extension to reduce waste and comply with safety regulations. It enables active control of oxygen, moisture, and microbial contamination. The Multifunctional Packaging market benefits from innovations in films, coatings, and intelligent packaging indicators. Food processors adopt this technology to meet strict regulatory standards and support global distribution chains.
- For instance, researchers developed a battery‑free smart package that extended fish shelf life by 14 days using embedded NFC sensors and controlled-release active compounds.
Strong Adoption Across Healthcare and Pharmaceutical Packaging Needs
Pharmaceutical companies seek packaging solutions that offer protection, traceability, and contamination control. Multifunctional packaging delivers barrier performance and integration of authentication features such as RFID tags or QR codes. It ensures product integrity during transit and storage, particularly for temperature-sensitive drugs. Healthcare firms adopt smart packaging for real-time condition monitoring and tamper evidence. The Multifunctional Packaging market grows due to rising investments in cold chain infrastructure and personalized medicine. It supports strict safety protocols while enhancing patient trust.
- For instance, Identiv, in collaboration with InPlay, offers BLE-enabled smart labels designed for monitoring temperature-sensitive biologics like vaccines. The labels integrate sensors for temperature and can be read by standard smartphones. At high production volumes, pricing for these smart labels is projected to range between $1 and $2 per unit, with commercial availability expected in late 2025
Sustainability Regulations and Demand for Recyclable Smart Packaging Materials
Governments and brand owners focus on circular economy goals, pushing sustainable packaging innovation. Multifunctional packaging evolves to include bio-based, compostable, and recyclable structures with enhanced functionality. It combines protective properties with eco-friendly designs to reduce carbon footprint and material usage. Companies invest in lightweight, multi-layer films that reduce waste while maintaining performance. The Multifunctional Packaging market aligns with global packaging directives, especially in Europe and North America. It responds to consumer pressure for transparency, safety, and sustainability.
Technological Advancements in Functional Coatings and Intelligent Systems
Advances in nanotechnology and printed electronics boost the functionality of packaging films and containers. Smart coatings provide oxygen scavenging, UV protection, and temperature control tailored to product needs. It also integrates sensors and indicators to detect spoilage or breaches during distribution. The Multifunctional Packaging market benefits from cost reduction in these technologies, making them scalable. Producers leverage automation and digital printing to enhance customization and security. It creates differentiation for brands in competitive retail environments.

Market Trends
Integration of Smart Packaging Technologies for Real-Time Monitoring and Consumer Engagement
Brands increasingly adopt smart packaging to improve product safety and connect with consumers. Sensors, time-temperature indicators, and freshness monitors are integrated into packaging formats. It supports real-time tracking, condition alerts, and interactive features through QR codes or NFC. The Multifunctional Packaging market reflects strong investment in printed electronics and IoT-enabled formats. Smart packaging enhances brand trust, especially in food, pharma, and luxury segments. Consumers respond positively to transparency, product origin tracking, and digital authentication.
- For instance, Tageos manufactures RFID inlays and tags, including sustainable, paper-based options. In 2024, the company's annual global production capacity was over 9 billion inlays and tags, including UHF, HF, and NFC types. The company operates manufacturing facilities in France, the United States, and China.
Shift Toward Lightweight, Multi-Layer Films with Enhanced Functional Properties
Manufacturers prefer lightweight packaging to reduce material usage and optimize logistics. Multi-layer films provide barrier performance, mechanical strength, and printing flexibility. It meets the demands of sectors requiring moisture, gas, and UV resistance without increasing package weight. The Multifunctional Packaging market sees a shift toward downgauging and film simplification. Companies adopt advanced extrusion and lamination methods to improve efficiency. These films support recyclability while offering high-performance functionality.
- For instance, In research published in September 2023, a biodegradable nanocomposite film was developed using Zn-doped TiO₂ nanoparticles. When tested on plums (Oemleria cerasiformis), this packaging extended their freshness for 16 days, though the trial was conducted at a high temperature of 42 ± 2 °C.
Customization and Digital Printing Trends for Short Runs and Personalized Products
The rise of short product cycles and personalized marketing increases demand for flexible packaging formats. Digital printing enables high-quality visuals, quick design changes, and efficient production of small batches. It offers brands the ability to regionalize content or engage in limited-edition promotions. The Multifunctional Packaging market aligns with these trends by supporting variable data and interactive content. It empowers faster time-to-market for new product launches. Brands benefit from improved consumer engagement and shelf appeal.
Growth of Active Packaging Solutions with Antimicrobial and Antioxidant Additives
Active packaging expands with the inclusion of functional agents to preserve product quality. Materials with antimicrobial or oxygen-scavenging additives extend shelf life and enhance food safety. It enables better protection without relying on preservatives. The Multifunctional Packaging market integrates these features into films, coatings, and inserts. Sectors such as dairy, meat, and pharmaceuticals lead this trend. Functional packaging solutions support clean-label strategies and consumer health awareness.
Market Challenges Analysis
High Material and Production Costs Restrain Large-Scale Adoption Across Industries
The integration of barrier layers, smart sensors, and functional coatings increases packaging complexity. These advanced features drive up production costs compared to conventional formats. It limits adoption among small manufacturers and cost-sensitive sectors. The Multifunctional Packaging market faces resistance where margins remain thin, especially in emerging economies. Scalability of nanomaterials, RFID tags, and multi-layer films often requires specialized equipment and infrastructure. High initial investment slows the transition from traditional to multifunctional formats.
Limited Recycling Infrastructure and Regulatory Compliance Complexity
Multi-layer and composite structures pose significant recycling challenges due to mixed material composition. It becomes difficult for recyclers to separate layers or reuse them without contamination. The Multifunctional Packaging market must address growing regulatory scrutiny around recyclability and material traceability. Complex compliance with region-specific food contact and labeling rules also burdens producers. Companies struggle to meet both functional and environmental standards in a cost-effective way. Delays in standardizing testing protocols and certifications further slow innovation cycles.
Market Opportunities
Expansion of E-Commerce and Direct-to-Consumer Channels Drives Demand for Functional and Secure Packaging
The rise in online retail creates strong demand for packaging that ensures product protection and traceability. E-commerce requires durable, tamper-evident, and informative packaging to meet logistical and customer needs. It opens new opportunities for brands to integrate smart labels, authentication features, and damage-resistant designs. The Multifunctional Packaging market benefits from this shift, particularly in food, cosmetics, electronics, and pharmaceuticals. Secure and interactive packaging formats enhance customer experience and reduce returns. Direct-to-consumer models push innovation in compact, branded, and multi-functional solutions.
Growing Focus on Health, Safety, and Regulatory Compliance Boosts Intelligent Packaging Solutions
Rising consumer awareness about product safety and hygiene supports demand for active and intelligent packaging. Functional features such as antimicrobial layers, spoilage indicators, and freshness sensors offer measurable health benefits. It creates new growth avenues in packaged food, nutraceuticals, and healthcare products. The Multifunctional Packaging market aligns with stricter compliance and clean-label trends. Governments and industry bodies support adoption through pilot programs and innovation grants. These conditions make the market favorable for companies investing in functional and sustainable designs.
Market Segmentation Analysis:
By Product Type:
The market divides into flexible and rigid packaging. Flexible packaging leads due to its lightweight structure, ease of customization, and reduced material usage. It supports extended shelf life, resealability, and space efficiency, making it suitable for food and pharmaceutical products. Rigid packaging holds demand in applications requiring high strength and product protection. It finds usage in cosmetics, beverages, and electronics where durability and visual appeal matter. The Multifunctional Packaging market gains traction from the shift toward hybrid formats that combine rigidity with functional flexibility.
- For instance, carbon‑dots (R‑CDs) coated film extended salmon fillet shelf life by 4 days, while reducing lipid peroxidation by 72.92 %.
By Material Type:
Plastics dominate due to their versatility, cost-efficiency, and adaptability to functional enhancements. Paper and paperboard gain momentum in sustainable packaging initiatives, driven by consumer and regulatory pressure. Biodegradable materials show rapid growth due to demand for compostable and eco-safe packaging options. Metals and glass retain relevance for premium and sensitive products, where inertness and strength are critical. It includes pharmaceutical vials, canned foods, and high-end cosmetics. Others include foils, laminates, and emerging smart substrates used in specialty applications.
- For instance, researchers created cassava-starch-based films with just 0.01 % TiO₂, boosting banana shelf life from 5–7 days to 14 days, and tomato shelf life from 7–10 days to 21 days
By End-User:
Food and beverages form the largest segment, with high adoption of moisture barriers, freshness indicators, and resealable features. The pharmaceutical sector follows, driven by anti-counterfeit needs, cold chain packaging, and traceability mandates. Personal care and cosmetics rely on multifunctional formats to deliver both visual appeal and product stability. The electronics industry requires antistatic, shock-absorbing, and tamper-evident packaging for sensitive devices. It also supports the industrial segment where performance packaging protects against mechanical, thermal, or chemical stress. Other end users include home care, agriculture, and specialty retail packaging.
Segments:
Based on Product Type:
- Flexible Packaging
- Rigid Packaging
Based on Material Type:
- Plastics
- Paper & Paperboard
- Metals
- Glass
- Biodegradable Materials
- Others
Based on End User:
- Food & Beverages
- Pharmaceuticals
- Personal Care & Cosmetics
- Electronics
- Industrial
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest share in the multifunctional packaging market, accounting for 32% of the global revenue in 2024. The region leads due to strong demand across food, healthcare, and personal care sectors. Consumer preference for convenience, freshness, and tamper-evident packaging supports the shift toward functional formats. U.S.-based food producers and pharmaceutical firms adopt smart packaging solutions to improve traceability, comply with FDA regulations, and extend product shelf life. Packaging companies in the U.S. and Canada invest in antimicrobial films, time-temperature indicators, and interactive packaging, aligning with health and safety trends. It also benefits from rapid digitalization of supply chains and e-commerce expansion. Regional players focus on biodegradable and recyclable structures to meet sustainability mandates, creating further demand for multifunctional materials.
Europe
Europe captures 27% of the multifunctional packaging market, driven by strict environmental policies and innovation in eco-friendly packaging solutions. The region's regulatory framework under the EU Packaging and Packaging Waste Directive encourages the adoption of recyclable and compostable multifunctional formats. Leading economies such as Germany, France, and the U.K. invest in smart packaging, particularly in food and pharmaceutical sectors. It supports early adoption of bio-based barrier films and digital packaging formats with track-and-trace features. Europe's mature recycling infrastructure enables faster integration of sustainable multifunctional materials in both rigid and flexible packaging. Brands across Europe respond to consumer demands for clean-label, shelf-stable, and safe packaging with integrated indicators and RFID-enabled verification systems.
Asia Pacific
Asia Pacific holds 23% of the global multifunctional packaging market, supported by high population density, urbanization, and rising disposable income. Countries like China, Japan, South Korea, and India drive strong consumption across food, personal care, and electronics segments. It benefits from the presence of large-scale packaging manufacturers and strong demand from export-oriented industries. Governments in the region promote smart packaging adoption to reduce food loss and improve supply chain transparency. E-commerce growth and mobile-first consumer behavior push demand for packaging with QR codes, product information, and authentication features. Flexible packaging formats see significant growth due to ease of transport and low cost, with rising integration of antimicrobial and anti-counterfeit elements.
Latin America
Latin America represents 10% of the multifunctional packaging market in 2024, led by Brazil and Mexico. The region adopts multifunctional packaging in food and beverage applications to improve preservation in hot and humid climates. It sees growing demand in pharmaceuticals and cosmetics, where tamper-evidence and shelf stability are critical. Local firms introduce cost-effective solutions like resealable pouches and oxygen-scavenging layers in flexible packaging. Infrastructure challenges and limited recycling capacity slow the pace of adoption in rural areas. However, increasing awareness of food safety and government push for smart agriculture create long-term potential for multifunctional packaging growth.
Middle East & Africa
The Middle East & Africa account for 8% of the multifunctional packaging market, driven by demand in food, industrial, and healthcare sectors. GCC countries focus on improving packaging performance to extend shelf life under harsh climatic conditions. It encourages adoption of moisture-resistant and UV-blocking multifunctional films. Urban growth, especially in the UAE and Saudi Arabia, supports use in retail, pharmaceuticals, and consumer goods. Africa’s emerging economies begin exploring smart packaging for agricultural exports, though cost remains a key constraint. Local and international partnerships aim to develop scalable solutions using regionally available biodegradable materials. The region gradually builds regulatory frameworks to standardize multifunctional packaging use.
Key Player Analysis
- Schur Flexibles
- Ball Corporation
- Westrock
- Amcor
- Graphic Packaging Holding Company
- Sonoco
- Mondi
- Berry Global
- Sealed Air
Competitive Analysis
The multifunctional packaging market remains competitive, with leading players including Schur Flexibles, Ball Corporation, Westrock, Amcor, Graphic Packaging Holding Company, Sonoco, Mondi, Berry Global, and Sealed Air. These companies focus on expanding product portfolios, improving material performance, and adopting sustainable manufacturing practices. They invest in smart packaging technologies, barrier films, and antimicrobial coatings to meet evolving end-user demands across food, pharma, and personal care industries. Players differentiate by offering solutions that combine durability, recyclability, and active functionalities. Strategic acquisitions, global partnerships, and R&D investments enhance their market reach and innovation pipeline. Companies also strengthen supply chains and digital printing capabilities to meet demand for short-run, customizable formats. Sustainability goals and compliance with regional packaging regulations drive product reformulations across portfolios. Players leverage automation and multilayer extrusion to achieve cost efficiency without compromising packaging functionality. The competition intensifies as regional manufacturers enter the market with bio-based, cost-effective alternatives targeting niche applications.
Recent Developments
- In 2024, Amcor announced showcasing innovative packaging and machinery solutions at IPPE 2025 (Jan 2025), highlighting advancements designed to enhance operational efficiency and safety in protein processing, including AI-powered customized bag sizes, on-demand print capabilities, and smart merging technology.
- In 2024, Berry Global collaborated with VOID Technologies to commercialize a new high-performance polyethylene film for pet food packaging, optimized for recyclability and durability.
- In 2024, Mondi launched IntegoBag, a paper bag using functional barrier coating instead of free film, reducing plastic content by up to 50%
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily due to rising demand for shelf-stable and safe packaged products.
- Food, pharmaceutical, and cosmetics sectors will continue driving innovation in active and smart packaging.
- Brands will invest more in digital printing and interactive packaging to boost customer engagement.
- Flexible packaging formats will expand faster due to cost efficiency and ease of transport.
- Biodegradable and recyclable materials will gain strong traction amid tightening sustainability regulations.
- Use of RFID tags, QR codes, and sensors will rise in retail, logistics, and healthcare packaging.
- Asia Pacific will see faster adoption with increasing urbanization and e-commerce penetration.
- Regulatory compliance and safety standards will push global companies toward advanced packaging formats.
- Investment in nanotechnology and functional coatings will improve material performance and shelf life.
- Public-private initiatives will support R&D and infrastructure for smart, circular packaging solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Extended Shelf Life and Food Safety
Food manufacturers are increasingly adopting multifunctional packaging with barrier layers and antimicrobial agents to extend shelf life and reduce spoilage, meeting regulatory requirements and consumer expectations for freshness and safety.
Smart Packaging and Traceability in Healthcare and Pharma
Pharmaceutical and healthcare sectors require packaging that ensures product integrity, traceability, and tamper evidence, driving adoption of smart features like RFID tags, QR codes, and real-time condition monitoring.
Sustainability Regulations and Eco-Friendly Packaging
Stringent regulations and consumer demand for sustainable packaging are pushing manufacturers to develop recyclable, compostable, and bio-based multifunctional packaging solutions, especially in Europe and North America.
Growth of E-Commerce and Direct-to-Consumer Channels
The expansion of online retail and direct-to-consumer models increases the need for durable, tamper-evident, and interactive packaging that protects products during transit and enhances customer experience.
Technological Advancements in Functional Coatings and Sensors
Innovations in nanotechnology, printed electronics, and smart coatings enable packaging to offer enhanced protection, spoilage detection, and interactive features, making multifunctional packaging more attractive and scalable across industries.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Multifunctional Packaging market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Multifunctional Packaging Market projected to grow between 2025 and 2032?
Which Multifunctional Packaging market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Multifunctional Packaging market?
Who are the leading companies in the Multifunctional Packaging Market?
Which region commanded the largest share of the Multifunctional Packaging market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Food & Beverages
- 1.2.2 Pharmaceuticals
- 1.2.3 Personal Care & Cosmetics
- 1.2.4 Electronics
- 1.2.5 Industrial
- 1.2.6 Others
- 1.3 By Product Type
- 1.3.1 Flexible Packaging
- 1.3.2 Rigid Packaging
- 1.4 By Material Type
- 1.4.1 Plastics
- 1.4.2 Paper & Paperboard
- 1.4.3 Metals
- 1.4.4 Glass
- 1.4.5 Biodegradable Materials
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12.74 billion → 2032: USD 17.3 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Multifunctional Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Multifunctional Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Multifunctional Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Multifunctional Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Multifunctional Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Multifunctional Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Multifunctional Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Multifunctional Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12.74 billion → 2032: USD 17.3 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Multifunctional Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Food & Beverages
- 12.3.7.2 Pharmaceuticals
- 12.3.7.3 Personal Care & Cosmetics
- 12.3.7.4 Electronics
- 12.3.7.5 Industrial
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Flexible Packaging
- 12.4.7.2 Rigid Packaging
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Plastics
- 12.5.7.2 Paper & Paperboard
- 12.5.7.3 Metals
- 12.5.7.4 Glass
- 12.5.7.5 Biodegradable Materials
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Multifunctional Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Multifunctional Packaging Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Multifunctional Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Multifunctional Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amcor
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mondi
- 18.4 Berry Global
- 18.5 Westrock
- 18.6 Sealed Air
- 18.7 Schur Flexibles
- 18.8 Ball Corporation
- 18.9 Graphic Packaging Holding Company
- 18.10 Sonoco
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

