
Market Overview
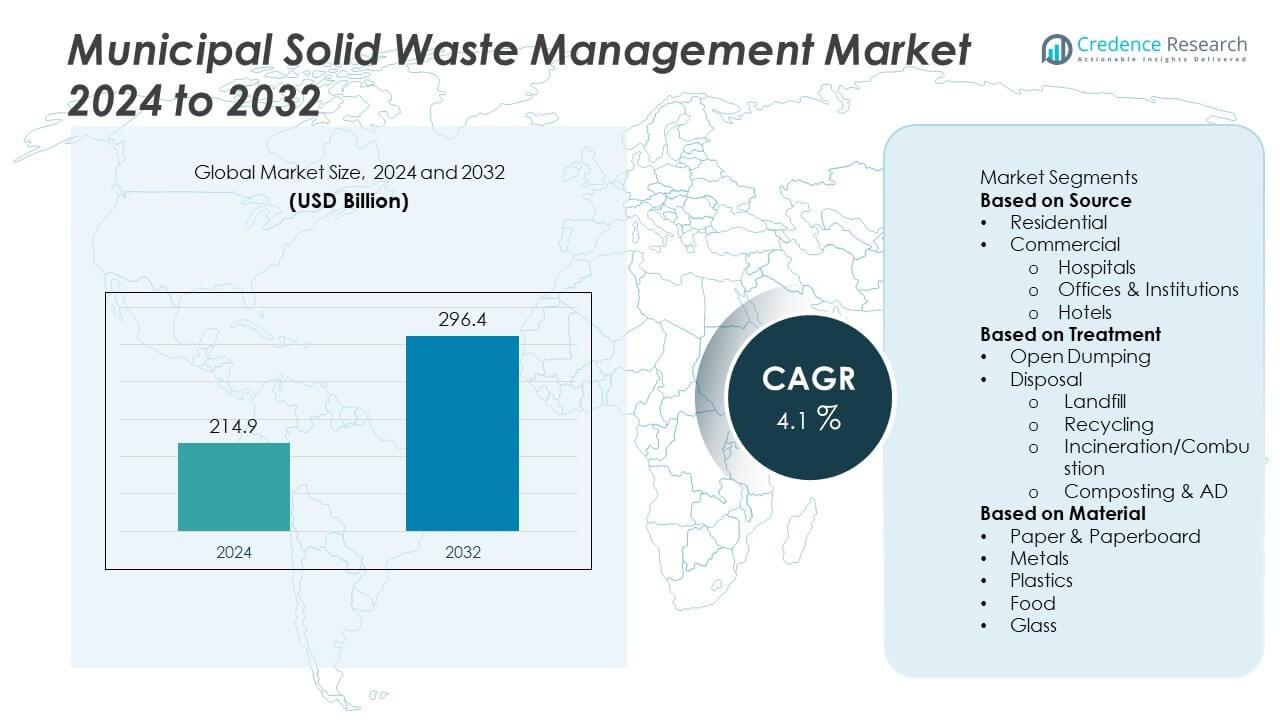
The Municipal Solid Waste Management Market size was valued at USD 214.9 billion in 2024 and is projected to reach USD 296.4 billion by 2032, growing at a CAGR of 4.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Municipal Solid Waste Management Market Size 2024 | USD 214.9 Billion |
| Municipal Solid Waste Management Market, CAGR | 4.1% |
| Municipal Solid Waste Management Market Size 2032 | USD 296.4 Billion |
The Municipal Solid Waste Management Market advances through strong drivers such as rapid urbanization, rising waste volumes, and stricter environmental regulations that push municipalities toward sustainable practices. It gains support from government initiatives promoting recycling, composting, and waste-to-energy adoption, while public-private partnerships enhance infrastructure efficiency.
The Municipal Solid Waste Management Market demonstrates a broad geographical footprint, shaped by varying regulatory frameworks, infrastructure maturity, and urbanization levels across regions. North America leads with advanced recycling systems, strong policy support, and widespread adoption of waste-to-energy technologies. Europe emphasizes circular economy practices, strict landfill restrictions, and high recycling efficiency, supported by progressive environmental directives. Asia-Pacific emerges as the fastest-evolving region, driven by rapid urban growth, government-backed initiatives, and rising investments in smart waste management solutions. Latin America and the Middle East & Africa show steady progress with modernization programs and increasing private sector participation. Key players shaping the market include China Everbright Environment Group, a leader in waste-to-energy projects, Clean Harbors, known for comprehensive environmental and waste services, Recology, recognized for community-focused recycling programs, and GFL Environmental, which strengthens its presence with integrated collection, treatment, and disposal solutions.
Market Insights
- The Municipal Solid Waste Management Market was valued at USD 214.9 billion in 2024 and is projected to reach USD 296.4 billion by 2032, expanding at a CAGR of 4.1%.
- The market grows through rising urbanization, increasing waste volumes, and government initiatives that enforce stricter environmental compliance and promote sustainable management systems.
- Key trends highlight the adoption of digital solutions such as IoT-enabled bins, AI-powered sorting, and route optimization platforms, alongside growing emphasis on circular economy practices.
- Competition remains strong, with leading players such as China Everbright Environment Group, Recology, GFL Environmental, and Clean Harbors investing in recycling infrastructure, waste-to-energy plants, and smart monitoring technologies.
- The market faces restraints in the form of high operational costs, inadequate infrastructure in emerging economies, and low public participation in source segregation, which limit large-scale adoption.
- North America and Europe dominate with advanced recycling systems and stringent regulatory frameworks, while Asia-Pacific experiences rapid growth through urban expansion and government-backed initiatives.
- Latin America and the Middle East & Africa gradually modernize through international funding, public-private partnerships, and investments in waste-to-energy and composting solutions, creating long-term growth opportunities.
Market Drivers
Rising Urbanization and Population Growth Driving Demand for Efficient Waste Handling
The Municipal Solid Waste Management Market grows steadily with rapid urbanization and population expansion across developed and developing regions. Higher population density generates greater household, commercial, and industrial waste volumes. Urban centers require modern collection, segregation, and disposal systems to prevent public health risks and environmental degradation. Governments and municipalities prioritize investment in infrastructure and integrated systems to keep pace with the mounting pressure. Public-private partnerships strengthen service delivery through advanced logistics and sustainable disposal practices. The growing urban middle class reinforces expectations for hygienic waste management solutions.
- For instance, Recology processes more than 1.5 million tons of recyclable and compostable material annually across its operations in the United States, demonstrating the scale required to manage rising urban waste volumes.
Increasing Focus on Environmental Regulations and Sustainability Standards
Governments across the globe enforce stringent environmental standards to minimize landfill use and control greenhouse gas emissions. The Municipal Solid Waste Management Market benefits from regulatory frameworks that mandate recycling, waste-to-energy adoption, and extended producer responsibility. It supports sustainable development by promoting circular economy practices and resource recovery. Strict compliance requirements push municipalities to implement advanced sorting, composting, and treatment technologies. International agreements on climate action and carbon neutrality encourage faster adoption of eco-friendly processes. Companies in the sector align with these goals to ensure long-term operational viability.
- For instance, China Everbright Environment Group operates more than 200 waste-to-energy projects with a combined daily processing capacity exceeding 160,000 tonnes, significantly reducing landfill reliance while complying with strict emission standards.
Technological Advancements in Recycling, Treatment, and Waste-to-Energy Solutions
The Municipal Solid Waste Management Market experiences transformation through innovations in smart bins, automated collection systems, and AI-driven sorting. It strengthens efficiency by reducing manual intervention and optimizing operational costs. Waste-to-energy facilities expand capacity to convert non-recyclable waste into electricity and heat, supporting renewable energy goals. Advanced recycling technologies improve recovery of plastics, metals, and electronic waste with higher precision. Data analytics and IoT solutions help monitor collection routes, reduce inefficiencies, and improve compliance reporting. Continuous innovation attracts investments from both governments and private operators.
Rising Public Awareness and Shifting Consumer Preferences Toward Sustainable Practices
The Municipal Solid Waste Management Market expands with rising public awareness of sustainability and ecological responsibility. It gains momentum as consumers demand recycling services, reduced plastic usage, and environmentally responsible practices. Educational initiatives and awareness campaigns influence behavioral change in urban households. Businesses adopt sustainable packaging, while communities participate in source segregation of biodegradable and recyclable materials. Municipalities respond to public pressure by enhancing transparency and accountability in waste management systems. Growing citizen participation ensures stronger adoption of efficient waste management models.
Market Trends
Growing Adoption of Waste-to-Energy Facilities to Support Renewable Energy Goals
The Municipal Solid Waste Management Market advances with the expansion of waste-to-energy plants that convert non-recyclable waste into electricity and heat. It enables municipalities to reduce landfill dependence while addressing rising energy demands. Governments support the deployment of these facilities through policy incentives and funding programs. The trend aligns with global commitments to expand renewable energy capacity and reduce greenhouse gas emissions. Companies in the sector invest in modern incineration, gasification, and anaerobic digestion technologies to maximize energy recovery. This approach integrates environmental sustainability with economic efficiency.
- For instance, Keppel Seghers is part of Hong Kong’s Integrated Waste Management Facility, which will process 3,000 tonnes of municipal solid waste per day and generate 480 million kWh of electricity annually once operational.
Integration of Digital Technologies and Smart Waste Solutions for Operational Efficiency
The Municipal Solid Waste Management Market embraces IoT-enabled bins, automated route optimization, and AI-powered sorting technologies. It enhances collection efficiency, reduces operational costs, and improves service reliability. Data-driven platforms allow municipalities to track waste volumes, predict collection schedules, and maintain real-time monitoring. Smart technologies provide transparency to citizens and strengthen accountability for waste services. Advanced analytics support better decision-making in recycling, treatment, and disposal. This trend accelerates adoption of digital infrastructure across urban waste management systems.
- For instance, GFL Environmental deployed over 3,000 smart bins equipped with IoT sensors across Canadian municipalities in 2023, enabling real-time monitoring and reducing unnecessary collection trips by more than 15 million kilometers annually.
Expanding Circular Economy Practices and Resource Recovery Initiatives
The Municipal Solid Waste Management Market gains momentum through practices that extend the lifecycle of materials and reduce raw material dependence. It emphasizes recycling, composting, and recovery of valuable resources from electronic and plastic waste. Companies adopt sustainable packaging, while governments introduce extended producer responsibility regulations. Municipalities strengthen segregation practices to improve recycling rates and minimize landfill use. Circular economy initiatives contribute to reduced environmental impact and support global sustainability goals. Investment in material recovery facilities highlights the growing importance of resource efficiency.
Rising Collaboration Between Public and Private Stakeholders to Improve Infrastructure
The Municipal Solid Waste Management Market evolves through partnerships that address infrastructure gaps in waste collection, transportation, and treatment. It benefits from joint ventures, concession models, and investment in modern facilities. Municipalities rely on private operators to deliver advanced technologies and operational expertise. Public participation in funding and awareness programs ensures community involvement in sustainable waste management. International organizations promote collaboration to improve waste systems in emerging economies. This trend drives consistent improvements in service delivery and accelerates modernization across regions.
Market Challenges Analysis
High Operational Costs and Limited Infrastructure in Developing Regions
The Municipal Solid Waste Management Market faces significant challenges from high collection, transportation, and treatment costs. It struggles with limited infrastructure in emerging economies where waste volumes rise faster than system capacity. Many municipalities depend on outdated equipment and underfunded facilities that cannot meet modern efficiency or environmental standards. Budget constraints restrict adoption of advanced recycling and waste-to-energy technologies. Rural and semi-urban areas often lack organized collection networks, creating inefficiencies and uncontrolled dumping. This gap in resources and infrastructure slows the pace of sustainable waste management practices.
Regulatory Complexity and Low Public Participation in Waste Segregation
The Municipal Solid Waste Management Market also encounters difficulties in managing diverse regulatory frameworks and compliance requirements across regions. It must adapt to varying policies on landfill use, recycling quotas, and emissions control, which creates operational hurdles. Public participation in source segregation remains low, limiting the effectiveness of recycling and composting initiatives. Inconsistent awareness campaigns fail to drive lasting behavioral change in many communities. Informal waste handling practices persist, undermining formal systems and reducing efficiency. These challenges emphasize the need for stronger collaboration between regulators, municipalities, and citizens to achieve long-term sustainability goals.
Market Opportunities
Expansion of Waste-to-Energy Projects and Advanced Recycling Technologies
The Municipal Solid Waste Management Market creates strong opportunities through investments in waste-to-energy and high-efficiency recycling technologies. It supports governments and private operators seeking to reduce landfill dependency while generating renewable energy. Growing interest in advanced incineration, pyrolysis, and anaerobic digestion expands the potential for energy recovery from non-recyclable waste. Recycling innovations in plastics, e-waste, and metals enable higher material recovery rates and cost efficiency. These opportunities align with global sustainability goals and climate commitments. Increased funding from both international organizations and local authorities reinforces the momentum for modern infrastructure deployment.
Rising Potential in Emerging Economies and Smart Waste Management Solutions
The Municipal Solid Waste Management Market holds significant opportunities in rapidly urbanizing economies where infrastructure modernization remains a priority. It addresses the growing demand for organized collection, segregation, and treatment systems across Asia-Pacific, Africa, and Latin America. Adoption of IoT-enabled bins, route optimization platforms, and AI-driven sorting enhances service efficiency and transparency. Municipalities explore digital platforms that allow real-time monitoring and citizen participation. Stronger public-private partnerships in these regions create avenues for long-term investment and technological integration. The push for smart and sustainable cities amplifies demand for scalable waste management solutions.
Market Segmentation Analysis:
By Source
The Municipal Solid Waste Management Market classifies waste sources into residential, commercial, and industrial sectors. Residential areas generate a large share of waste through food scraps, packaging materials, plastics, and paper products. It requires regular collection services and community-level segregation practices to maintain efficiency. Commercial establishments such as retail outlets, offices, and restaurants contribute through paper, plastics, and food waste that need systematic disposal. Industrial sources add to the complexity with bulk quantities of non-hazardous materials, often requiring specialized handling. Growth in urbanization and rising consumption patterns reinforce demand for effective waste management across all sources.
- For instance, Biffa in the UK manages waste from over 76,000 business customers and collects more than 4 million tonnes of municipal and commercial waste annually, ensuring coverage across residential and industrial sectors.
By Treatment
The Municipal Solid Waste Management Market segments treatment processes into collection, recycling, incineration, composting, and landfilling. Collection remains the first critical step, supported by advanced logistics and digital monitoring systems. Recycling strengthens its share as governments and businesses prioritize material recovery and circular economy practices. Incineration and waste-to-energy methods expand rapidly, addressing energy needs while reducing landfill dependency. Composting gains attention with rising demand for sustainable agricultural practices and organic waste utilization. Landfills continue to serve as a last resort, though stricter regulations push municipalities toward more sustainable alternatives. It reflects a global shift toward environmentally responsible treatment solutions.
- For instance, Cleanaway in Australia operates more than 100 recycling and resource recovery facilities, including organics processing sites capable of treating over 300,000 tonnes of food and garden waste annually, converting it into compost and renewable energy feedstock.
By Material
The Municipal Solid Waste Management Market categorizes materials into paper, plastics, metals, glass, food, and others. Paper and cardboard maintain a strong position with high recycling rates supported by established collection channels. Plastics pose significant challenges due to their environmental impact, yet advanced recycling technologies create new opportunities for recovery. Metals and glass contribute consistently, with high potential for reuse in industrial applications. Food waste accounts for a substantial portion, encouraging expansion of composting and anaerobic digestion facilities. Other materials, including textiles and e-waste, add diversity and require specialized recycling systems. It highlights the need for integrated approaches to address the varied material composition of urban waste.
Segments:
Based on Source
- Residential
- Commercial
- Hospitals
- Offices & Institutions
- Hotels
Based on Treatment
- Open Dumping
- Disposal
- Landfill
- Recycling
- Incineration/Combustion
- Composting & AD
Based on Material
- Paper & Paperboard
- Metals
- Plastics
- Food
- Glass
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds a significant share of the Municipal Solid Waste Management Market, accounting for 34% of the global market in 2024. Strong regulatory frameworks, advanced infrastructure, and high public awareness contribute to the region’s leadership. The United States generates more than 292 million tons of municipal solid waste annually, with nearly 32% directed to recycling and composting programs. Canada complements the market with nationwide recycling policies and landfill diversion targets. It benefits from robust investment in waste-to-energy plants, digital monitoring solutions, and public-private partnerships that improve operational efficiency. Growing emphasis on sustainability and stricter emission control regulations further encourage adoption of advanced recycling and treatment technologies. Continuous technological innovation positions North America as a mature and reliable market for sustainable waste management practices.
Europe
Europe represents 28% of the Municipal Solid Waste Management Market in 2024, supported by strict environmental directives and well-developed recycling infrastructure. Countries such as Germany, Sweden, and the Netherlands demonstrate world-leading recycling rates exceeding 50%. The European Union enforces stringent regulations on landfill use, promoting circular economy initiatives and extended producer responsibility programs. It drives demand for composting, anaerobic digestion, and advanced sorting technologies. Public awareness of ecological responsibility supports efficient source segregation across households and commercial establishments. Investment in modern incineration plants with energy recovery enhances the region’s waste-to-energy capacity. Europe’s consistent focus on regulatory compliance and innovation sustains its strong market presence.
Asia-Pacific
Asia-Pacific commands 24% of the Municipal Solid Waste Management Market in 2024, with rapid urbanization and industrialization driving demand for organized systems. China generates over 235 million tons of municipal waste annually, supported by national policies promoting recycling and waste-to-energy adoption. India follows with strong government-backed initiatives such as Swachh Bharat Mission, which encourages segregation and infrastructure expansion in urban centers. Japan and South Korea maintain advanced recycling frameworks with high recovery rates of plastics, metals, and food waste. It benefits from rising investments in smart waste collection, IoT-enabled monitoring, and large-scale composting facilities. Growing environmental awareness and urban population growth further reinforce Asia-Pacific’s position as the fastest-growing regional market.
Latin America
Latin America accounts for 8% of the Municipal Solid Waste Management Market in 2024, with demand driven by urbanization and government initiatives to modernize infrastructure. Brazil leads the region, producing more than 79 million tons of municipal waste annually, followed by Mexico and Argentina. It faces challenges from limited recycling infrastructure and heavy reliance on landfills, yet opportunities arise from public-private partnerships and international funding. Governments implement stricter landfill management policies and promote selective collection programs to boost recycling rates. Community-driven initiatives play a growing role in improving waste segregation and reducing informal waste handling. Rising investments in composting and waste-to-energy projects support gradual modernization of the region’s waste management systems.
Middle East and Africa
The Middle East and Africa hold 6% of the Municipal Solid Waste Management Market in 2024, with rising urbanization and infrastructure expansion creating demand for efficient solutions. The United Arab Emirates and Saudi Arabia invest heavily in waste-to-energy projects to reduce landfill dependency and meet sustainability goals. South Africa and Nigeria represent emerging markets where inadequate collection infrastructure and limited recycling capacity remain challenges. It benefits from international collaboration and government-led initiatives that encourage modernization and private sector participation. The region witnesses growing adoption of digital platforms for monitoring and smart city waste management programs. Long-term opportunities emerge from expanding population bases and the urgent need for sustainable solutions to address rising waste volumes.
Key Player Analysis
- Keppel Seghers
- Recology
- China Everbright Environment Group
- OMNI Conversion Technologies
- Cleanaway
- GFL Environmental
- Hitachi Zosen
- L. Harvey
- Biffa
- Clean Harbors
Competitive Analysis
The competitive landscape of the Municipal Solid Waste Management Market is shaped by leading players such as China Everbright Environment Group, Biffa, Recology, Cleanaway, Clean Harbors, GFL Environmental, Hitachi Zosen, Keppel Seghers, OMNI Conversion Technologies, and E.L. Harvey, which drive industry growth through technological innovation, service diversification, and sustainable operations. Strategic investments in waste-to-energy facilities, advanced recycling technologies, and digital waste monitoring solutions strengthen efficiency and regulatory compliance. Market reach is further expanded through partnerships and acquisitions, enabling enhanced service capabilities across urban and industrial waste streams. A strong focus on sustainable practices such as resource recovery, composting, and reduced landfill dependency aligns with circular economy principles. Continuous innovation combined with regional expansion underpins competitive intensity and supports long-term growth in the sector.
Recent Developments
- In August 2025, China Everbright Environment Group announced (interim 1H results) that it secured three new projects totaling RMB 2.336 billion investments, adding a daily household waste processing capacity of 3,000 tonnes.
- In June 2025, Biffa reached the halfway point of a hazardous waste removal project at the former Ratcliffe-on-Soar power station deploying specialists to support decommissioning efforts.
- In June 2025, Biffa secured a contract for waste, recycling, and street cleaning services in Wokingham Borough Council.
- In June 2025, Recology released its 2025 Sustainability Update reporting the processing of 1.5 million tons of recyclable and compostable material and the avoidance of 1.7 million metric tons.
Report Coverage
The research report offers an in-depth analysis based on Source,Treatment,Material and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Urban regions drive continued demand for scalable, efficient waste management systems.
- Governments expand incentives for recycling and waste-to-energy projects.
- Investment growth targets smart waste technologies like IoT monitoring and AI sorting.
- Waste-to-energy facilities play a larger role in integrating energy recovery with disposal strategies.
- Circular economy principles shape packaging, recycling, and material reuse frameworks.
- Public-private partnerships deliver modern infrastructure and build resilience.
- Consumer awareness prompts stronger source segregation and sustainable behavior.
- Emerging economies accelerate modernization of collection and treatment networks.
- Regulatory frameworks evolve toward stricter landfill restrictions and resource recovery targets.
- Mergers, acquisitions, and strategic alliances fuel expansion and drive innovation.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Urbanization and Population Growth
Rapid urbanization and expanding populations in both developed and emerging economies are generating higher volumes of municipal solid waste, necessitating investment in modern collection, segregation, and disposal systems to maintain public health and environmental standards.
Stringent Environmental Regulations and Sustainability Standards
Governments are enforcing stricter regulations on landfill use, emissions, and recycling, pushing municipalities and private operators to adopt advanced recycling, composting, and waste-to-energy technologies to comply with sustainability goals and reduce environmental impact.
Technological Advancements in Waste Management
The adoption of IoT-enabled bins, AI-powered sorting, and route optimization platforms is transforming operational efficiency, reducing manual intervention, and enabling better monitoring and reporting, which supports the scaling of sustainable waste management practices.
Expansion of Waste-to-Energy and Circular Economy Initiatives
Growing investment in waste-to-energy facilities and circular economy practices is reducing landfill dependency while supporting renewable energy targets and resource recovery, aligning with global climate commitments and creating new revenue streams for operators.
Increasing Public Awareness and Participation
Rising consumer demand for recycling, reduced plastic use, and sustainable practices, supported by educational campaigns and community initiatives, is driving municipalities to enhance transparency, accountability, and adoption of efficient waste management models.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Municipal Solid Waste Management, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Municipal Solid Waste Management market projected to grow between 2025 and 2032?
Which Municipal Solid Waste Management market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Municipal Solid Waste Management market?
Who are the leading companies in the Municipal Solid Waste Management market?
Which region commanded the largest share of the Municipal Solid Waste Management market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Source
- 1.2.1 Residential
- 1.2.2 Commercial (Hospitals, Offices & Institutions, Hotels)
- 1.2.3 Industrial
- 1.3 By Material
- 1.3.1 Paper & Paperboard
- 1.3.2 Plastics
- 1.3.3 Metals
- 1.3.4 Food
- 1.3.5 Glass
- 1.3.6 Others (e-waste, textiles)
- 1.4 By Treatment
- 1.4.1 Landfill
- 1.4.2 Recycling
- 1.4.3 Incineration/Combustion
- 1.4.4 Composting & Anaerobic Digestion
- 1.4.5 Open Dumping
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 214.9 billion → 2032: USD 296.4 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Municipal Solid Waste Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Municipal Solid Waste Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Municipal Solid Waste Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Municipal Solid Waste Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Municipal Solid Waste Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Municipal Solid Waste Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Municipal Solid Waste Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Municipal Solid Waste Management Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 214.9 billion → 2032: USD 296.4 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Municipal Solid Waste Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Source - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential
- 12.3.7.2 Commercial (Hospitals, Offices & Institutions, Hotels)
- 12.3.7.3 Industrial
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Paper & Paperboard
- 12.4.7.2 Plastics
- 12.4.7.3 Metals
- 12.4.7.4 Food
- 12.4.7.5 Glass
- 12.4.7.6 Others (e-waste, textiles)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Treatment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Landfill
- 12.5.7.2 Recycling
- 12.5.7.3 Incineration/Combustion
- 12.5.7.4 Composting & Anaerobic Digestion
- 12.5.7.5 Open Dumping
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Municipal Solid Waste Management Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Municipal Solid Waste Management Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Municipal Solid Waste Management Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 China Everbright Environment Group
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Recology
- 17.4 GFL Environmental
- 17.5 Clean Harbors
- 17.6 Biffa
- 17.7 Cleanaway
- 17.8 Keppel Seghers
- 17.9 Hitachi Zosen
- 17.10 OMNI Conversion Technologies
- 17.11 E.L. Harvey
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

