
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Netherlands Gastrointestinal Products Market Size 2023 | USD 129.17 million |
| Netherlands Gastrointestinal Products Market, CAGR | 4.82% |
| Netherlands Gastrointestinal Products Market Size 2032 | USD 197.38 million |
Market Overview
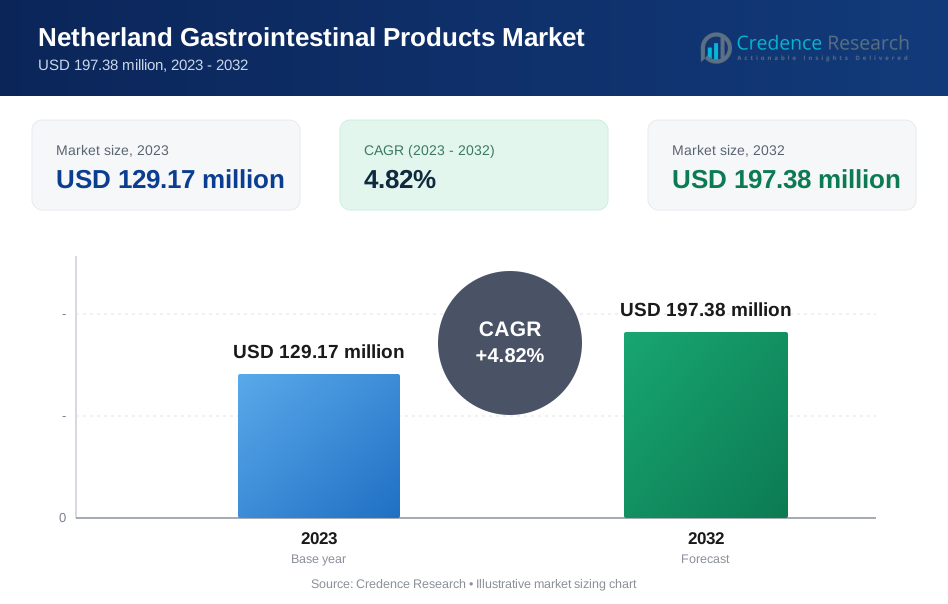
The Netherlands Gastrointestinal Products Market is expected to grow from USD 129.17 million in 2023 to USD 197.38 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.82%.
The Netherlands gastrointestinal products market is driven by the increasing prevalence of gastrointestinal disorders, rising healthcare awareness, and advancements in medical treatments. The growing demand for effective treatments for conditions like IBS, acid reflux, and Crohn’s disease is fueling market growth. Additionally, the aging population in the Netherlands is contributing to a higher incidence of digestive issues, further boosting product demand. Technological innovations in gastrointestinal therapeutics, such as targeted drug delivery systems and biologics, are also shaping market trends. The adoption of minimally invasive procedures and improved diagnostics is enhancing treatment options, leading to a higher patient satisfaction rate. Furthermore, the focus on personalized medicine and growing healthcare investments by the government and private sector are key trends accelerating market expansion. These factors, along with a rising awareness of preventive healthcare, are expected to continue driving the Netherlands gastrointestinal products market forward.
The Netherlands gastrointestinal products market benefits from a robust healthcare infrastructure and a growing demand for advanced diagnostic and therapeutic solutions. Geographically, the country is a significant player in the Western European market, with increasing investments in medical technologies and a rising prevalence of gastrointestinal disorders. Key players in the market include SynMed, Penlon, Micro-Tech UK, and Medtronic, alongside other prominent companies like Ethicon Endo-Surgery, Stryker, and Smith & Nephew. These companies contribute to the development and distribution of innovative gastrointestinal products, including endoscopy devices, ablation technologies, and biologic therapies. The presence of leading global players in the Netherlands supports the growth of both preventive and therapeutic solutions, driving market expansion through the introduction of advanced diagnostic tools and minimally invasive treatments. This dynamic landscape of key players and healthcare innovation positions the Netherlands as a strong market for gastrointestinal products in the region.
Market Insights
- The Netherlands gastrointestinal products market was valued at USD 129.17 million in 2023 and is projected to reach USD 197.38 million by 2032, growing at a CAGR of 4.82%.
- Increasing prevalence of gastrointestinal disorders, such as IBS and GERD, is driving the demand for advanced diagnostic and therapeutic solutions.
- The growing adoption of minimally invasive surgeries and diagnostic tools is shaping market trends, with a focus on early detection and treatment.
- Key players like Medtronic, SynMed, and Stryker are innovating to capture market share, intensifying competition in the region.
- High product costs and stringent regulatory approvals are key market restraints that could limit the growth of new products.
- The market is expanding in Western Europe, supported by strong healthcare infrastructure and rising healthcare investments.
- Emerging markets in Eastern and Southern Europe present growth opportunities, driven by improving healthcare access and increasing disease awareness.
Market Drivers
Rising Prevalence of Gastrointestinal Disorders
The increasing incidence of gastrointestinal (GI) disorders in the Netherlands is one of the primary drivers for the growth of the gastrointestinal products market. Conditions such as irritable bowel syndrome (IBS), acid reflux, Crohn's disease, and gastroesophageal reflux disease (GERD) are becoming more prevalent due to lifestyle changes, dietary habits, and an aging population. For instance, a study by the Dutch Stomach, Liver and Bowel Foundation revealed that nearly one in four people in the Netherlands had visited their general practitioner for stomach, liver, and bowel problems. As more individuals seek effective treatment solutions, there is a growing demand for innovative gastrointestinal products that address these chronic conditions.
Aging Population and Changing Demographics
The aging population in the Netherlands is significantly contributing to the market’s growth. Older adults are more prone to developing gastrointestinal issues, such as constipation, dyspepsia, and colorectal cancer. For instance, data from the Central Bureau voor de Statistiek (CBS) indicates that the proportion of residents aged 65 or older has increased significantly, representing a substantial portion of the population. As the population continues to age, the demand for gastrointestinal products, including medications, supplements, and diagnostic tools, is expected to rise. This demographic shift creates long-term growth potential for the gastrointestinal products market in the region.
Advancements in Treatment and Technology
Technological innovations and advancements in gastrointestinal treatments are playing a key role in driving market growth. New drug formulations, biologics, and minimally invasive surgical procedures are revolutionizing the way GI disorders are treated. Furthermore, advancements in diagnostic technologies, such as endoscopy and capsule endoscopy, have made it easier to identify gastrointestinal conditions early, leading to better patient outcomes. These innovations are enhancing the efficacy of treatments and attracting more patients to seek advanced gastrointestinal products.
Increased Healthcare Awareness and Preventive Care
Rising healthcare awareness and a growing emphasis on preventive care are also boosting the Netherlands gastrointestinal products market. As individuals become more informed about the importance of gut health, they are increasingly seeking preventive measures to manage digestive health. This trend is driving the demand for probiotics, dietary supplements, and other over-the-counter products. Additionally, the focus on personalized medicine, which tailors treatments to an individual’s genetic profile, is fostering a shift toward more effective and targeted gastrointestinal therapies.
Market Trends
Shift Towards Personalized Medicine
One of the key trends in the Netherlands gastrointestinal products market is the growing focus on personalized medicine. Advances in genomics and biotechnology have made it possible to tailor treatments to individual patients based on their genetic profiles and specific conditions. Personalized therapies, such as biologics and targeted drug treatments, are gaining traction due to their higher efficacy and fewer side effects compared to traditional therapies. For instance, the Personalized Medicine Research Program at Amsterdam UMC focuses on developing customized therapies based on genetic and phenotypic determinants. This trend is expected to continue driving demand for more sophisticated and customized gastrointestinal treatments in the Netherlands.
Rise in Preventive Healthcare and Self-Medication
Preventive healthcare is becoming a prominent trend in the Netherlands, with more individuals adopting proactive measures to maintain digestive health. This includes an increased demand for over-the-counter products such as probiotics, fiber supplements, and antacids, which are commonly used to manage minor digestive issues. Consumers are more focused on maintaining a healthy gut microbiome and preventing GI disorders, leading to a surge in the use of dietary supplements and non-prescription products. This trend reflects a broader shift towards self-medication and wellness, further boosting the gastrointestinal market.
Integration of Advanced Diagnostic Tools
The Netherlands gastrointestinal products market is also witnessing a growing trend toward the integration of advanced diagnostic tools. Technologies such as capsule endoscopy, smart endoscopes, and non-invasive breath tests are increasingly being used for the early detection of gastrointestinal conditions. These tools allow for more accurate and timely diagnoses, leading to better treatment outcomes. As healthcare providers adopt these advanced diagnostic technologies, the demand for related products and services is expected to rise, further contributing to the market's growth.
Emphasis on Minimally Invasive Treatments
Another significant trend in the market is the increasing preference for minimally invasive treatments. Procedures like endoscopic surgeries, laparoscopic techniques, and the use of biologics are gaining popularity due to their shorter recovery times, lower risks, and greater patient comfort. As more patients opt for less invasive treatment options, the demand for gastrointestinal products associated with these procedures, such as endoscopic instruments and biologic therapies, is expected to grow. This trend is reshaping the way gastrointestinal disorders are managed in the Netherlands.
Market Challenges Analysis
Regulatory and Reimbursement Challenges
One of the major challenges facing the Netherlands gastrointestinal products market is navigating the complex regulatory environment. The approval process for new gastrointestinal treatments, medical devices, and diagnostic tools can be time-consuming and costly, which may hinder the market entry of innovative products. For instance, the European Food Safety Authority (EFSA) has highlighted that the approval process for novel foods and medical products can take up to three years due to detailed safety assessments. Furthermore, reimbursement policies for these products are often restrictive, particularly for new therapies that are not yet widely recognized in clinical practice. This can limit patient access to cutting-edge treatments and slow the adoption of new gastrointestinal products. Companies must also ensure compliance with strict European Union (EU) regulations, which adds another layer of complexity to product development and commercialization in the Netherlands.
Market Competition and Price Pressure
The gastrointestinal products market in the Netherlands is highly competitive, with numerous domestic and international players vying for market share. This intense competition, coupled with rising pressure on healthcare budgets, leads to significant price sensitivity in the market. Companies must innovate to differentiate their products, but the constant need to maintain cost-effectiveness often limits their ability to invest in research and development. Additionally, the prevalence of generic drugs and low-cost alternatives intensifies price competition, which can undermine profitability for manufacturers. These challenges create a difficult market landscape, requiring companies to balance innovation with cost-efficiency to remain competitive while ensuring continued market growth.
Market Opportunities
Growth in Preventive and Wellness-Oriented Products
The growing consumer focus on preventive healthcare presents a significant opportunity for the Netherlands gastrointestinal products market. As awareness of digestive health and its link to overall well-being increases, there is rising demand for products that support gut health, such as probiotics, dietary supplements, and functional foods. This trend toward preventive care offers a vast market for over-the-counter gastrointestinal products aimed at improving digestion, managing symptoms, and maintaining a healthy gut microbiome. Companies that focus on developing and marketing wellness-oriented gastrointestinal products are well-positioned to capitalize on this expanding segment, catering to health-conscious consumers seeking natural and non-invasive solutions.
Technological Innovations and Treatment Advancements
Advancements in medical technologies and the development of innovative treatments present another key opportunity for the Netherlands gastrointestinal products market. The integration of minimally invasive techniques, biologic therapies, and advanced diagnostic tools, such as capsule endoscopy and smart endoscopes, is transforming gastrointestinal care. As these technologies continue to evolve, they open up new avenues for the development of effective treatments and early diagnosis of gastrointestinal disorders. Furthermore, the rise of personalized medicine, driven by genomic research, offers the potential for tailored therapies that provide more precise and effective solutions for patients. Manufacturers investing in these technological innovations will be able to meet the growing demand for advanced, patient-specific treatments, positioning themselves as leaders in the evolving gastrointestinal market.
Market Segmentation Analysis:
By Devices:
The Netherlands gastrointestinal products market can be segmented by devices into several key categories, each addressing specific needs in GI care. Endoscopy devices are pivotal for visualizing and diagnosing gastrointestinal disorders, with increasing adoption driven by the demand for minimally invasive diagnostic solutions. Ablation devices are gaining traction for treating GI cancers and other conditions, offering targeted therapies that minimize recovery times and reduce complications. Motility testing devices, essential for diagnosing disorders like IBS and GERD, are increasingly in demand due to their role in assessing gut function. Biopsy devices also play a crucial role, enabling the collection of tissue samples for diagnosing various GI diseases, including cancer. Finally, stenting devices are utilized to treat obstructions in the gastrointestinal tract, offering relief for conditions like esophageal cancer. These device segments are experiencing growth due to technological advancements and increasing prevalence of GI disorders.
By Indications:
The gastrointestinal products market in the Netherlands is also segmented based on indications, including gastrointestinal cancers, gastroesophageal reflux disease (GERD), irritable bowel syndrome (IBS), inflammatory bowel disease (IBD), and other GI diseases. Gastrointestinal cancers are one of the leading causes of demand for specialized devices and treatments, with increasing awareness driving early detection and treatment. GERD and IBS are widespread conditions that continue to grow in prevalence, particularly due to lifestyle changes, making them major contributors to the demand for therapeutic products. Inflammatory bowel disease (IBD), including Crohn’s disease and ulcerative colitis, is another significant segment, with patients requiring advanced therapies for long-term management. The "other diseases" segment includes a range of lesser-known conditions that also drive market demand. As the awareness and diagnosis of these conditions rise, so does the need for innovative and effective gastrointestinal products to manage and treat them.
Segments:
Based on Devices:
- Endoscopy Devices
- Ablation Devices
- Motility Testing Devices
- Biopsy Devices
- Stenting Devices
Based on Indications:
- Gastrointestinal Cancers
- Gastroesophageal Reflux Disease
- Irritable Bowel Syndrome
- Inflammatory Bowel Disease
- Other Diseases
Based on End-User:
- Hospitals
- Ambulatory Surgical Centers & Independent Surgical Centers
- Clinics
- Other End Users
Based on the Geography:
- Western Europe
- Northern Europe
- Southern Europe
- Eastern Europe
Regional Analysis
Western Europe
Western European gastrointestinal products market, with a market share of approximately 15%. This position is driven by the country's well-established healthcare infrastructure, high standards of medical care, and increasing demand for advanced diagnostic and therapeutic solutions for gastrointestinal disorders. The region benefits from a robust healthcare system that prioritizes early diagnosis and treatment, leading to higher patient awareness and adoption of innovative gastrointestinal products. Additionally, the increasing prevalence of gastrointestinal disorders, including IBS, GERD, and gastrointestinal cancers, further fuels the market's growth in the Netherlands. The rising healthcare expenditures and investments in advanced medical technologies, such as endoscopy and biopsy devices, are contributing to the expansion of the market in the region.
Northern Europe
Northern Europe, which includes countries such as Sweden, Denmark, Finland, and Norway, is another important region for the Netherlands gastrointestinal products market. The market share for this region stands at approximately 20%, supported by a growing demand for both preventive and therapeutic gastrointestinal solutions. The increasing prevalence of lifestyle-related gastrointestinal conditions, along with an aging population, has contributed to the expansion of the market. Furthermore, Northern European countries are known for their focus on innovative healthcare technologies, making them early adopters of advanced gastrointestinal devices. The healthcare systems in these countries emphasize research, development, and the integration of new medical technologies, creating opportunities for growth in the gastrointestinal market.
Southern Europe
In Southern Europe, which includes countries like Spain, Italy, and Portugal, the Netherlands gastrointestinal products market is witnessing steady growth, with a regional market share of approximately 18%. The demand for gastrointestinal products is driven by a combination of an aging population, rising healthcare awareness, and increasing rates of gastrointestinal diseases. Southern Europe has seen a shift toward minimally invasive surgical procedures and advanced diagnostic tools, such as endoscopy and motility testing devices. The growing healthcare expenditure in this region is further supporting the expansion of the gastrointestinal market. Additionally, the growing emphasis on preventive healthcare and digestive wellness products is creating new opportunities for product developers and manufacturers in the region.
Eastern Europe
Eastern Europe, including countries like Poland, Czech Republic, and Hungary, represents a growing market for gastrointestinal products with a regional share of around 12%. While still emerging, this market is expanding due to improvements in healthcare access, rising awareness of gastrointestinal disorders, and the increasing adoption of advanced medical technologies. The growing prevalence of gastrointestinal diseases, particularly in urban areas, is prompting demand for both diagnostic devices and therapeutic solutions. As healthcare infrastructure continues to improve and economic conditions in the region strengthen, the gastrointestinal products market is expected to see accelerated growth. Eastern Europe is becoming a key region for companies looking to expand their presence in the broader European market, driven by rising consumer demand for better healthcare products.
Key Player Analysis
- SynMed
- Penlon
- Micro-Tech UK
- Ethicon Endo-Surgery
- Medtronic
- Stryker
- Smith & Nephew
- Karl Storz
- Hoya
- Company 10
- Company 11
- Company 12
- Company 13
- Company 14
Competitive Analysis
The Netherlands gastrointestinal products market is highly competitive, with several leading players contributing to the development of innovative solutions. Key players in the market include SynMed, Penlon, Micro-Tech UK, Ethicon Endo-Surgery, Medtronic, Stryker, Smith & Nephew, Karl Storz, and Hoya. Companies in this market differentiate themselves through innovation, offering a wide range of products such as endoscopy devices, biopsy tools, ablation technologies, and biologic therapies. The emphasis on minimally invasive surgeries and early detection is driving competition, with firms investing heavily in research and development to create more efficient and cost-effective solutions. To gain a competitive edge, companies are focusing on expanding their product portfolios and adopting cutting-edge technologies. Many firms are also forming strategic partnerships and collaborations to enhance their market presence and broaden their reach. For example, the Netherlands Food Partnership (NFP) brings together organizations from various sectors to accelerate food system transitions, demonstrating the importance of strategic collaborations. As the demand for personalized treatments grows, competition intensifies, with companies seeking to integrate advanced diagnostic tools and patient-specific solutions into their offerings. Additionally, the focus on improving patient outcomes, reducing recovery times, and lowering healthcare costs further fuels competition in the Netherlands gastrointestinal products market. Companies that successfully innovate and meet these evolving market needs are poised for long-term success.
Recent Developments
- In April 2023, Boston Scientific announced the launch of the EXALT Model B Single-use Bronchoscope, which expands its single-use endoscopy portfolio. This device is designed for diagnostic and therapeutic bronchoscopy procedures and offers high-resolution imaging and precise control.
- In March 2023, Polifarma Spa expanded its gastrointestinal portfolio through a long-term distribution agreement with Devintec Pharma Sagl, a Lugano-based company known for pioneering substance-based medical devices and the Gelsectan brand.
- In April 2023, Italian pharmaceutical innovator Azienda Farmaceutica Italiana partnered with TannerLAC, Inc. to distribute Hepilor, a medical device designed to protect the digestive system mucosa, throughout Latin America.
- In May 2022, Dr. Reddy’s Laboratories Ltd. announced a partnership with South Korea’s HK inno.N Corporation to supply and commercialize HK inno.N’s patented novel molecule, Tegoprazan, for treating gastrointestinal diseases in India and six key emerging markets.
- In March 2022, AbbVie Inc. received U.S. FDA approval for its novel drug, RINVOQ (upadacitinib), for the treatment of moderately to severely active ulcerative colitis.
Market Concentration & Characteristics
The Netherlands gastrointestinal products market exhibits a moderate level of market concentration, with a few leading players dominating key segments such as diagnostic devices, minimally invasive surgery tools, and therapeutic solutions. While large multinational companies hold a significant market share, there is still room for smaller, specialized firms to innovate and cater to niche markets. The competitive landscape is characterized by a strong emphasis on technological advancements, as companies invest in research and development to create more efficient, user-friendly, and cost-effective products. This includes innovations in endoscopy devices, ablation technologies, and diagnostic tools for conditions like GERD, IBS, and gastrointestinal cancers. The market is marked by rapid adoption of minimally invasive procedures, which reduce recovery times and improve patient outcomes, creating demand for cutting-edge diagnostic and therapeutic devices. Companies are also focusing on integrating digital technologies, such as AI and smart diagnostics, into their products to enhance precision and provide more personalized treatments. Additionally, regulatory compliance and reimbursement policies play a significant role in shaping market dynamics, as companies must navigate complex approval processes to introduce new products. The Netherlands' strong healthcare infrastructure, coupled with increasing patient awareness and demand for advanced treatments, ensures steady market growth, although competition remains intense among established and emerging players.
Report Coverage
The research report offers an in-depth analysis based on Devices, Indications, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Netherlands gastrointestinal products market will benefit from continued advancements in diagnostic imaging and endoscopic procedures.
- Growing collaboration between healthcare providers and product manufacturers will enhance the availability of innovative treatments.
- Regulatory frameworks will evolve to accommodate new technologies, ensuring faster approval of innovative gastrointestinal devices.
- The aging population in the Netherlands will further drive demand for gastrointestinal products, particularly for chronic conditions.
- Digital health tools, including remote monitoring and telemedicine, will enhance patient management and expand market opportunities.
- The market will experience increased demand for biologic therapies to address complex gastrointestinal diseases such as IBD and colorectal cancer.
- Rising healthcare spending and investments in medical research will support market expansion and the development of cutting-edge solutions.
- Environmental sustainability concerns will drive innovation in eco-friendly packaging and manufacturing of gastrointestinal products.
- There will be a growing focus on improving accessibility to gastrointestinal treatments, especially for underserved populations.
- Consumer demand for natural and organic gastrointestinal solutions will push companies to develop alternative products targeting digestive wellness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Netherlands Gastrointestinal Products market?
What factors are driving the growth of the Netherlands Gastrointestinal Products market?
What are the key segments within the Netherlands Gastrointestinal Products market?
What are some challenges faced by the Netherlands Gastrointestinal Products market?
Who are the major players in the Netherlands Gastrointestinal Products market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Netherland Gastrointestinal Products Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Netherland Gastrointestinal Products Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 129.17 million → 2032: USD 197.38 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Netherland Gastrointestinal Products Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Netherland Gastrointestinal Products Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Netherland Gastrointestinal Products Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Netherland Gastrointestinal Products Market Drivers
- 3.3 Netherland Gastrointestinal Products Market Restraints & Challenges
- 3.4 Netherland Gastrointestinal Products Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Netherland Gastrointestinal Products Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Netherland Gastrointestinal Products Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Netherland Gastrointestinal Products category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Netherland Gastrointestinal Products Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Netherland Gastrointestinal Products Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Netherland Gastrointestinal Products market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Netherland Gastrointestinal Products Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Netherland Gastrointestinal Products Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Netherland Gastrointestinal Products Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Netherland Gastrointestinal Products (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Netherland Gastrointestinal Products Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Netherland Gastrointestinal Products Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Netherland Gastrointestinal Products Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Netherland Gastrointestinal Products Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Netherland Gastrointestinal Products Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Netherland Gastrointestinal Products Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Netherland Gastrointestinal Products Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Netherland Gastrointestinal Products Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Netherland Gastrointestinal Products Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
