
Market Overview
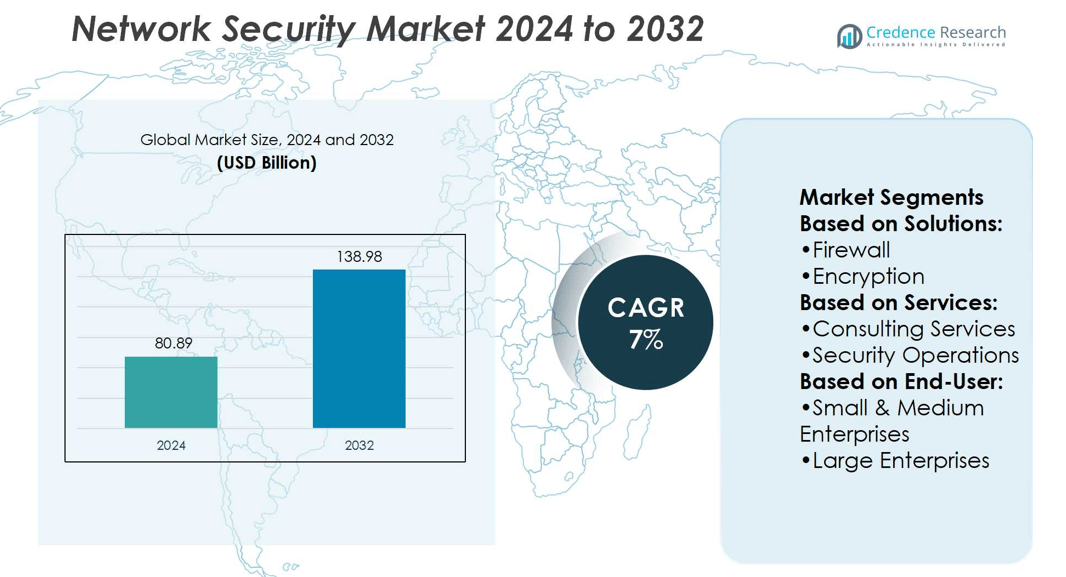
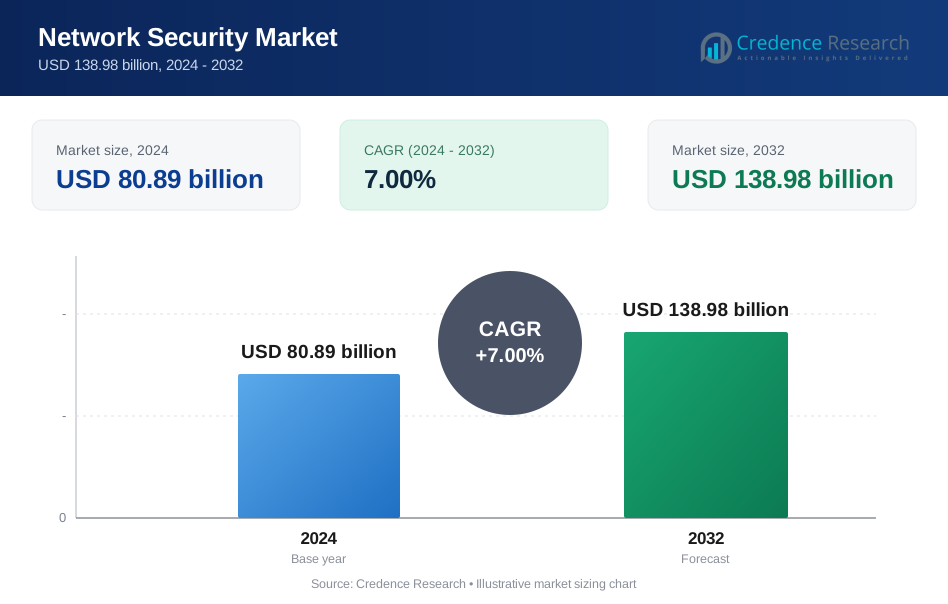
Network Security Market size was valued at USD 80.89 billion in 2024 and is anticipated to reach USD 138.98 billion by 2032, at a CAGR of 7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Network Security Market Size 2024 | USD 80.89 billion |
| Network Security Market CAGR | 7% |
| Network Security Market Size 2032 | USD 138.98 billion |
The Network Security Market grows strongly with rising cyber threats, regulatory compliance, and rapid cloud adoption. Enterprises invest in firewalls, intrusion detection, and identity management to secure expanding digital infrastructures. Remote work and hybrid environments intensify demand for zero-trust frameworks and managed security services. AI and machine learning integration improves threat detection, while automation enhances response efficiency. Cloud-native platforms and secure access solutions gain prominence with increasing reliance on distributed systems. Regulatory mandates reinforce adoption across sectors, while IoT and edge devices expand the scope of protection. Continuous innovation ensures the market evolves to meet complex and evolving security needs.
The Network Security Market shows strong geographical presence across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. North America leads with mature adoption, while Asia-Pacific records the fastest growth due to rapid digital transformation. Europe maintains steady demand under strict regulatory frameworks, and emerging regions expand with rising digitization. Competition remains intense with global players focusing on innovation and partnerships. Leading participants strengthen portfolios in cloud-native security, zero-trust models, and AI-driven solutions to capture wider market share.
Market Insights
- The Network Security Market size was valued at USD 80.89 billion in 2024 and is projected to reach USD 138.98 billion by 2032, at a CAGR of 7%.
- Rising cyber threats, strict compliance laws, and rapid cloud adoption drive steady market expansion.
- AI, machine learning, and automation enhance detection accuracy and accelerate incident response across industries.
- Market restraints include high infrastructure complexity and shortage of skilled cybersecurity professionals worldwide.
- North America leads in market share, while Asia-Pacific records the fastest growth due to digital transformation.
- Europe maintains consistent demand supported by GDPR, while Latin America and Middle East & Africa expand gradually.
- Competition stays intense with global players focusing on cloud-native platforms, zero-trust frameworks, and AI-driven security innovation.
Market Drivers
Rising Cybersecurity Threats Driving Adoption of Advanced Network Security Solutions
The Network Security Market expands with the increasing frequency and sophistication of cyberattacks. Enterprises face constant risks from ransomware, phishing, and distributed denial-of-service attacks. Rising digital connectivity across industries exposes networks to complex vulnerabilities. Organizations prioritize deploying next-generation firewalls, intrusion detection systems, and endpoint protection tools. Cloud adoption and remote work accelerate the need for secure access controls. It strengthens demand for integrated solutions that can adapt quickly to evolving threats.
- For instance, Aruba’s ESP platform supports management of over 5.2 million devices and handles more than 2 billion network services, all under consistent policy controls across deployment models including virtual private cloud and on-premises, preserving data sovereignty and regulatory alignment.
Regulatory Compliance and Data Protection Requirements Fueling Demand
Governments worldwide enforce strict regulations on data privacy and cybersecurity standards. The Network Security Market benefits from frameworks such as GDPR, HIPAA, and CCPA. These mandates require businesses to maintain robust protection for sensitive information. Industries like healthcare, banking, and telecom face higher pressure to invest in compliance-driven solutions. Network monitoring, encryption technologies, and identity access management gain prominence in meeting legal obligations. It ensures businesses remain compliant while building trust with customers.
- For instance, Ruckus’ SmartCell Insight platform stores up to 3 years of traffic data across 100,000 access points and millions of clients daily, enabling long-term compliance monitoring and analytics.
Growing Cloud Migration and Remote Work Intensifying Security Needs
Cloud services and hybrid work models create complex network environments. The Network Security Market responds with advanced tools for securing cloud workloads and remote endpoints. Traditional perimeter-based defense models struggle against distributed infrastructures. Secure access service edge (SASE) and zero-trust architectures emerge as vital solutions. Enterprises demand scalable, flexible, and cloud-native protection systems to ensure business continuity. It positions security integration as a core enabler of digital transformation.
Rising Investment in Advanced Technologies to Strengthen Network Resilience
Artificial intelligence and machine learning redefine how organizations address cybersecurity challenges. The Network Security Market leverages predictive analytics to detect anomalies in real time. Automated threat response reduces incident resolution times and improves resilience. Integration of blockchain supports tamper-proof data exchange across networks. Cybersecurity spending by governments and enterprises reinforces development of cutting-edge defenses. It drives continuous innovation and strengthens the overall market ecosystem.
Market Trends
Rising Deployment of Zero-Trust Security Models Across Enterprises
The Network Security Market advances with rapid adoption of zero-trust frameworks. Businesses shift from perimeter-based models to continuous verification of every access request. It enhances resilience against insider threats and unauthorized lateral movements within networks. Zero-trust architecture gains traction across government, healthcare, and financial institutions. Enterprises integrate multi-factor authentication, micro-segmentation, and identity-based access control to strengthen systems. Growing hybrid workforces and cloud adoption accelerate the pace of zero-trust deployment.
- For instance, Cisco’s Universal ZTNA blocked and detected all 30 real-world attack attempts in independent testing-12 stolen credential attacks, 8 MFA brute-force attempts, and 10 session hijacks-earning a top SE Labs AAA rating.
Expanding Integration of Artificial Intelligence and Machine Learning in Security Tools
The Network Security Market leverages AI and ML to detect and respond to threats faster. Predictive analytics improves identification of anomalies in network traffic. It reduces dependence on manual monitoring and enhances real-time decision-making. Advanced algorithms help security teams combat polymorphic malware and evolving attack vectors. AI-driven tools also support automated patch management and vulnerability assessments. Industries adopt these technologies to improve efficiency and reduce operational risks.
- For instance, Broadcom's Symantec Enterprise Cloud leverages its Global Intelligence Network-one of the world’s largest civilian threat intelligence networks. Using advanced AI and machine learning, the platform analyzes 11 trillion elements of telemetry to discover, block, and remediate advanced attacks.
Growing Importance of Cloud-Native Security for Hybrid Environments
The Network Security Market evolves to address complex hybrid and multi-cloud systems. Enterprises invest in cloud-native security to protect workloads and applications. It ensures consistent data protection across public, private, and edge infrastructures. Secure access service edge (SASE) and cloud workload protection platforms gain prominence. Vendors deliver scalable, flexible solutions tailored for distributed IT architectures. The expansion of remote access drives strong demand for adaptive cloud-based defenses.
Increasing Focus on Security Automation and Orchestration Solutions
The Network Security Market emphasizes automation to improve response speed and accuracy. Security orchestration, automation, and response platforms streamline incident detection and containment. It minimizes human error while managing large volumes of alerts. Automated playbooks and workflows enhance operational efficiency in security operations centers. Enterprises adopt these systems to address skilled workforce shortages in cybersecurity. Growing adoption of orchestration reflects a long-term trend toward more intelligent and proactive defense mechanisms.
Market Challenges Analysis
High Complexity of Managing Advanced Security Infrastructure Across Enterprises
The Network Security Market faces significant hurdles in handling complex and layered defense systems. Enterprises deploy multiple tools for firewalls, intrusion detection, endpoint security, and cloud protection. It creates integration challenges that increase administrative overhead and slow response times. Small and mid-sized businesses struggle with limited budgets and lack of skilled resources to manage such environments. Frequent software updates and evolving threat intelligence demand continuous adaptation. The absence of interoperability across vendor platforms further complicates security operations for organizations.
Shortage of Skilled Cybersecurity Professionals Hindering Effective Implementation
The Network Security Market struggles with a global shortage of trained cybersecurity specialists. Enterprises compete for limited talent while facing rising threats across industries. It leads to delays in deploying advanced solutions and weakens incident response capabilities. Training existing staff remains costly and time-consuming for many organizations. The gap in expertise limits adoption of AI-driven and zero-trust architectures. Rising demand for specialized skills in cloud, endpoint, and identity security highlights the ongoing workforce challenge.
Market Opportunities
Rising Demand for Cloud Security and Zero-Trust Architectures Creating New Growth Paths
The Network Security Market benefits from expanding adoption of cloud platforms and hybrid environments. Enterprises require advanced solutions to safeguard distributed applications and remote access points. It opens opportunities for vendors delivering cloud-native firewalls, secure access service edge (SASE), and zero-trust frameworks. Growing digital transformation across industries drives investments in scalable, flexible, and automated systems. The focus on secure migration of mission-critical workloads strengthens demand for innovative offerings. Service providers with end-to-end integration capabilities stand to gain a competitive advantage.
Growing Investments in Artificial Intelligence and Automation for Security Enhancement
The Network Security Market finds opportunities in AI-driven monitoring, threat prediction, and automated response. Enterprises adopt advanced analytics to identify anomalies faster and reduce false alerts. It creates room for vendors offering security orchestration and automated incident management platforms. Governments and corporations fund large projects focused on predictive defense technologies. Cloud providers integrate AI features into their security tools to improve resilience. The rising preference for automation to address workforce shortages ensures strong long-term market potential.
Market Segmentation Analysis:
By Solutions
The Network Security Market demonstrates strong demand across multiple solution categories. Firewalls remain a cornerstone, offering critical protection against unauthorized access and data breaches. Encryption gains prominence with rising concerns over data privacy and regulatory compliance. Intrusion Detection Systems support organizations in identifying unusual activities and preventing potential breaches in real time. Identity and Access Management secures critical assets by ensuring only authorized users can access sensitive data. Unified Threat Management solutions integrate multiple capabilities into a single platform, offering cost-effective and comprehensive protection for enterprises of varying sizes. It highlights the trend of organizations adopting both specialized and consolidated solutions to strengthen network defenses.
- For instance, Juniper’s next-generation SRX Series firewall achieved a 99.7% exploit block rate with zero false positives in independent testing, ensuring highly accurate protection at network edges.
By Services
The Network Security Market expands significantly through specialized service offerings. Consulting Services play a vital role in helping organizations design strategies aligned with regulatory and operational needs. Security Operations provide continuous monitoring and incident handling to protect critical infrastructure. Managed Security Services gain traction among enterprises looking to outsource security functions due to limited internal expertise. It supports cost savings, while offering advanced monitoring tools and access to global threat intelligence. Growing reliance on professional service providers underlines the importance of services in enhancing overall resilience against cyber threats.
- For instance, Huawei's UB-Mesh is designed to achieve very high per-chip bandwidth. A key technical feature cited by Huawei is the capability to scale from 100 Gbps to 10 Tbps (1.25 TB/s) per device, which is necessary for next-generation AI clusters.
By End User
The Network Security Market caters to a diverse range of enterprise needs across different sizes. Small and Medium Enterprises adopt scalable and affordable solutions to safeguard digital assets while managing tight budgets. Firewalls, endpoint protection, and managed services are often prioritized in this segment. Large Enterprises invest in complex, multi-layered solutions that integrate AI, machine learning, and zero-trust frameworks. These organizations require advanced identity management and real-time monitoring systems to protect expansive networks. It reflects a dual demand pattern where SMEs focus on cost-efficient security while large corporations emphasize comprehensive and proactive defense. This segmentation ensures the market continues to address unique needs across industries and organizational scales.
Segments:
Based on Solutions:
- Firewall
- Encryption
Based on Services:
- Consulting Services
- Security Operations
Based on End-User:
- Small & Medium Enterprises
- Large Enterprises
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America dominates the Network Security Market with the largest global share, ranging between 36% and 53% in recent estimates. The United States drives most of this demand, supported by Canada’s steady growth. Strong regulatory frameworks such as HIPAA, PCI DSS, and state-level data privacy laws create consistent pressure on enterprises to invest in advanced defenses. Companies in finance, healthcare, and government spend heavily on intrusion detection, encryption, and identity management. Cloud adoption in the U.S. further fuels demand for zero-trust security and managed services. It makes North America the most mature and technologically advanced hub for network security innovation. The region continues to lead in integrating AI and automation into cybersecurity platforms, reinforcing its global leadership.
Europe
Europe contributes close to 25% of the Network Security Market, placing it behind North America but ahead of other regions. The region benefits from stringent laws such as the General Data Protection Regulation (GDPR), which mandate stronger data protection across industries. Key markets include Germany, the United Kingdom, and France, where enterprises invest in unified threat management and identity solutions. Financial institutions, manufacturing companies, and telecom operators remain the top adopters of advanced security. It sees growing use of encryption and managed services as firms adapt to evolving cyber threats. Vendors find opportunities in tailoring products to strict compliance standards. Europe’s share demonstrates how regulation-driven demand sustains growth even in a slower-expanding digital economy.
Asia-Pacific
Asia-Pacific secures around 22% of the Network Security Market and stands out as the fastest-growing region. Countries such as China, India, Japan, and South Korea drive momentum through rapid digital transformation. Expanding e-commerce, cloud adoption, and mobile-first services expose enterprises to higher risks, creating demand for firewalls, intrusion systems, and endpoint protection. Governments launch national cybersecurity programs, strengthening regulatory frameworks across the region. It boosts adoption of zero-trust models and AI-based monitoring solutions. Rising cyberattacks on financial and manufacturing sectors accelerate spending on both consulting and managed services. Asia-Pacific’s dynamic growth positions it as the future leader in cybersecurity expansion.
Latin America
Latin America represents about 7% of the Network Security Market, with Brazil and Mexico being key contributors. Growing cloud adoption and rising internet penetration drive demand for managed security services. Enterprises in banking, telecom, and energy invest in encryption and identity solutions to safeguard critical systems. Governments also push for stronger cybersecurity regulations, opening opportunities for vendors. It remains an emerging market with limited budgets compared to advanced regions, yet demand for affordable solutions continues to grow. The presence of multinational firms accelerates adoption of global security practices. Latin America’s market demonstrates steady growth potential in the coming years.
Middle East & Africa
The Middle East & Africa account for roughly 6% of the Network Security Market. Countries such as Saudi Arabia, the UAE, and South Africa lead adoption, supported by strong government initiatives. The energy, oil and gas, and banking sectors remain top users of intrusion detection and encryption tools. Rising investment in smart city projects in the Gulf states accelerates demand for cloud-native security solutions. It reflects a shift toward integrating identity management and unified threat systems into critical infrastructure. Africa sees gradual adoption, with South Africa driving most spending. While smaller in share, this region provides significant long-term opportunities due to rising digitization.
Key Player Analysis
- Sophos Ltd
- Aruba Networks
- Fortinet Inc
- Motorola Solutions
- Ruckus
- Cisco Systems Inc
- Aerohive
- Dell Technologies
- Broadcom Inc
- Jupiter Networks Inc
Competitive Analysis
The Network Security Market features include Sophos Ltd, Aruba Networks, Fortinet Inc, Motorola Solutions, Ruckus, Cisco Systems Inc, Aerohive, Dell Technologies, Broadcom Inc, and Jupiter Networks Inc. The Network Security Market remains highly competitive, shaped by continuous innovation and rising enterprise demand for advanced protection. Companies focus on expanding product portfolios that include firewalls, intrusion detection, cloud-native platforms, and identity management solutions. Strategic mergers, acquisitions, and technology partnerships play a central role in gaining market share. Vendors emphasize integration of artificial intelligence, automation, and zero-trust frameworks to address complex security needs. Service offerings such as managed security and consulting also create differentiation in a crowded landscape. Strong investment in R&D ensures consistent development of next-generation solutions, reinforcing competition and driving the overall market forward.
Recent Developments
- In May 2025, Huawei Technologies Co., Ltd. unveiled the Xinghe Intelligent High-Quality Wi-Fi 7 Campus Network Solution, offering advanced performance and security features for enterprise wireless connectivity.
- In July 2024, SonicWall launched Cloud Secure Edge (CSE), an innovative suite of Zero-Trust Network Access (ZTNA) offerings developed specifically for Managed Service Providers (MSPs). It is a cost-effective and flexible solution which provides remote access and internet access to organizations to connect with their employees and third-party users securely from any device and location.
- In July 2024, Fortinet, Inc. introduced a hardware-as-a-service offering that keep the latest firewall technology updated. The FortiGate-as-a-Service (FGaaS) enables customers to choose the hardware they want and FortiGate next-gen firewalls. The company will manage and configure the device for the customer’s service.
- In April 2024, HPE Aruba Networking launched its first range of Wi-Fi 7-capable access points, introducing the 730 Series Campus APs. While built on the latest Wi-Fi 7 standard, the products are positioned to stand out in the wireless market not solely for speed, but for their integrated network security and location-based services.
Report Coverage
The research report offers an in-depth analysis based on Solutions, Services, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Network Security Market will expand with growing adoption of zero-trust architectures.
- AI and machine learning will strengthen real-time threat detection and automated response.
- Cloud-native security platforms will dominate with rising multi-cloud and hybrid deployments.
- Demand for managed security services will grow due to global workforce shortages.
- IoT and edge device expansion will create new requirements for endpoint protection.
- Regulatory pressure will drive greater investment in compliance-focused security solutions.
- Small and medium enterprises will increasingly adopt scalable and affordable protection tools.
- Integration of blockchain will enhance data integrity and secure transaction environments.
- Remote and hybrid work models will keep secure access and identity management in focus.
- Continuous innovation in orchestration and automation will define long-term competitive advantage.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Cybersecurity Threats
The increasing frequency and sophistication of cyberattacks such as ransomware, phishing, and DDoS are compelling organizations to invest in advanced network security solutions, including next-generation firewalls and intrusion detection systems, to protect their expanding digital infrastructures.
Regulatory Compliance and Data Protection
Stringent regulations like GDPR, HIPAA, and CCPA require organizations to implement robust network security measures, driving demand for encryption, identity management, and continuous monitoring solutions to ensure compliance and avoid penalties.
Cloud Migration and Remote Work
The rapid adoption of cloud services and hybrid work environments has created complex, distributed network architectures, intensifying the need for cloud-native security platforms, secure access solutions, and zero-trust frameworks to safeguard remote endpoints and cloud workloads.
Integration of AI and Automation
Organizations are leveraging artificial intelligence and automation to enhance real-time threat detection, accelerate incident response, and reduce operational risks, fueling demand for AI-driven security tools and automated orchestration platforms.
Shortage of Skilled Cybersecurity Professionals
A global shortage of cybersecurity talent is prompting enterprises to adopt managed security services and automated solutions, increasing reliance on external expertise and advanced technologies to maintain effective network protection.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Network Security Market, and what is its projected size in 2032?
Which Network Security Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Network Security Market?
Who are the leading companies in the Network Security Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service
- 1.2.1 Consulting Services
- 1.2.2 Security Operations
- 1.2.3 Managed Security Services
- 1.2.4 Professional Services
- 1.3 By End User
- 1.3.1 Small & Medium Enterprises
- 1.3.2 Large Enterprises
- 1.3.3 Government & Public Sector
- 1.3.4 Healthcare
- 1.3.5 BFSI
- 1.4 By Solution
- 1.4.1 Firewall
- 1.4.2 Encryption
- 1.4.3 Intrusion Detection Systems
- 1.4.4 Identity and Access Management
- 1.4.5 Unified Threat Management
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 80.89 billion → 2032: USD 138.98 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Network Security Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Network Security Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Network Security Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Network Security Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Network Security Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Network Security Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Network Security Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Network Security Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 80.89 billion → 2032: USD 138.98 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Network Security Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Consulting Services
- 12.3.7.2 Security Operations
- 12.3.7.3 Managed Security Services
- 12.3.7.4 Professional Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Small & Medium Enterprises
- 12.4.7.2 Large Enterprises
- 12.4.7.3 Government & Public Sector
- 12.4.7.4 Healthcare
- 12.4.7.5 BFSI
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Solution - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Firewall
- 12.5.7.2 Encryption
- 12.5.7.3 Intrusion Detection Systems
- 12.5.7.4 Identity and Access Management
- 12.5.7.5 Unified Threat Management
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Network Security End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Network Security Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Network Security Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Network Security Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Sophos Ltd
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Aruba Networks
- 18.4 Fortinet Inc
- 18.5 Motorola Solutions
- 18.6 Ruckus
- 18.7 Cisco Systems Inc
- 18.8 Dell Technologies
- 18.9 Broadcom Inc
- 18.10 Juniper Networks Inc
- 18.11 SonicWall
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

