
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Neurovascular Devices Market Size 2024 | USD 7,851.39 million |
| Neurovascular Devices Market, CAGR | 5.80% |
| Neurovascular Devices Market Size 2032 | USD 12,298.26 million |
Market Overview
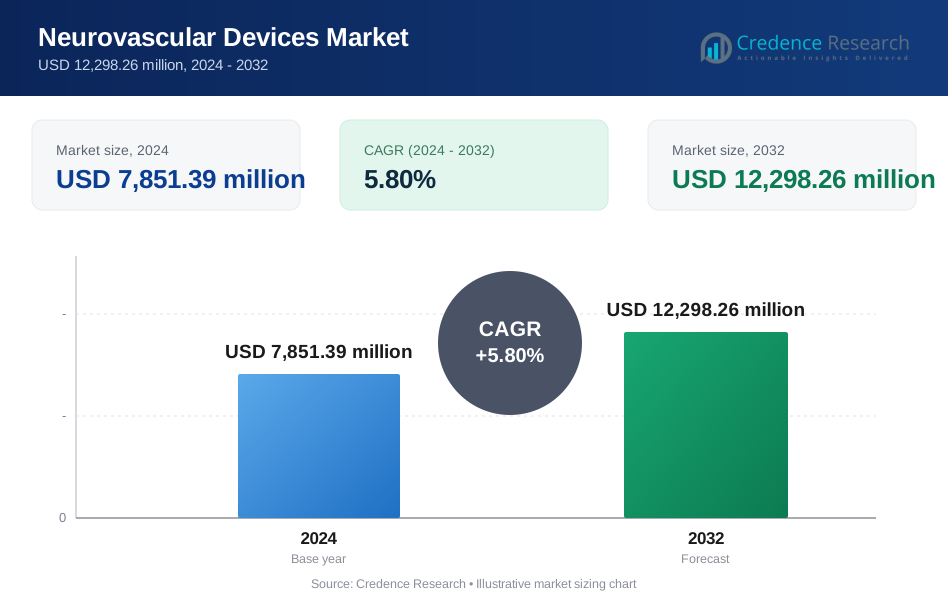
Neurovascular Devices Market size was valued at USD 6,780.00 million in 2018 to USD 7,851.39 million in 2024 and is anticipated to reach USD 12,298.26 million by 2032, at a CAGR of 5.80% during the forecast period.
The Neurovascular Devices Market is experiencing robust growth driven by the rising incidence of neurovascular diseases such as stroke and aneurysms, coupled with an aging global population that is increasingly susceptible to these conditions. Advancements in minimally invasive surgical techniques and the development of technologically advanced devices, including stent retrievers and flow diverters, are significantly improving patient outcomes and boosting adoption among healthcare providers. Heightened awareness of early diagnosis and treatment options, along with supportive government initiatives and increased healthcare spending, further accelerate market expansion. Trends indicate a growing preference for endovascular procedures due to reduced recovery times and complications, as well as ongoing investments in research and development to introduce more efficient, safer, and cost-effective solutions. The integration of artificial intelligence and advanced imaging in neurovascular procedures is also enhancing procedural accuracy, signaling a continued shift toward innovation and improved clinical results in the neurovascular devices sector.
The geographical analysis of the Neurovascular Devices Market highlights strong growth across North America, Europe, and Asia Pacific, with each region contributing uniquely to the industry’s expansion. North America stands out for its robust healthcare infrastructure, early adoption of advanced neurovascular technologies, and presence of major manufacturers. Europe’s growth is supported by an increasing prevalence of neurovascular disorders, well-established medical networks, and ongoing clinical research. Asia Pacific demonstrates significant momentum due to expanding healthcare investment, a large patient pool, and rapid technological advancement in countries such as China, Japan, and India. Among the leading companies driving innovation and market presence are Medtronic, Stryker Corporation, and Terumo Corporation. These key players invest heavily in research and development, consistently launch new products, and maintain strong collaborations with healthcare providers and academic institutions to support global market advancement.
Market Insights
The Neurovascular Devices Market is projected to grow from USD 7,851.39 million in 2024 to USD 12,298.26 million by 2032, registering a CAGR of 5.80% during the forecast period.
· Rising incidence of stroke, cerebral aneurysms, and other neurovascular disorders is a key factor driving demand for advanced neurovascular devices worldwide.
· Minimally invasive procedures, digital integration, and adoption of artificial intelligence in device design are major trends reshaping the landscape and improving patient outcomes.
· Leading companies such as Medtronic, Stryker Corporation, and Terumo Corporation hold strong positions in the market by continuously launching innovative devices and expanding their global reach.
· High device costs, stringent regulatory processes, and limited access to specialized neurovascular care in emerging regions remain significant restraints for market expansion.
· North America leads the market due to its developed healthcare infrastructure and rapid adoption of cutting-edge technologies, while Asia Pacific is witnessing accelerated growth driven by large patient populations and increasing healthcare investments.
· The competitive environment is characterized by strategic collaborations, mergers and acquisitions, and a focus on research and development to maintain technological leadership and address evolving clinical needs.
Market Drivers
Rising Prevalence of Neurovascular Disorders and Aging Population Fuels Demand
The increasing prevalence of neurovascular disorders, such as stroke, aneurysms, and arteriovenous malformations, remains a primary driver for the Neurovascular Devices Market. It benefits from a rapidly aging population that faces a higher risk of these conditions due to age-related physiological changes. Epidemiological studies highlight a steady rise in stroke cases globally, propelling the demand for advanced intervention and treatment solutions. Growing awareness about early diagnosis and the availability of effective neurovascular devices is encouraging more patients to seek timely care. Public health initiatives and awareness campaigns support this trend by educating populations about the risk factors and symptoms of neurovascular diseases. The rising burden of neurological diseases strengthens the need for specialized devices, ensuring sustained market expansion.
- For instance, the World Health Organization has highlighted in its recent reports that the burden of stroke continues to grow, especially in regions with expanding elderly populations.
Advancements in Minimally Invasive Technologies Improve Patient Outcomes
Continuous technological advancements in minimally invasive procedures play a significant role in shaping the Neurovascular Devices Market. It experiences strong adoption of devices such as stent retrievers, flow diverters, and embolic coils that enable precise interventions with minimal trauma. Healthcare providers prefer these solutions because they reduce hospital stays, lower complication rates, and enhance patient recovery times. The shift toward endovascular techniques over traditional open surgeries reflects a broader industry movement prioritizing patient safety and quality of care. New product approvals and regulatory clearances for innovative neurovascular devices enable wider clinical adoption. The commitment to advancing device technology creates new opportunities for market participants.
- For instance, several leading medical device companies have introduced new-generation stent retrievers and flow diverters that have received positive feedback from interventional neurologists for their ease of use and clinical effectiveness.
Increased Healthcare Investments and Favorable Government Policies Support Growth
Greater investments in healthcare infrastructure, especially in emerging economies, provide a foundation for the Neurovascular Devices Market. It benefits from government policies aimed at improving access to advanced medical technologies and strengthening public health systems. Expansion of specialized neurovascular care centers, along with rising insurance coverage for neurovascular procedures, increases the uptake of these devices. Public-private partnerships are facilitating the deployment of new technologies and expanding treatment availability in underserved regions. The presence of funding for research and development encourages manufacturers to innovate and enhance their product portfolios. Robust healthcare funding and policy support will continue to underpin market growth.
Integration of Artificial Intelligence and Advanced Imaging Drives Innovation
The integration of artificial intelligence (AI) and advanced imaging technologies is transforming the Neurovascular Devices Market. It allows for greater procedural precision, faster diagnosis, and better patient stratification. AI-driven platforms are assisting clinicians in decision-making by providing real-time data analysis and risk assessment. Innovations in imaging, such as 3D visualization and high-resolution angiography, improve the accuracy of device placement and treatment planning. These technologies are reducing procedure times and optimizing clinical workflows, leading to improved outcomes and higher efficiency. The ongoing digital transformation in healthcare ensures the market remains at the forefront of medical innovation.
Market Trends
Expansion of Minimally Invasive and Image-Guided Procedures Continues to Accelerate
A key trend in the Neurovascular Devices Market involves the widespread adoption of minimally invasive and image-guided procedures. It benefits from the preference among clinicians and patients for less invasive solutions that promise faster recovery and lower complication rates. New product launches featuring advanced navigation systems and microcatheters are setting new standards for procedural precision. Enhanced imaging capabilities support surgeons in accurately targeting lesions and improving patient outcomes. The growing availability of hybrid operating rooms and interventional suites further accelerates this shift. Health systems are investing in specialized training to expand access to these techniques and to support the integration of innovative devices.
- For instance, recent hospital surveys in North America and Asia-Pacific have reported a marked increase in the use of advanced navigation systems and microcatheters in neurovascular interventions.
Development of Next-Generation Devices Focuses on Safety and Efficacy
Manufacturers are prioritizing the development of next-generation neurovascular devices designed to enhance safety and clinical efficacy. The Neurovascular Devices Market features products with improved biocompatibility, durability, and flexibility, enabling more complex interventions in challenging anatomies. Research and development efforts are yielding stents, coils, and embolic agents with enhanced deployment accuracy and reduced risk of complications. The trend toward personalized devices tailored for specific patient profiles continues to strengthen. Clinical data supporting the efficacy of these new devices is driving regulatory approvals and adoption. Manufacturers are leveraging user feedback to address unmet clinical needs and optimize device performance.
- For instance, recent clinical trials sponsored by leading device manufacturers have demonstrated the benefits of new embolic agents and stents with improved biocompatibility and deployment accuracy.
Strategic Collaborations and Mergers Drive Product Innovation and Market Reach
Strategic collaborations, mergers, and acquisitions are shaping the competitive landscape of the Neurovascular Devices Market. It enables industry players to expand product portfolios, access novel technologies, and enter new geographies. Companies are entering into alliances with research institutions and startups to accelerate the development and commercialization of innovative devices. Partnerships with hospitals and academic centers are facilitating large-scale clinical trials and evidence generation. These strategies help firms adapt to evolving market demands and capitalize on growth opportunities. The dynamic nature of the industry encourages continuous investment in research and commercialization.
Emphasis on Digital Integration and Data-Driven Decision Making Gains Momentum
Digital integration and data-driven decision making have become prominent trends within the Neurovascular Devices Market. It now incorporates artificial intelligence, machine learning, and advanced data analytics into clinical workflows. These technologies enable clinicians to enhance diagnostic accuracy, monitor patient progress, and optimize treatment protocols. The use of real-time data is supporting precision medicine and personalized therapy planning. Digital health platforms are facilitating remote monitoring and post-procedure care, improving patient engagement and outcomes. The market demonstrates a clear movement toward technology-enabled, value-based healthcare delivery.
Market Challenges Analysis
Complex Regulatory Landscape and High Cost of Innovation Hinder Market Growth
The complex regulatory landscape presents a significant challenge for the Neurovascular Devices Market. It faces strict approval requirements and rigorous clinical validation processes across global markets. Meeting these demands requires substantial investments of time and resources, often slowing product launches and limiting access to innovative devices. High development costs and the need for extensive safety and efficacy data further add to the financial burden on manufacturers. Smaller companies may struggle to compete due to limited capital and regulatory expertise. The complexity of global compliance standards can lead to delays and increased operational risk for market participants.
- For instance, surveys conducted by industry associations have found that manufacturers often cite the need to comply with multiple regulatory frameworks such as those set by the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) as a major hurdle.
Limited Access to Specialized Care and Variability in Reimbursement Impede Adoption
Limited access to specialized neurovascular care and inconsistencies in reimbursement policies remain persistent challenges for the Neurovascular Devices Market. It faces disparities in healthcare infrastructure, particularly in emerging and rural regions where advanced neurovascular centers are scarce. Variability in reimbursement coverage can create uncertainty for both providers and patients, impacting the adoption of new technologies. Training gaps among healthcare professionals may hinder optimal device utilization and procedural success. Budget constraints within healthcare systems often restrict investment in state-of-the-art equipment. These factors contribute to uneven market penetration and slow the uptake of innovative neurovascular solutions.
Market Opportunities
Emerging Markets and Expanding Healthcare Infrastructure Create New Growth Avenues
The expansion of healthcare infrastructure in emerging markets presents substantial opportunities for the Neurovascular Devices Market. It stands to benefit from increased investment in hospitals, specialized stroke centers, and advanced imaging facilities in developing countries. Government initiatives and international collaborations are driving efforts to improve access to neurovascular care and address the rising burden of stroke and related disorders. As awareness and diagnosis rates improve, the demand for neurovascular devices is expected to rise in these regions. Companies that tailor product offerings and distribution strategies to local needs can gain a significant competitive edge. The presence of a large, underserved patient population offers considerable potential for future market growth.
Innovation in Digital Technologies and Personalized Medicine Supports Market Expansion
Ongoing innovation in digital health technologies and personalized medicine represents a strong opportunity for the Neurovascular Devices Market. It is poised to leverage artificial intelligence, machine learning, and remote monitoring solutions to enhance patient outcomes and streamline clinical workflows. Personalized approaches to neurovascular treatment are driving the development of tailored devices and data-driven therapy planning. Collaboration with technology firms and academic institutions will accelerate the adoption of smart neurovascular devices. Digital platforms that enable telemedicine and patient engagement can further extend market reach. These advances hold promise for improving procedural success rates and transforming standards of neurovascular care.
Market Segmentation Analysis:
By Device:
cerebral embolization and aneurysm coiling devices lead due to their critical role in treating cerebral aneurysms and complex vascular abnormalities. These devices enable minimally invasive procedures, which appeal to clinicians seeking to reduce patient risk and recovery time. Cerebral angioplasty and stenting systems follow, driven by their effectiveness in managing cerebral artery stenosis and restoring adequate blood flow to the brain. Neurothrombectomy devices hold a strong position due to rising stroke incidence worldwide, offering rapid clot removal and improved outcomes for acute ischemic stroke patients. Support devices complement these categories, enhancing procedural efficiency and safety.
By Application:
The market also segments by application, with stroke commanding the largest share. It reflects the global rise in stroke prevalence and ongoing demand for prompt, effective intervention. Cerebral artery stenosis represents another significant application area, requiring precise device deployment for optimal patient management. Cerebral aneurysm treatment continues to see strong device adoption, benefiting from technological advances and early diagnosis rates. The “others” segment captures use in conditions such as arteriovenous malformations and vascular malformations, where innovative neurovascular devices support tailored therapy.
By End-use:
End-use segmentation further shapes market structure, with hospitals representing the primary channel for neurovascular device adoption. Hospitals leverage advanced imaging, specialized neurology teams, and comprehensive acute care infrastructure to deliver complex neurovascular interventions. Specialty clinics show growing demand, particularly in regions investing in ambulatory surgical centers and specialized neurology practices. The “others” category includes academic and research institutions, which play a vital role in early-stage device trials and the advancement of neurovascular treatment protocols. Each segment, through focused adoption and clinical integration, supports sustained growth and technological innovation within the Neurovascular Devices Market.
Segments:
Based on Device:
- Cerebral Embolization and Aneurysm Coiling Devices
- Cerebral Angioplasty and Stenting Systems
- Neurothrombectomy Devices
- Support Devices
Based on Application:
- Stroke
- Cerebral Artery Stenosis
- Cerebral Aneurysm
- Others
Based on End-use:
- Hospitals
- Specialty Clinics
- Others
Based on Size:
- 0.027"
- 0.021"
- 0.071"
- 0.017"
- 0.019"
- 0.013"
- 0.058"
- 0.068"
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Neurovascular Devices Market
North America Neurovascular Devices Market grew from USD 2,206.21 million in 2018 to USD 2,532.26 million in 2024 and is projected to reach USD 3,981.60 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.9%. North America is holding a 32% market share. The United States and Canada dominate the region due to robust healthcare infrastructure, early adoption of advanced neurovascular technologies, and the presence of leading industry players. The region benefits from extensive reimbursement systems, large patient populations, and strong investments in research and clinical trials. Demand for minimally invasive treatments and a high incidence of stroke and aneurysms are driving device utilization. Hospitals and specialized neurology centers in the U.S. and Canada remain central to market expansion.
Europe Neurovascular Devices Market
Europe Neurovascular Devices Market grew from USD 1,635.34 million in 2018 to USD 1,813.46 million in 2024 and is expected to reach USD 2,643.79 million by 2032, at a CAGR of 4.9%. Europe accounts for a 22% market share. Key countries including Germany, France, and the United Kingdom contribute significantly due to a high prevalence of neurovascular diseases and a strong focus on healthcare quality. European nations benefit from regulatory support, public health initiatives, and a growing emphasis on advanced diagnostic and therapeutic technologies. Aging populations and well-established medical networks support device demand. Regional collaborations and clinical research further accelerate market penetration.
Asia Pacific Neurovascular Devices Market
Asia Pacific Neurovascular Devices Market grew from USD 1,722.12 million in 2018 to USD 2,055.02 million in 2024 and is set to reach USD 3,635.47 million by 2032, posting a CAGR of 7.5%. Asia Pacific represents a 30% market share. China, Japan, and India lead growth with rapidly evolving healthcare infrastructure, rising incidence of cerebrovascular diseases, and increasing investments in hospitals and medical technology. Government initiatives, expanding insurance coverage, and greater awareness of early intervention are driving device uptake. Local manufacturers are introducing cost-effective devices tailored to regional needs, fueling competition and growth. The large patient pool offers significant opportunities for further expansion.
Latin America Neurovascular Devices Market
Latin America Neurovascular Devices Market grew from USD 776.31 million in 2018 to USD 894.19 million in 2024 and is anticipated to reach USD 1,334.73 million by 2032, at a CAGR of 5.2%. Latin America holds a 11% market share. Brazil, Mexico, and Argentina anchor the region with increased healthcare investments and the expansion of stroke care programs. Efforts to upgrade hospital capabilities and broaden access to neurovascular interventions are propelling market development. Public-private partnerships and international collaborations support technology transfer and medical training. Market players are targeting emerging urban centers to capitalize on growing demand.
Middle East Neurovascular Devices Market
Middle East Neurovascular Devices Market grew from USD 241.37 million in 2018 to USD 260.62 million in 2024 and is forecast to reach USD 359.03 million by 2032, at a CAGR of 4.1%. The Middle East represents a 3% market share. Saudi Arabia and the United Arab Emirates are leading adoption with growing investments in healthcare modernization and specialty care. Regional governments focus on increasing access to advanced neurological treatments and building comprehensive stroke centers. Efforts to train specialists and raise disease awareness are gradually enhancing device penetration. Import reliance and pricing pressures present challenges for broader market expansion.
Africa Neurovascular Devices Market
Africa Neurovascular Devices Market grew from USD 198.65 million in 2018 to USD 295.84 million in 2024 and is estimated to reach USD 343.64 million by 2032, showing a CAGR of 1.0%. Africa accounts for a 3% market share. South Africa, Egypt, and Nigeria are primary markets, although access to advanced neurovascular care remains limited. Public sector initiatives are aiming to improve diagnosis and treatment, while partnerships with international organizations are helping to train healthcare professionals. Device adoption is slow due to budget constraints, infrastructure gaps, and a shortage of specialized facilities. Companies are focusing on long-term market education and local partnerships to support future growth.
Key Player Analysis
- Medtronic
- Stryker Corporation
- Terumo Corporation
- Penumbra, Inc.
- Johnson & Johnson Services, Inc.
- Integra LifeSciences Corporation
- Acandis GmbH
- Spiegelberg GmbH & Co. KG
- MicroPort Scientific Corporation
- ZYLOX-TONBRIDGE MEDICAL TECHNOLOGY CO., LTD.
Competitive Analysis
The competitive landscape of the Neurovascular Devices Market features prominent players such as Medtronic, Stryker Corporation, Terumo Corporation, Penumbra, Inc., Johnson & Johnson Services, Inc., Integra LifeSciences Corporation, Acandis GmbH, Spiegelberg GmbH & Co. KG, MicroPort Scientific Corporation, and ZYLOX-TONBRIDGE MEDICAL TECHNOLOGY CO., LTD. These companies maintain their leadership through robust research and development efforts, consistent product launches, and a focus on technological innovation. Companies compete by expanding their product portfolios and securing regulatory approvals for next-generation neurovascular solutions, such as minimally invasive devices and AI-powered imaging tools. Strategic mergers, acquisitions, and collaborations with academic institutions and hospitals play a crucial role in expanding geographic presence and accelerating time-to-market for new products. The industry also emphasizes clinical research to demonstrate the effectiveness and safety of their devices, which supports widespread clinical adoption. Global and regional firms are focusing on addressing unmet clinical needs and tailoring solutions to specific market demands, especially in fast-growing regions. Competitive intensity continues to rise, driven by the ongoing pursuit of technological leadership and broader access to neurovascular care.
Recent Developments
- In September 2024, CERENOVUS, Inc. launched a next-generation balloon guide catheter, EMBOGUARD, for treating patients suffering from acute ischemic stroke.
- In June 2024, Terumo Corporation introduced the LVIS EVO Intraluminal Support Device for treating wide-neck intracranial aneurysms in the U.S. market.
- In May 2024, Penumbra, Inc. reported the CE Mark authorization and the launch of three of its neurovascular reperfusion catheters in Europe- Red 78, Red 43, and Red 72 with SENDit Technology for treating acute ischemic strokes.
- In April 2024, CERENOVUS, Inc., launched the CEREGLIDE 71 Aspiration Catheter in Europe; this catheter is useful for revascularizing patients suffering from acute ischemic stroke.
- In September 2023, Terumo Corporation obtained 510(k) clearance from the FDA for its Sofia EX 5Fr 115cm intracranial support catheter for use in trans-radial access.
Market Concentration & Characteristics
The Neurovascular Devices Market displays a moderate to high level of market concentration, with a few large multinational companies holding significant influence due to extensive product portfolios, established distribution networks, and continuous innovation. It features a strong focus on advanced technology, including minimally invasive devices and integration with digital health solutions. The market is characterized by rapid adoption of new products, rigorous regulatory standards, and high investment in clinical research. Barriers to entry remain considerable because of strict approval processes and the need for substantial capital investment. It experiences ongoing consolidation, with mergers, acquisitions, and strategic partnerships frequently shaping competitive dynamics. Companies compete on technological leadership, clinical evidence, and global reach, while regional players contribute to market diversity by introducing cost-effective and locally tailored solutions. The sector prioritizes safety, efficacy, and clinician training, reflecting its commitment to quality outcomes and sustainable growth.
Report Coverage
The research report offers an in-depth analysis based on Device, Application, End-use, Size and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for personalized neurovascular devices will rise, driven by advances in genomics and precision medicine.
- Digital health integration will expand, supporting remote patient monitoring and real-time data sharing between providers and patients.
- Artificial intelligence applications will increase, enabling faster diagnosis and optimized treatment pathways in neurovascular care.
- Growing awareness and education programs will improve early detection and timely intervention for neurovascular diseases worldwide.
- Industry leaders will prioritize eco-friendly manufacturing and sustainable product designs to align with global environmental goals.
- Expanded training and education for healthcare professionals will enhance the adoption and safe use of advanced neurovascular devices.
- Increasing clinical trial activity will strengthen evidence for novel technologies and support broader market access.
- Companies will focus on developing cost-effective devices to improve affordability and access in lower-income and rural regions.
- Partnerships with academic and research organizations will accelerate innovation and bring new device concepts to commercialization.
- Evolving reimbursement frameworks and health policy reforms will support broader insurance coverage for neurovascular procedures, encouraging market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Neurovascular Disorders and Aging Population
The increasing incidence of stroke, cerebral aneurysms, and other neurovascular conditions, particularly among the aging global population, is driving demand for advanced neurovascular devices. As more patients require timely intervention, the need for effective and minimally invasive treatment options continues to grow.
Advancements in Minimally Invasive Technologies
Continuous innovation in minimally invasive devices such as stent retrievers, flow diverters, and embolic coils is improving patient outcomes and reducing recovery times. These technological advancements are encouraging healthcare providers to adopt newer devices, expanding the market.
Increased Healthcare Investments and Favorable Government Policies
Growing investments in healthcare infrastructure, especially in emerging markets, and supportive government initiatives are improving access to neurovascular care. Expansion of specialized centers and broader insurance coverage are further accelerating device adoption.
Integration of Artificial Intelligence and Advanced Imaging
The adoption of AI and advanced imaging technologies is enhancing procedural accuracy, enabling faster diagnosis, and supporting better patient stratification. These digital innovations are making neurovascular interventions safer and more effective, fueling market growth.
Growing Awareness and Early Diagnosis
Public health campaigns and improved education about neurovascular disease symptoms are leading to earlier diagnosis and intervention. This trend is increasing the number of patients eligible for neurovascular device-based treatments, supporting sustained market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Neurovascular Devices Market?
What factors are driving the growth of the Neurovascular Devices Market?
What are some challenges faced by the Neurovascular Devices Market?
Who are the major players in the Neurovascular Devices Market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Device
- 1.2.1 Cerebral Embolization and Aneurysm Coiling Devices
- 1.2.2 Cerebral Angioplasty and Stenting Systems
- 1.2.3 Neurothrombectomy Devices
- 1.2.4 Support Devices
- 1.3 By End-use
- 1.3.1 Hospitals
- 1.3.2 Specialty Clinics
- 1.3.3 Others
- 1.4 By Application
- 1.4.1 Stroke
- 1.4.2 Cerebral Artery Stenosis
- 1.4.3 Cerebral Aneurysm
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,851.39 million → 2032: USD 12,298.26 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Neurovascular Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Neurovascular Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Neurovascular Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Neurovascular Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Neurovascular Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Neurovascular Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Neurovascular Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Neurovascular Devices Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,851.39 million → 2032: USD 12,298.26 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Neurovascular Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Device - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cerebral Embolization and Aneurysm Coiling Devices
- 12.3.7.2 Cerebral Angioplasty and Stenting Systems
- 12.3.7.3 Neurothrombectomy Devices
- 12.3.7.4 Support Devices
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Specialty Clinics
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Stroke
- 12.5.7.2 Cerebral Artery Stenosis
- 12.5.7.3 Cerebral Aneurysm
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Neurovascular Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Neurovascular Devices Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Neurovascular Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Neurovascular Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Medtronic
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Stryker Corporation
- 18.4 Terumo Corporation
- 18.5 Penumbra, Inc.
- 18.6 Johnson & Johnson Services, Inc.
- 18.7 Integra LifeSciences Corporation
- 18.8 Acandis GmbH
- 18.9 MicroPort Scientific Corporation
- 18.10 ZYLOX-TONBRIDGE MEDICAL TECHNOLOGY CO., LTD.
- 18.11 Spiegelberg GmbH & Co. KG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

