
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| North America Data Center Market Size 2023 | USD 114,117.78 Million |
| North America Data Center Market, CAGR | 6.17% |
| North America Data Center Market Size 2032 | USD 201,800.26Million |
Market Overview
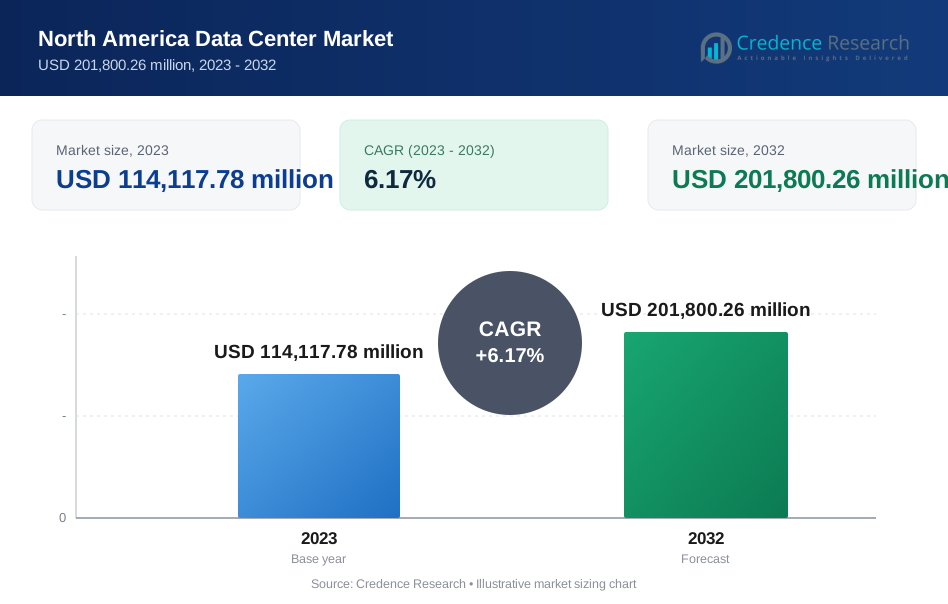
The North America data center market is projected to grow from USD 114,117.78 million in 2023 to an estimated USD 201,800.26 million by 2032, reflecting a compound annual growth rate (CAGR) of 6.17% from 2024 to 2032. This significant expansion is driven by the increasing demand for cloud computing, big data analytics, and the rising adoption of artificial intelligence (AI) and machine learning (ML) technologies.
Key drivers contributing to the growth of the North America data center market include the rapid proliferation of internet usage, the expansion of IoT devices, and the growing emphasis on data privacy and security regulations. Additionally, the trend towards hybrid and multi-cloud environments is pushing enterprises to invest in scalable and efficient data center infrastructures. The market is also witnessing advancements in energy-efficient technologies, further propelling its growth.
Geographically, the United States dominates the North America data center market, owing to its advanced technological infrastructure and significant investments by major tech companies. Canada follows as a key contributor, driven by its growing tech sector and government initiatives to promote digitalization. Leading players in this market include Microsoft Corporation, Amazon Web Services (AWS), Google LLC, Equinix, Inc., and Digital Realty Trust, Inc., who continue to innovate and expand their data center capacities to meet the increasing demand.
Market Drivers
Rapid Proliferation of Cloud Computing and Big Data
The North America data center market is experiencing significant growth driven by the rapid proliferation of cloud computing and big data technologies. Organizations across various sectors are increasingly adopting cloud services to enhance operational efficiency, scalability, and cost-effectiveness. This widespread adoption has led to an exponential increase in the amount of data generated and processed daily, necessitating robust and scalable data center infrastructures. For instance, a survey conducted by a leading IT research firm found that a majority of enterprises in North America have already adopted or plan to adopt cloud services within the next year. Cloud service providers are investing heavily in expanding their data center capacities to accommodate the growing demand. Additionally, the rise of big data analytics has further fueled the demand for high-performance data centers. A government report on the digital economy highlighted the significant impact of big data on various industries, with many companies reporting improved decision-making and customer experiences as a result of big data analytics. As businesses continue to leverage these technologies, the need for efficient data storage and processing solutions will continue to grow, propelling the expansion of the data center market in North America.
Increasing Adoption of Artificial Intelligence (AI) and Machine Learning (ML)
The integration of artificial intelligence (AI) and machine learning (ML) technologies into business operations is another significant driver of the North America data center market. These technologies require vast amounts of computational power and data storage, which can only be provided by advanced data centers. A recent industry survey revealed that a substantial number of North American companies are either already using or planning to implement AI and ML in their operations within the next few years. As AI and ML become increasingly central to business strategies, organizations are investing in state-of-the-art data center facilities to support these technologies. For instance, a major tech company recently announced plans to build several AI-focused data centers across North America to meet the growing demand for AI computing resources. Moreover, AI and ML are being used to optimize data center operations themselves, enabling more efficient cooling, power management, and workload distribution. A study by a prominent energy research institute found that AI-powered data centers can achieve significant reductions in energy consumption compared to traditional facilities. This symbiotic relationship between AI/ML and data centers creates a continuous cycle of demand and innovation, driving the market forward.
Expansion of the Internet of Things (IoT) Ecosystem
The expansion of the Internet of Things (IoT) ecosystem is a critical factor driving the growth of the North America data center market. IoT devices generate massive amounts of data that need to be collected, stored, and processed in real time, leading to a surge in demand for data centers capable of handling IoT workloads. A government report on the state of IoT adoption in North America highlighted the rapid growth of connected devices across various sectors, with projections indicating a significant increase in the number of IoT devices over the next five years. The growth of IoT is particularly prominent in sectors such as healthcare, automotive, and manufacturing. For example, a survey of healthcare providers in North America found that a majority are already using or planning to implement IoT devices for patient monitoring and diagnostics. As the IoT ecosystem continues to expand, the volume of data generated will increase exponentially, necessitating the development of more data centers with high storage capacity and low latency. Additionally, the advent of 5G technology is expected to accelerate the adoption of IoT devices. A recent study by a telecommunications association found that 5G networks will enable a much higher density of connected devices compared to previous generations, further driving the demand for data center infrastructure.
Emphasis on Data Privacy and Security Regulations
The growing emphasis on data privacy and security regulations in North America is another major driver of the data center market. With the increasing amount of sensitive data being generated and stored, there is a heightened focus on protecting this information from cyber threats and ensuring compliance with stringent data protection laws. Regulations such as the General Data Protection Regulation (GDPR) in Europe, the California Consumer Privacy Act (CCPA), and other state-level data privacy laws in the United States have put pressure on organizations to enhance their data security measures. This has led to a surge in demand for secure data center facilities that can offer advanced cybersecurity solutions and comply with regulatory requirements. Furthermore, the rise of cyberattacks, including ransomware and data breaches, has prompted companies to invest in more resilient data center infrastructures with built-in security features such as encryption, firewalls, and intrusion detection systems. As data privacy concerns continue to grow, the demand for compliant and secure data centers will increase, driving further growth in the market. Additionally, the trend towards hybrid and multi-cloud environments, where data is distributed across multiple locations, necessitates robust data center solutions to ensure data integrity and security across different platforms.
Market Trends
Shift Towards Sustainability and Energy Efficiency
A significant trend shaping the North America data center market is the increasing focus on sustainability and energy efficiency. As data centers are notorious for their high energy consumption, there is growing pressure from governments, environmental groups, and consumers for the industry to adopt greener practices. Companies are now investing heavily in renewable energy sources, such as wind, solar, and hydroelectric power, to reduce their carbon footprint. For instance, major tech giants have committed to achieving carbon neutrality and are implementing strategies to power their data centers entirely with renewable energy. In addition to adopting green energy, data center operators are also focusing on improving the energy efficiency of their facilities. Innovations such as advanced cooling systems, AI-driven energy management, and the use of energy-efficient hardware are becoming standard in new data center designs. The shift towards sustainable practices is not only driven by regulatory requirements but also by the growing demand from clients who prioritize environmental responsibility in their business partnerships. This trend is expected to continue as the industry seeks to balance the increasing demand for data with the need to minimize environmental impact.
Adoption of Edge Computing and Hybrid Cloud Architectures
Another prominent trend in the North America data center market is the adoption of edge computing and hybrid cloud architectures. As the volume of data generated by IoT devices, autonomous vehicles, and other latency-sensitive applications increases, there is a growing need for data processing to occur closer to the data source. This has led to the rise of edge computing, where smaller, decentralized data centers are deployed near the point of data generation to reduce latency and improve real-time processing capabilities. Edge data centers are becoming crucial for industries such as healthcare, finance, and manufacturing, where low latency is essential for operational efficiency. Concurrently, the adoption of hybrid cloud architectures is gaining momentum as organizations seek the flexibility to manage workloads across both on-premises and cloud environments. Hybrid cloud solutions allow businesses to optimize costs, enhance data security, and improve scalability by leveraging the strengths of both private and public clouds. This trend is driving the demand for data centers that can seamlessly integrate with various cloud platforms, offering hybrid solutions that cater to the diverse needs of enterprises.
Market Restraints and Challenges
High Operational Costs and Energy Consumption
One of the primary challenges facing the North America data center market is the high operational costs associated with running and maintaining data centers. Data centers require substantial amounts of energy to power servers, cooling systems, and other essential infrastructure, leading to significant utility expenses. For instance, a recent survey by the Uptime Institute found that a majority of data center managers are concerned about enhancing energy performance. Despite efforts to adopt energy-efficient technologies and renewable energy sources, the overall cost of operations remains a significant burden for data center operators. These high operational costs can hinder profitability, particularly for smaller players in the market who may struggle to compete with larger companies that have more resources to invest in cost-reducing innovations. Furthermore, fluctuating energy prices and potential future regulations aimed at curbing energy consumption could exacerbate this challenge, making it crucial for data center operators to continuously seek ways to optimize efficiency and reduce costs.
Increasing Complexity of Data Security and Compliance
The growing complexity of data security and compliance is another significant restraint in the North America data center market. As data centers handle vast amounts of sensitive information, they are increasingly targeted by cyberattacks, including data breaches, ransomware, and other forms of cybercrime. For instance, a report by the U.S. Department of Energy highlighted the rising number of cyber incidents targeting critical infrastructure, including data centers. Ensuring robust data security is a constant challenge, requiring significant investment in advanced cybersecurity measures, regular audits, and compliance with stringent regulations. Additionally, the adoption of hybrid and multi-cloud environments complicates data management, as organizations must ensure data integrity and security across multiple platforms. The need to comply with various local, state, and federal regulations adds another layer of complexity, as data center operators must navigate a patchwork of laws that can vary significantly depending on the jurisdiction. These challenges not only increase operational costs but also expose data centers to legal risks and reputational damage in the event of a security breach.
Market Segmentation Analysis
By Type
The North America data center market is divided into several key segments: Enterprise, Edge, Colocation, Hyperscale, Managed, and Modular data centers. According to recent industry surveys, Enterprise data centers continue to be a significant segment, though their share is gradually declining as businesses shift towards cloud and colocation solutions. Edge data centers are experiencing rapid growth, driven by the increasing demand for low-latency applications and IoT devices. For instance, a major telecom company reported a substantial increase in edge deployments across urban centers. Colocation facilities are gaining popularity among small to medium-sized businesses, with several providers expanding their footprint across the region. Hyperscale data centers dominate in terms of capacity, with tech giants like Amazon, Microsoft, and Google leading the charge. A government report highlighted the economic impact of hyperscale facilities, noting their contribution to job creation and local infrastructure development. Managed data centers are attracting organizations looking to outsource their IT operations, while modular data centers are finding favor for their scalability and quick deployment capabilities. Overall, the market is evolving to meet diverse needs, from enterprise-grade security to edge computing performance.
By Compound
The North America data center market's compound segmentation encompasses hardware, Data Centre Infrastructure Management (DCIM) software, and services. Hardware remains the largest segment, with power and cooling systems seeing significant investments due to energy efficiency concerns. For example, a leading hardware manufacturer reported strong sales growth in their data center power management solutions. Rack and server technologies are evolving to meet the demands of high-density computing, with several vendors introducing innovative designs for AI and machine learning workloads. The DCIM software market is shifting towards cloud-based solutions, as evidenced by the adoption rates reported in a recent industry survey. On-premises DCIM still maintains a strong presence, particularly in sectors with stringent data sovereignty requirements. The service segment is experiencing robust growth, with managed services gaining traction among enterprises looking to optimize their IT operations. A government study on digital transformation highlighted the increasing demand for professional services in data center planning and implementation. Integration and consulting services are also seeing upticks as organizations navigate complex hybrid and multi-cloud environments.
Segments
Based on Type
- Enterprise
- Edge
- Colocation
- Hyperscale
- Managed
- Modular
Based on Compound
- Hardware
- Power Systems
- Cooling Systems
- Racks
- Servers
- Networking Devices
- Others
- Nigeria Data Centre Infrastructure Management Software
- Cloud-based
- On-premises
- Service
- Professional Services
- Integration & Implementation
- Consulting
- Support & Maintenance
- Managed Services
Based on Size
- Small
- Mid-Sized
- Large
Based on Tier
- Tier 1
- Tier 2
- Tier 3
- Tier 4
Based on Industry
- IT & Telecom
- BFSI
- Manufacturing
- Healthcare
- Government
- Others
Based on Region
- United States
- Canada
- Mexico
Regional Analysis
United States (78%):
The United States holds the largest share of the North America data center market, accounting for approximately 78% of the total market. For instance, a recent industry survey by DataCenter Dynamics found that hyperscale providers like Amazon Web Services and Microsoft Azure continue to expand their data center footprints across the country. The U.S. market sees high demand for cloud services and emerging technologies, as highlighted in Gartner's latest IT spending forecast. Government initiatives are also fueling growth, with the Department of Energy's data center optimization program encouraging efficiency improvements. The U.S. Green Building Council reports an uptick in LEED-certified data centers, reflecting a focus on sustainability. Overall, the robust infrastructure and innovation ecosystem position the U.S. as the regional leader.
Canada (15%):
Canada contributes around 15% to the North America data center market, positioning itself as a growing hub for data center operations. The Canadian Internet Registration Authority notes increasing demand for domestic data storage due to data sovereignty concerns. A recent survey by IDC Canada found that over 60% of Canadian organizations are accelerating their cloud adoption plans. The Canadian government's Digital Charter Implementation Act is spurring investments in data infrastructure. Natural Resources Canada highlights the country's cooler climate as advantageous for data center cooling efficiency. Industry Canada reports growing foreign direct investment in the sector, particularly from U.S. and European operators looking to establish a North American presence. Sustainable practices are gaining traction, with the Canada Green Building Council noting rising certifications for data centers.
Key players
- CoreSite (America Tower Corporation)
- DPR Construction
- CyrusOne Inc.
- Cyxtera Technologies
- Databank Holdings Ltd
- Digital Realty Trust, Inc.
- Equinix, Inc.
- Flexential Corp.
- H5 Data Centers LLC
- NTT Ltd.
- Quality Technology Services (QTS)
- Switch
- Vantage Data Centers, LLC
Competitive Analysis
The North America data center market is characterized by intense competition among key players, each striving to expand their market presence and enhance service offerings. Digital Realty Trust, Inc., and Equinix, Inc. are market leaders, leveraging their vast global networks and robust infrastructure to attract a diverse client base. Companies like CoreSite (American Tower Corporation) and CyrusOne Inc. focus on providing scalable, high-performance solutions, catering to enterprise-level clients with specific needs. NTT Ltd. and Switch are distinguished by their commitment to innovation and sustainable practices, setting benchmarks in energy efficiency. New entrants and smaller players, such as H5 Data Centers LLC and Vantage Data Centers, LLC, compete by offering specialized and flexible solutions, often targeting niche markets. The competitive landscape is further intensified by strategic mergers, acquisitions, and partnerships, as companies seek to consolidate their market positions and expand their service capabilities across the region.
Recent Developments
- In November 2021, American Tower Corporation acquired CoreSite for approximately $10.1 billion, expanding its data center portfolio.
- In September 2024, DPR Construction was named a Best Workplace for Innovators by Fast Company for the second consecutive year, highlighting its commitment to innovation in construction.
- In January 2024, Evoque Data Center Solutions completed its acquisition of Cyxtera's data center portfolio, combining to form a leading data center company with over 50 locations, primarily in North America.
- In April 2024, DataBank established a new $725 million credit facility to finance ongoing and future data center construction projects across multiple markets including New York, Denver, Minneapolis, Salt Lake City, and Dallas.
- In April 2024, Digital Realty and Blackstone announced a $7 billion joint venture to develop hyperscale data centers across three Tier 1 metros in Europe and North America, with plans to deliver approximately 500 megawatts of IT capacity.
- In April 2024, Equinix and PGIM Real Estate entered into a $600 million joint venture to develop and operate the first xScale data center in the U.S., located in the Silicon Valley region of California.
- In September 2024, Flexential announced significant data center expansions and product enhancements, including 112 MW of total available capacity and the launch of Flexential Fabric, an advanced interconnection solution.
Market Concentration and Characteristics
The North America data center market is moderately concentrated, with a mix of global giants and regional players competing for market share. Key characteristics of this market include high barriers to entry due to the substantial capital investment required for infrastructure, advanced technology, and regulatory compliance. The market is dominated by a few large companies, such as Digital Realty Trust, Inc., Equinix, Inc., and CoreSite (America Tower Corporation), which leverage their extensive networks and resources to maintain a competitive edge. However, the presence of specialized providers like Cyxtera Technologies and Vantage Data Centers, LLC, catering to niche segments, adds diversity to the competitive landscape. The market is characterized by rapid innovation, a strong focus on energy efficiency and sustainability, and increasing adoption of cloud services, which drive continuous expansion and evolution.
Report Coverage
The research report offers an in-depth analysis based on Type, Compound, Size, Tier, Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for cloud services will continue to surge, driving the expansion of data center infrastructure to accommodate increasing data storage and processing needs.
- Edge computing will gain prominence as organizations seek to reduce latency and enhance real-time data processing, leading to the proliferation of smaller, decentralized data centers.
- The industry will prioritize sustainability, with data centers increasingly powered by renewable energy sources and adopting energy-efficient technologies to reduce carbon footprints.
- Data centers will integrate more AI-driven automation for energy management, predictive maintenance, and operational efficiency, reducing costs and improving performance.
- Hyperscale data centers will continue to expand, driven by major cloud service providers like AWS, Google, and Microsoft, to support the growing global digital economy.
- Modular and prefabricated data centers will become more prevalent, offering scalable and flexible solutions that can be rapidly deployed to meet specific organizational needs.
- As cyber threats evolve, data centers will invest heavily in advanced cybersecurity measures and ensure compliance with increasingly stringent data protection regulations.
- The rollout of 5G networks will drive demand for data centers equipped to handle the increased data traffic and low-latency requirements of connected devices and IoT ecosystems.
- The market will witness continued consolidation through mergers and acquisitions, as companies seek to strengthen their market positions and expand their service offerings.
- While the U.S. will remain the dominant player, regions like Canada and Mexico will see accelerated growth due to increasing digitalization efforts and foreign investments in data center infrastructure.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Proliferation of Cloud Computing and Big Data
The widespread adoption of cloud services and big data analytics across industries is driving exponential growth in data generation and processing, necessitating robust and scalable data center infrastructure throughout North America.
Increasing Adoption of Artificial Intelligence (AI) and Machine Learning (ML)
AI and ML workloads require significant computational power and storage, prompting organizations to invest in advanced data centers capable of supporting these technologies and enabling innovation in both business operations and data center management.
Expansion of the Internet of Things (IoT) Ecosystem
The surge in IoT devices across sectors like healthcare, automotive, and manufacturing is generating massive volumes of data, fueling demand for data centers with high storage capacity and low latency to process and manage this data efficiently.
Emphasis on Data Privacy and Security Regulations
Stringent data privacy laws and the growing threat of cyberattacks are compelling organizations to invest in secure, compliant data center facilities with advanced cybersecurity features, driving market growth.
Shift Towards Sustainability and Energy Efficiency
Rising energy costs and environmental concerns are pushing data center operators to adopt renewable energy sources and energy-efficient technologies, which not only reduce operational expenses but also align with regulatory and client sustainability requirements.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the North America data center market?
What are the key drivers of growth in the North America data center market?
Which region dominates the North America data center market?
How are sustainability concerns affecting the data center market?
What role does edge computing play in the data center market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Size
- 1.2.1 Small
- 1.2.2 Mid-Sized
- 1.2.3 Large
- 1.3 By Type
- 1.3.1 Enterprise
- 1.3.2 Edge
- 1.3.3 Colocation
- 1.3.4 Hyperscale
- 1.3.5 Managed
- 1.3.6 Modular
- 1.4 By Compound
- 1.4.1 Hardware
- 1.4.2 Data Centre Infrastructure Management Software (Cloud-based)
- 1.4.3 Data Centre Infrastructure Management Software (On-premises)
- 1.4.4 Service
- 1.5 By Industry
- 1.5.1 IT & Telecom
- 1.5.2 BFSI
- 1.5.3 Manufacturing
- 1.5.4 Healthcare
- 1.5.5 Government
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 114,117.78 million → 2032: USD 201,800.26 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North America Data Center Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North America Data Center Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 North America Data Center Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 North America Data Center Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North America Data Center Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North America Data Center Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 North America Data Center Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North America Data Center Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 114,117.78 million → 2032: USD 201,800.26 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North America Data Center Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Size - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Small
- 12.3.7.2 Mid-Sized
- 12.3.7.3 Large
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Enterprise
- 12.4.7.2 Edge
- 12.4.7.3 Colocation
- 12.4.7.4 Hyperscale
- 12.4.7.5 Managed
- 12.4.7.6 Modular
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Compound - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hardware
- 12.5.7.2 Data Centre Infrastructure Management Software (Cloud-based)
- 12.5.7.3 Data Centre Infrastructure Management Software (On-premises)
- 12.5.7.4 Service
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Industry - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 IT & Telecom
- 12.6.7.2 BFSI
- 12.6.7.3 Manufacturing
- 12.6.7.4 Healthcare
- 12.6.7.5 Government
- 12.6.7.6 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 North America Data Center End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 North America Data Center Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Country-Level Shares, 2023
- 14.2 Country Market Size Comparison, 2023
- 14.3 Country Market Forecasts, 2023-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 North America Data Center Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 North America Data Center Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Digital Realty Trust, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Equinix, Inc.
- 18.4 CoreSite (American Tower Corporation)
- 18.5 CyrusOne Inc.
- 18.6 NTT Ltd.
- 18.7 Switch
- 18.8 Vantage Data Centers, LLC
- 18.9 Cyxtera Technologies
- 18.10 Databank Holdings Ltd
- 18.11 Flexential Corp.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

