
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| North America Distributed Acoustic Sensing Market Size 2024 | USD 224.29 million |
| North America Distributed Acoustic Sensing Market, CAGR | 12.04% |
| North America Distributed Acoustic Sensing Market Size 2032 | USD 556.77 million |
Market Overview:
The North America Distributed Acoustic Sensing Market is projected to grow from USD 224.29 million in 2024 to an estimated USD 556.77 million by 2032, with a compound annual growth rate (CAGR) of 12.04% from 2024 to 2032.
The North America Distributed Acoustic Sensing (DAS) market is witnessing growing adoption due to the rising need for advanced, real-time monitoring systems across multiple industries. In the oil and gas sector, DAS technology plays a crucial role in pipeline surveillance, leak detection, and infrastructure integrity monitoring. The power and utility sector leverages DAS to monitor transmission lines, detect faults, and enhance maintenance practices. In transportation, the technology improves safety and operational efficiency by enabling continuous monitoring of infrastructure. Furthermore, increasing security concerns across both public and private sectors are accelerating the deployment of DAS systems for perimeter and infrastructure surveillance. Continued innovations in fiber optic sensing and analytics are also enhancing the performance, accuracy, and cost-effectiveness of DAS solutions, further supporting market expansion.
In North America, the United States dominates the DAS market due to its extensive infrastructure, early adoption of advanced technologies, and strong presence of industries such as oil and gas, utilities, and defense. The country has seen widespread implementation of DAS in critical applications such as pipeline monitoring and border security. Meanwhile, Canada is emerging as a key market for DAS adoption, driven by its vast natural landscapes and regulatory emphasis on environmental protection and infrastructure monitoring. Across the region, the combination of technological maturity, industry-specific requirements, and supportive regulatory frameworks continues to fuel the growth of distributed acoustic sensing solutions.
Market Insights:
- The North America Distributed Acoustic Sensing market is expected to grow from USD 224.29 million in 2024 to USD 556.77 million by 2032, reflecting a CAGR of 12.04%.
- The Global Distributed Acoustic Sensing Market is projected to grow from USD 639.45 million in 2024 to an estimated USD 1596.46 million by 2032, with a compound annual growth rate (CAGR) of 12.12% from 2024 to 2032.
- Oil and gas remains the dominant industry segment, leveraging DAS for real-time pipeline surveillance and infrastructure integrity monitoring.
- Utility and power sectors are expanding DAS use to enhance grid reliability, reduce downtime, and support smart grid implementation.
- Rising security concerns are accelerating the deployment of DAS systems for border surveillance, critical infrastructure protection, and covert threat detection.
- Technological advancements in AI, fiber optics, and machine learning are improving DAS data analysis and supporting wider application across industries.
- High deployment and operational costs, along with challenges in data interpretation and lack of standardization, may restrict adoption in smaller enterprises.
- The United States leads the regional market due to early adoption and robust infrastructure, while Canada is emerging as a fast-growing segment driven by environmental regulations.
Report Scope
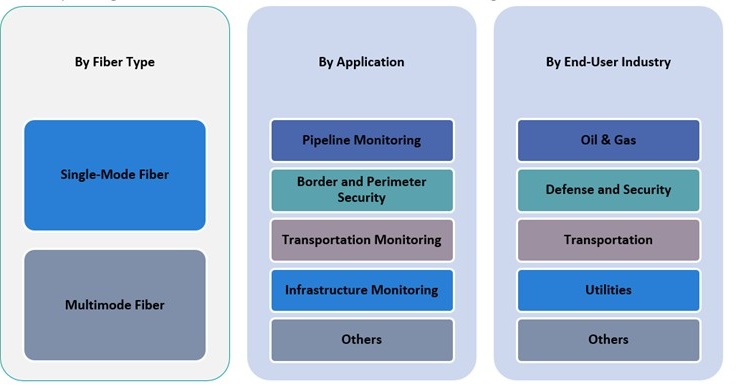
This report segments the North America Distributed Acoustic Sensing Market as follow
Market Drivers:
Rising Demand in Oil and Gas Sector
The oil and gas industry plays a pivotal role in driving the adoption of distributed acoustic sensing solutions in North America. With the region's extensive pipeline infrastructure, there is a heightened need for advanced monitoring systems that ensure safety, operational efficiency, and environmental compliance. DAS technology enables continuous, real-time monitoring of pipelines, allowing early detection of leaks, unauthorized activities, and mechanical stresses. The ability to convert existing fiber optic cables into sensing elements reduces deployment costs while providing comprehensive coverage. As energy companies face stricter regulatory scrutiny and increasing pressure to minimize environmental risks, DAS emerges as a critical solution for maintaining the integrity of energy assets.
Expansion of Utility and Power Infrastructure
Distributed acoustic sensing is gaining traction in the utility and power sectors across North America, driven by the demand for reliable and uninterrupted energy transmission. DAS technology enhances situational awareness for utilities by detecting faults, physical disturbances, and temperature anomalies along power lines. This capability supports predictive maintenance strategies, reduces downtime, and improves grid resilience. As energy providers transition toward smart grid solutions and renewable energy integration, DAS systems offer enhanced monitoring capabilities that align with evolving infrastructure needs. The technology's non-intrusive and cost-effective nature makes it a valuable tool for managing aging power infrastructure and supporting future energy networks.
Heightened Focus on Security and Surveillance
The growing emphasis on national and infrastructural security in North America is further accelerating the adoption of DAS technology. Governments and private enterprises are increasingly deploying DAS systems to safeguard critical assets such as borders, airports, railways, and power plants. The technology provides real-time acoustic data, enabling early threat detection and rapid response to potential intrusions or accidents. Unlike traditional security systems, DAS offers covert surveillance with minimal maintenance and extensive coverage. For example, the U.S. Department of Homeland Security utilizes DAS for border surveillance to identify unauthorized activities in real time. This scalable solution ensures comprehensive perimeter security while minimizing maintenance requirements. As cyber and physical security threats continue to evolve, distributed acoustic sensing offers a scalable and dependable solution that supports comprehensive perimeter security strategies.
Technological Advancements and Integration with Data Analytics
Technological innovation remains a key driver of DAS market growth in North America. Advances in fiber optic technology, artificial intelligence, and machine learning have significantly improved the accuracy, sensitivity, and data interpretation capabilities of DAS systems. These innovations enable the transformation of raw acoustic signals into actionable insights, enhancing decision-making across industries. For instance, AI-powered algorithms can analyze acoustic data to predict maintenance needs or detect anomalies with greater precision. The integration of DAS with digital platforms and centralized monitoring systems allows organizations to automate responses and optimize resource allocation. As enterprises increasingly adopt digital transformation strategies, the value proposition of distributed acoustic sensing as a smart, adaptable monitoring tool becomes more compelling, paving the way for wider implementation across sectors.
Market Trends:
Integration with Edge Computing and IoT Platforms
One of the most prominent trends in the North America DAS market is the growing integration of distributed acoustic sensing systems with edge computing and Internet of Things (IoT) platforms. Organizations across sectors are seeking real-time, decentralized data processing capabilities to reduce latency and enhance responsiveness. By combining DAS with edge devices, businesses can analyze acoustic signals locally, enabling faster threat detection and improved system reliability. For instance, Telus Communications collaborated with MobiledgeX, Inc. to develop the MobiledgeX Early Access Program, which allows developers to test edge-enabled applications in low-latency environments. This integration enhances DAS's ability to analyze acoustic signals locally, providing faster threat detection and improved reliability. Such advancements are particularly beneficial in remote or high-risk areas where immediate insights are critical for safety and operational continuity. As IoT adoption expands across industrial domains, the synergy with DAS is strengthening, contributing to more intelligent and automated infrastructure monitoring.
Adoption in Transportation and Smart City Projects
The deployment of DAS technology in the transportation sector and smart city initiatives is gaining momentum across North America. Urban infrastructure planners are recognizing the value of DAS for traffic monitoring, vibration analysis, and structural health assessments of bridges, tunnels, and railways. By enabling continuous acoustic sensing along fiber optic networks embedded in transportation corridors, municipalities and transport authorities can enhance predictive maintenance, reduce service disruptions, and improve commuter safety. Additionally, as smart cities evolve to incorporate more connected infrastructure, DAS systems are being explored as complementary technologies for integrated urban surveillance and infrastructure health monitoring.
Increased Use in Seismic and Environmental Monitoring
A notable trend in the North American DAS market is the expanding application of the technology in environmental and geophysical monitoring. DAS systems are increasingly used to detect seismic activity, monitor ground movement, and observe environmental phenomena such as landslides and subsidence. Academic institutions, research organizations, and environmental agencies are deploying fiber optic-based DAS to collect high-resolution subsurface data without relying on traditional seismometers. The ability of DAS to convert existing telecom fiber networks into dense sensor arrays presents a cost-effective approach to gathering continuous geotechnical data, especially in regions prone to natural disasters.
Growing Emphasis on Data Fusion and AI-Based Interpretation
As DAS generates vast volumes of acoustic data, organizations are investing in advanced data fusion techniques and AI-driven analytics to extract actionable intelligence. For example, machine learning algorithms are being trained to classify acoustic patterns and predict anomalies with greater accuracy. A notable development is the PhaseNet-DAS model, which refines noisy labels from DAS data to improve earthquake detection and phase arrival-time predictions. A rising trend involves the integration of DAS data with other sensor inputs such as thermal, optical, and pressure data within unified platforms to deliver more comprehensive monitoring capabilities. Machine learning models are being trained to classify acoustic patterns and predict anomalies with greater accuracy. This evolution supports a more proactive approach to risk management and asset performance optimization.
Market Challenges Analysis:
High Deployment and Operational Costs
One of the primary restraints in the North America distributed acoustic sensing market is the high cost associated with deployment and maintenance. While DAS technology offers significant operational advantages, its implementation often involves substantial capital investment in fiber optic infrastructure, signal processing hardware, and software integration. Small and mid-sized enterprises, particularly those outside core industries like oil and gas or utilities, may find the upfront costs prohibitive. Additionally, the requirement for skilled personnel to manage and interpret DAS data further adds to operational expenses, limiting widespread adoption across less resource-intensive sectors.
Complexity in Data Interpretation
Despite advancements in artificial intelligence (AI) and machine learning (ML), interpreting DAS-generated data remains a challenge due to the sheer volume and complexity of acoustic signals. DAS systems generate continuous streams of data that require robust algorithms to filter out environmental noise and extract actionable insights. For example, inconsistent signal quality and variations in installation can lead to false positives or missed detections, complicating real-time decision-making in critical applications such as pipeline monitoring or infrastructure security. Organizations without specialized expertise or advanced analytics platforms often struggle to fully leverage DAS technology, limiting its effectiveness across industries
Limited Standardization and Interoperability
The DAS market in North America also faces challenges related to the lack of standardization and interoperability among various systems and vendors. As organizations adopt different hardware configurations and software protocols, integration becomes more complex and costly. The absence of universally accepted standards limits the ability to scale systems across multiple sites or sectors efficiently. This issue is particularly relevant for large-scale infrastructure operators and government entities, who require seamless compatibility and long-term system sustainability. Addressing standardization gaps will be essential to enabling broader adoption and fostering market maturity.
Market Opportunities:
The North America distributed acoustic sensing market presents significant growth opportunities as industries increasingly prioritize safety, efficiency, and real-time monitoring. The widespread availability of pre-existing fiber optic infrastructure across the region provides a strategic foundation for DAS deployment without requiring extensive new installations. As digital transformation accelerates in sectors such as energy, utilities, transportation, and environmental monitoring, DAS offers a scalable solution for organizations aiming to modernize asset management and operational oversight. The shift toward predictive maintenance and proactive risk mitigation further enhances the appeal of DAS technologies, particularly for enterprises seeking to reduce downtime and improve long-term reliability.
Moreover, the expanding application of DAS in emerging areas such as smart cities, perimeter security, and environmental monitoring creates new avenues for market expansion. Government and municipal investments in infrastructure resilience, disaster preparedness, and intelligent transportation systems open doors for DAS integration into broader digital ecosystems. Additionally, the potential to enhance geophysical research, earthquake detection, and climate monitoring using DAS underscores its value beyond traditional commercial use cases. As advancements in artificial intelligence and edge analytics improve data interpretation capabilities, DAS systems are becoming more accessible and efficient. These evolving technological and policy landscapes collectively position North America as a leading region for distributed acoustic sensing innovation and adoption.
Market Segmentation Analysis:
The North America distributed acoustic sensing market is segmented by fiber type, application, and end-user industry, each contributing uniquely to market development.
By fiber type, single-mode fiber dominates the market due to its superior sensing range, signal integrity, and compatibility with long-distance installations. Its efficiency in large-scale infrastructure projects makes it a preferred choice across industries such as oil and gas and utilities. Multimode fiber, while less prevalent, is used in shorter-range applications where budget constraints and compact infrastructure environments are key considerations.
By application, pipeline monitoring represents the leading segment, driven by the critical need for real-time surveillance and leak detection in the region’s extensive oil and gas infrastructure. Border and perimeter security also account for a substantial share, supported by government initiatives to enhance national and asset protection through advanced sensing technologies. Transportation and infrastructure monitoring are gaining traction, especially within smart city and public safety initiatives, where DAS offers continuous monitoring of structural integrity and transit systems.
By end-user industry, the oil and gas sector remains the dominant contributor to market demand, relying heavily on DAS for asset integrity, safety compliance, and operational efficiency. The defense and security sector is increasingly adopting DAS for surveillance and threat detection, while the transportation sector is integrating the technology into smart infrastructure systems. Utilities are leveraging DAS to monitor power lines and detect faults, enhancing grid reliability. Other industries, including environmental monitoring and research, are also exploring DAS for specialized sensing applications.
Segmentation:
By Fiber Type:
- Single-Mode Fiber
- Multimode Fiber
By Application:
- Pipeline Monitoring
- Transportation Monitoring
- Border and Perimeter Security
- Infrastructure Monitoring
- Others
By End-User Industry:
- Oil & Gas
- Defense and Security
- Transportation
- Utilities
- Others
Regional Analysis:
North America continues to lead the global Distributed Acoustic Sensing (DAS) market, accounting for approximately 31.7% of the total market share in 2023. This dominance is primarily driven by the region's extensive adoption of DAS technology across key industries such as oil and gas, defense, and infrastructure. The widespread pipeline infrastructure in the United States and Canada, coupled with significant investments in advanced monitoring systems, has accelerated the deployment of DAS solutions. Major pipeline operators in both countries utilize DAS for applications including leak detection, intrusion prevention, and seismic monitoring, enhancing safety and operational efficiency.
Within the region, the United States holds a substantial share, representing about 75.3% of the North American DAS market in 2023. This is attributed to the country's advanced oil and gas industry, growing need for critical infrastructure monitoring, and advancements in fiber optics technologies. The U.S. market benefits from a strong presence of key industry players and a proactive approach to adopting innovative sensing technologies. This growth is fueled by Canada's vast natural landscape and environmental concerns, leading to increased utilization of DAS technology for environmental monitoring and compliance in sensitive areas.
Mexico, while currently holding a smaller share of the North American DAS market, is anticipated to witness steady growth in the coming years. The country's expanding infrastructure projects and growing emphasis on security and surveillance are expected to drive the adoption of DAS solutions. As Mexico continues to invest in modernizing its energy and transportation sectors, the demand for real-time monitoring technologies like DAS is likely to increase, contributing to the overall growth of the market in the region.
Key Player Analysis:
- Schlumberger Limited
- Baker Hughes Company
- Halliburton Company
- Silixa Ltd.
- Hifi Engineering Inc.
- OFS Fitel LLC
- AP Sensing GmbH
- Future Fibre Technologies
- OZ Optics Ltd.
- GEOSpace Technologies
Competitive Analysis:
The North America Distributed Acoustic Sensing (DAS) market is characterized by the presence of several key players actively competing through technological innovation, strategic partnerships, and industry-specific solutions. Leading companies such as Halliburton, Schlumberger, Luna Innovations, and OFS Fitel maintain a strong foothold by offering advanced DAS systems tailored for applications in oil and gas, utilities, and defense. These firms invest heavily in research and development to enhance system sensitivity, data interpretation accuracy, and integration with digital platforms. Additionally, partnerships with infrastructure operators and government agencies have enabled broader adoption across critical sectors. Emerging players are entering the market with cost-effective and AI-integrated solutions, intensifying competition and expanding market reach. As customer demand for real-time, reliable, and scalable sensing solutions increases, market participants continue to differentiate through service capabilities, proprietary technologies, and domain expertise. This competitive landscape is expected to drive further innovation and market consolidation in the coming years.
Recent Developments:
- In December 2023, Luna Innovations Inc. acquired Silixa Ltd., a UK-based leader in distributed fiber optic sensing solutions. This strategic acquisition enhanced Luna’s capabilities in distributed acoustic sensing (DAS), distributed temperature sensing (DTS), and distributed strain sensing (DSS), enabling improved performance for applications in energy, natural environments, mining, and defense.
Market Concentration & Characteristics:
The North American Distributed Acoustic Sensing (DAS) market is characterized by a moderate to high level of concentration, with a few key players holding significant market shares. Leading companies such as Halliburton, Schlumberger, Baker Hughes, and Luna Innovations dominate the market, leveraging their extensive experience and technological expertise to offer advanced DAS solutions tailored for various industries, including oil and gas, utilities, and defense. These firms invest heavily in research and development to enhance system sensitivity, data interpretation accuracy, and integration with digital platforms. The market's characteristics are defined by rapid technological advancements, particularly in fiber optic sensing and data analytics. The integration of artificial intelligence and machine learning algorithms has significantly improved the accuracy and reliability of DAS systems, enabling real-time monitoring and predictive maintenance across vast infrastructures. Additionally, the presence of a well-established fiber optic infrastructure in North America facilitates the deployment of DAS technologies, further driving market growth. The region's focus on enhancing security measures and infrastructure monitoring has also contributed to the increased adoption of DAS solutions.
Report Coverage:
The research report offers an in-depth analysis based on Fiber Type, Application and End-User Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increased adoption of DAS in smart infrastructure projects will drive long-term market expansion.
- Technological integration with AI and machine learning will enhance data interpretation and system responsiveness.
- Oil and gas industry will continue to lead demand, especially for leak detection and pipeline security.
- Rising investments in border and perimeter security will boost DAS deployment in defense applications.
- Expansion of renewable energy infrastructure will open new use cases for DAS in utilities.
- Growth of urban transportation networks will accelerate adoption in structural and vibration monitoring.
- Environmental monitoring applications will expand, particularly in seismic and geophysical research.
- Edge computing integration will improve real-time analytics and reduce data processing latency.
- Emergence of cost-effective DAS solutions will encourage adoption among small and mid-sized enterprises.
- Regulatory support for infrastructure safety and monitoring will sustain market momentum across sectors.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand in Oil and Gas Sector
The extensive pipeline infrastructure in North America and the need for real-time leak detection, surveillance, and asset integrity monitoring are driving the adoption of DAS technology in the oil and gas industry. Regulatory pressures and the need to minimize environmental risks further accelerate deployment.
Expansion of Utility and Power Infrastructure
Utilities are increasingly implementing DAS to monitor transmission lines, detect faults, and support predictive maintenance, which enhances grid reliability and reduces downtime. The shift toward smart grids and renewable energy integration is also boosting demand for advanced sensing solutions.
Heightened Focus on Security and Surveillance
Growing security concerns around critical infrastructure, borders, and public assets are leading to increased deployment of DAS systems for real-time perimeter monitoring and threat detection. Government and private sector investments in security are fueling this trend.
Technological Advancements and AI Integration
Continuous innovation in fiber optic sensing, artificial intelligence, and machine learning is improving the accuracy, sensitivity, and data interpretation capabilities of DAS systems. These advancements make DAS more cost-effective and accessible for a wider range of applications.
Integration with Edge Computing and IoT Platforms
The integration of DAS with edge computing and IoT platforms enables decentralized, real-time data processing and faster response times, particularly in remote or high-risk environments. This trend is enhancing the value proposition of DAS for industrial and infrastructure monitoring.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the North America Distributed Acoustic Sensing Market?
What factors are driving the growth of the North America Distributed Acoustic Sensing Market?
What are some challenges faced by the North America Distributed Acoustic Sensing Market?
Who are the major players in the North America Distributed Acoustic Sensing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Fiber Type
- 1.2.1 Single-Mode Fiber
- 1.2.2 Multimode Fiber
- 1.3 By Application
- 1.3.1 Pipeline Monitoring
- 1.3.2 Transportation Monitoring
- 1.3.3 Border and Perimeter Security
- 1.3.4 Infrastructure Monitoring
- 1.3.5 Others
- 1.4 By End-User Industry
- 1.4.1 Oil & Gas
- 1.4.2 Defense and Security
- 1.4.3 Transportation
- 1.4.4 Utilities
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 224.29 million → 2032: USD 556.77 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North America Distributed Acoustic Sensing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North America Distributed Acoustic Sensing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 North America Distributed Acoustic Sensing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 North America Distributed Acoustic Sensing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North America Distributed Acoustic Sensing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North America Distributed Acoustic Sensing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 North America Distributed Acoustic Sensing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North America Distributed Acoustic Sensing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 224.29 million → 2032: USD 556.77 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North America Distributed Acoustic Sensing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Fiber Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Single-Mode Fiber
- 12.3.7.2 Multimode Fiber
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pipeline Monitoring
- 12.4.7.2 Transportation Monitoring
- 12.4.7.3 Border and Perimeter Security
- 12.4.7.4 Infrastructure Monitoring
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oil & Gas
- 12.5.7.2 Defense and Security
- 12.5.7.3 Transportation
- 12.5.7.4 Utilities
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 North America Distributed Acoustic Sensing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 North America Distributed Acoustic Sensing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 North America Distributed Acoustic Sensing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 North America Distributed Acoustic Sensing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Schlumberger Limited
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Baker Hughes Company
- 18.4 Halliburton Company
- 18.5 Silixa Ltd.
- 18.6 Hifi Engineering Inc.
- 18.7 OFS Fitel LLC
- 18.8 AP Sensing GmbH
- 18.9 Future Fibre Technologies
- 18.10 OZ Optics Ltd.
- 18.11 Luna Innovations Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

