
North America Genotoxicity Testing Services Market
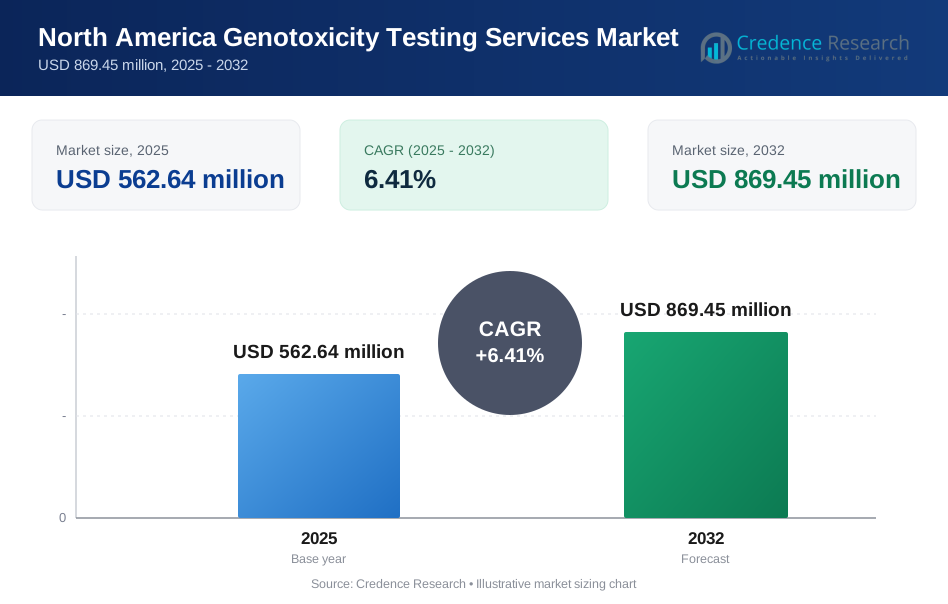
The North America Genotoxicity Testing Services Market increased from USD 341.02 million in 2018 to USD 562.64 million in 2025 and is projected to reach USD 869.45 million by 2032, growing at a CAGR of 6.41% during 2025–2032. This growth reflects steady, compliance-led demand for genotoxicity assessment across regulated development programs, particularly in pharmaceuticals and biotechnology, where safety screening is required to support clinical progression and regulatory submissions. North America continues to benefit from a mature outsourcing ecosystem with established GLP infrastructure and submission-ready reporting.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| North America Genotoxicity Testing Services Market Size 2025 | USD 562.64 million |
| North America Genotoxicity Testing Services Market, CAGR | 6.41% |
| North America Genotoxicity Testing Services Market Size 2032 | USD 869.45 million |
Key Market Trends & Insights
- The market grew from USD 341.02 million in 2018 to USD 562.64 million in 2025 and is expected to reach USD 869.45 million by 2032, supported by sustained outsourcing and compliance-driven testing demand.
- In vitro tests accounted for 65% in 2025, driven by faster turnaround needs and scalable screening in early safety assessment workflows.
- Pharmaceutical and biotechnology accounted for 48% in 2025, reflecting mandatory genotoxicity screening across development stages and higher study volumes versus other end markets.
- North America’s overall growth is expected to average 6.36% CAGR (2025–2032), supported by continued investment in regulated testing capacity and advanced in vitro adoption.
- By 2032, the U.S. is expected to hold 87.33% share of the regional market, supported by a 6.53% CAGR, indicating concentration of high-value GLP-compliant testing activity.
Segment Analysis
Demand in North America is shaped by the need to de-risk pipelines early and maintain submission timelines, which supports routine genotoxicity packages and repeat testing across development milestones. Buyers prefer providers that can run standard assay batteries with predictable timelines and deliver reports aligned to regulatory expectations, making quality systems and audit history central to vendor selection. Faster early screening also increases the role of in vitro assays, especially where programs require rapid go/no-go decisions and consistent documentation.
Across applications, regulated industries such as pharmaceutical and biotechnology drive the highest testing intensity due to mandated safety requirements and larger portfolios moving through development. Chemicals and agrochemicals contribute steady volumes tied to compliance and hazard classification programs, while cosmetics and personal care increasingly prioritize alternative methods and human-relevant approaches. Food and beverages and other categories typically reflect targeted use cases tied to ingredient safety and specialized risk assessments.
By Test Type Insights
In Vitro Tests accounted for the largest share of 65% in 2025. Sponsors prioritize in vitro panels to accelerate early hazard identification and support higher throughput decision-making across compound libraries. Standardized protocols and predictable turnaround strengthen adoption for programs operating under strict development timelines. Improved human-relevant models and method refinements also increase confidence in in vitro outputs before selectively escalating to in vivo confirmation where required.
By Service Providers Insights
Service provider selection in genotoxicity testing services typically concentrates around GLP readiness, assay breadth, and the ability to deliver submission-quality reporting with consistent timelines. Independent toxicology labs and CRO-style providers often compete on study management, capacity availability, and validated method depth across common assays. Company-based testing can remain important for high-volume pipelines where scheduling control and internal governance requirements are critical.
By Application Insights
Pharmaceutical and Biotechnology accounted for the largest share of 48% in 2025. Drug development programs require genotoxicity evaluation to reduce late-stage attrition risk and support regulatory filings, sustaining high testing frequency. Biotech pipelines increase demand further as sponsors run multiple programs in parallel and rely on outsourced capacity for submission timelines. Adjacent end markets contribute incremental volumes, but regulated pharma and biotech typically set the pace for service demand and pricing dynamics.
North America Genotoxicity Testing Services Market Drivers
Regulatory-Driven Safety Testing Requirements
Genotoxicity testing remains a foundational requirement across regulated development and safety programs, which keeps baseline demand resilient across cycles. Sponsors must demonstrate mutagenicity and genotoxic risk control before advancing candidates, sustaining routine assay packages and repeat testing needs. This requirement extends beyond pharmaceuticals into chemicals, agrochemicals, and other regulated categories, supporting multi-industry demand. Service providers with validated methods and submission-ready reporting benefit from consistent compliance-driven volumes.
- For instance, under OECD Test No. 471, laboratories such as Nelson Labs routinely run bacterial reverse mutation assays using at least five Salmonella typhimurium and Escherichia coli strains to detect point mutations, providing GLP-compliant data packages that are directly accepted in global regulatory submissions for pharmaceuticals, medical devices, and chemicals.
Outsourcing Growth and Study Volume Expansion
Sponsors increasingly outsource genetic toxicology work to manage capacity constraints and maintain predictable timelines across multiple development programs. Outsourcing supports access to broader assay panels, experienced study management, and established quality systems without heavy internal fixed costs. Higher pipeline complexity and parallel program execution increase testing throughput requirements, which favors providers with scalable lab operations. This dynamic supports steady service utilization across both early screening and confirmatory workflows.
Shift Toward Faster Screening and Human-Relevant Methods
Speed and predictivity requirements continue to elevate demand for in vitro workflows that can deliver early hazard signals and support rapid development decisions. Method improvements and broader acceptance of alternative approaches increase confidence in human-relevant systems, particularly where programs aim to reduce uncertainty early. These shifts support higher utilization of standardized in vitro batteries and targeted escalation strategies. Providers that combine speed, reproducibility, and strong documentation are positioned to capture incremental demand.
- For instance, AstraZeneca has implemented an automated high-content, high-throughput in vitro micronucleus assay that has screened more than 1,000 small-molecule compounds in just 14 independent runs, using machine-learning–enabled image analysis to classify aneugenic and clastogenic responses with approximately 95% accuracy while reducing analysis time by around 80% compared with traditional manual approaches.
Concentration of High-Value GLP Infrastructure in the U.S.
North America’s regional demand remains concentrated where GLP-compliant infrastructure, specialized expertise, and regulatory-ready documentation are most available. The U.S. continues to attract high-value programs, including complex development portfolios that require repeat testing and tight coordination. This concentration supports higher service intensity, deeper assay coverage, and stronger capacity investment. Regional leadership also reinforces buyer preference for established quality systems and audit-ready operations.
North America Genotoxicity Testing Services Market Challenges
Genotoxicity testing services face operational constraints tied to study scheduling, validated method maintenance, and the need to align outputs with evolving regulatory expectations. Maintaining consistent turnaround times can be difficult when study demand spikes, particularly for specialized assays or confirmatory in vivo work that requires constrained resources and longer lead times. Providers must also invest continuously in training, quality systems, and instrumentation to keep methods current and defensible for submissions.
- For instance, Charles River Laboratories reports delivering approximately 40,000 biologics testing reports annually across global sites with 95% of statements of work (SOWs) issued in under 4 days, illustrating the scale at which scheduling and method control must be managed to maintain predictable study starts and regulatory-compliant documentation.
Cost pressures and procurement scrutiny create additional friction, especially when sponsors seek faster timelines without proportional budget increases. Complex programs may require customized study designs or expanded method packages, which increases cost and coordination effort. In addition, method comparability and cross-site consistency can be challenging when studies span multiple labs or provider networks. These factors can extend project timelines and increase rework risk if expectations are not aligned upfront.
North America Genotoxicity Testing Services Market Trends and Opportunities
Demand is trending toward integrated study packages that combine early in vitro screening with targeted confirmatory strategies to manage both speed and regulatory robustness. Sponsors increasingly prefer providers that can coordinate multiple assays, streamline documentation, and deliver consistent reporting formats that support submission readiness. This trend supports opportunities for providers that offer end-to-end genetic toxicology workflows, strong project management, and capacity visibility.
Opportunities also expand as more programs emphasize alternative methods and human-relevant models to improve predictivity and reduce reliance on animal testing. Providers that invest in advanced in vitro systems, method validation, and clear positioning for regulatory acceptance can differentiate in competitive bids. Continued growth in biotech innovation and outsourced development workflows supports sustained service utilization across North America. This environment favors providers that balance scientific depth with operational scalability.
- For instance, Toxys’ ToxTracker assay has undergone multi-laboratory validation in seven expert laboratories, delivering high intra- and inter-laboratory reproducibility and showing strong correlation with standard regulatory assays, and is currently under OECD review as a New Approach Methodology in genetic toxicology.
Regional Insights
U.S.
The U.S. remains the primary growth engine for genotoxicity testing services in North America, supported by a dense biopharma R&D base and strong demand for GLP-compliant, submission-ready study execution. The regional share is projected to reach 87.33% by 2032, supported by a 6.53% CAGR (2025–2032), reflecting continued concentration of high-value testing programs and outsourcing activity.
Canada
Canada is expected to maintain a meaningful but comparatively smaller role in the regional market as sponsors continue to prioritize scale and throughput availability. The share is projected to moderate to 8.72% by 2032, growing at a 5.73% CAGR (2025–2032), with demand supported by cross-border projects and steady growth in regulated testing capacity.
Mexico
Mexico is anticipated to expand at a slower pace relative to the U.S. and Canada, primarily due to slower scaling of high-value GLP-compliant testing infrastructure. The share may decline to 3.95% by 2032, supported by a 4.19% CAGR (2025–2032), with growth linked mainly to cost-sensitive outsourcing and select capacity additions.
Competitive Landscape
Competition centers on GLP readiness, validated assay breadth, and the ability to deliver submission-quality reporting on predictable timelines. Providers differentiate through capacity scale, turnaround consistency, study management quality, and the ability to support integrated test batteries that reduce coordination burden for sponsors. Strategic focus often includes expansion of lab capacity, method upgrades aligned to evolving expectations, and broader service integration across preclinical safety programs.
Charles River Laboratories maintains a strong position in regulated safety assessment services through integrated scientific capabilities, established quality systems, and scalable testing infrastructure. Its approach aligns with sponsor demand for predictable timelines, broad assay availability, and documentation that supports regulatory submissions. The company’s participation in method validation and alternative-method adoption also supports differentiation in in vitro-forward workflows.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Charles River Laboratories
- Labcorp Drug Development
- Eurofins Scientific
- BioReliance
- SGS S.A.
- NAMSA
- Scantox
- Toxys
- ICON plc
- ITR Laboratories Canada Inc.
- Others
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In October 2025, Charles River Laboratories announced a collaboration focused on validating newer alternative methods for toxicology applications, expanding access to advanced in vitro approaches for clients.
- In September 2024, Scantox Group announced the acquisition of Gentronix Ltd, a UK-based GLP-compliant genetic toxicology contract research organization, expanding Scantox’s genetic toxicology service platform to better support pre-IND enabling studies and a broader global customer base.
- In August 2024, SGS S.A. introduced new specialized bioanalytical testing services at its state-of-the-art laboratory in Hudson, New Hampshire, enhancing support for discovery through phase 1–3 clinical trials for North American pharmaceutical and biopharmaceutical customers via expanded bioanalytical capabilities and a partnership with Agilex Biolabs.
Report Scope
| Report Attribute | Details |
| Historic year | 2018 |
| Historic year market size | USD 341.02 million |
| Market size value in 2025 | USD 562.64 million |
| Revenue forecast in 2032 | USD 869.45 million |
| Growth rate (CAGR) | 6.41% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026–2032 |
| Quantitative units | USD million |
| Segments covered | By Test Type; By Service Providers; By Application; By Region |
| Regional scope | North America; Europe; Asia Pacific; Latin America; Middle East & Africa |
| Key companies profiled | Charles River Laboratories; Labcorp Drug Development; Eurofins Scientific; BioReliance; SGS S.A.; NAMSA; Scantox; Toxys; ICON plc; ITR Laboratories Canada Inc.; Others |
Segmentation
BY TEST TYPE
- In Vitro Tests
- In Vivo Tests
BY SERVICE PROVIDERS
- Independent Toxicology
- Labs
- Research Facilities
- Company Based
- Toxicology Labs
BY APPLICATION
- Pharmaceutical and Biotechnology
- Chemicals and Agrochemicals
- Cosmetics and Personal Care
- Food and Beverages
- Others
BY REGION
- U.S.
- Canada
- Mexico
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size and growth outlook for the North America Genotoxicity Testing Services Market?
What is driving growth in genotoxicity testing services across North America?
Which test type leads the market?
Which application segment contributes the most revenue?
Which country leads the North America market, and how is it expected to evolve?
Who are the key players operating in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 562.64 million → 2032: USD 869.45 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North America Genotoxicity Testing Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North America Genotoxicity Testing Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 North America Genotoxicity Testing Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 North America Genotoxicity Testing Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North America Genotoxicity Testing Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North America Genotoxicity Testing Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 North America Genotoxicity Testing Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North America Genotoxicity Testing Services Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 562.64 million → 2032: USD 869.45 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North America Genotoxicity Testing Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 North America Genotoxicity Testing Services Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Country-Level Shares, 2025
- 13.2 Country Market Size Comparison, 2025
- 13.3 Country Market Forecasts, 2025-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 North America Genotoxicity Testing Services Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2025-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 North America Genotoxicity Testing Services Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

