
Market Overview
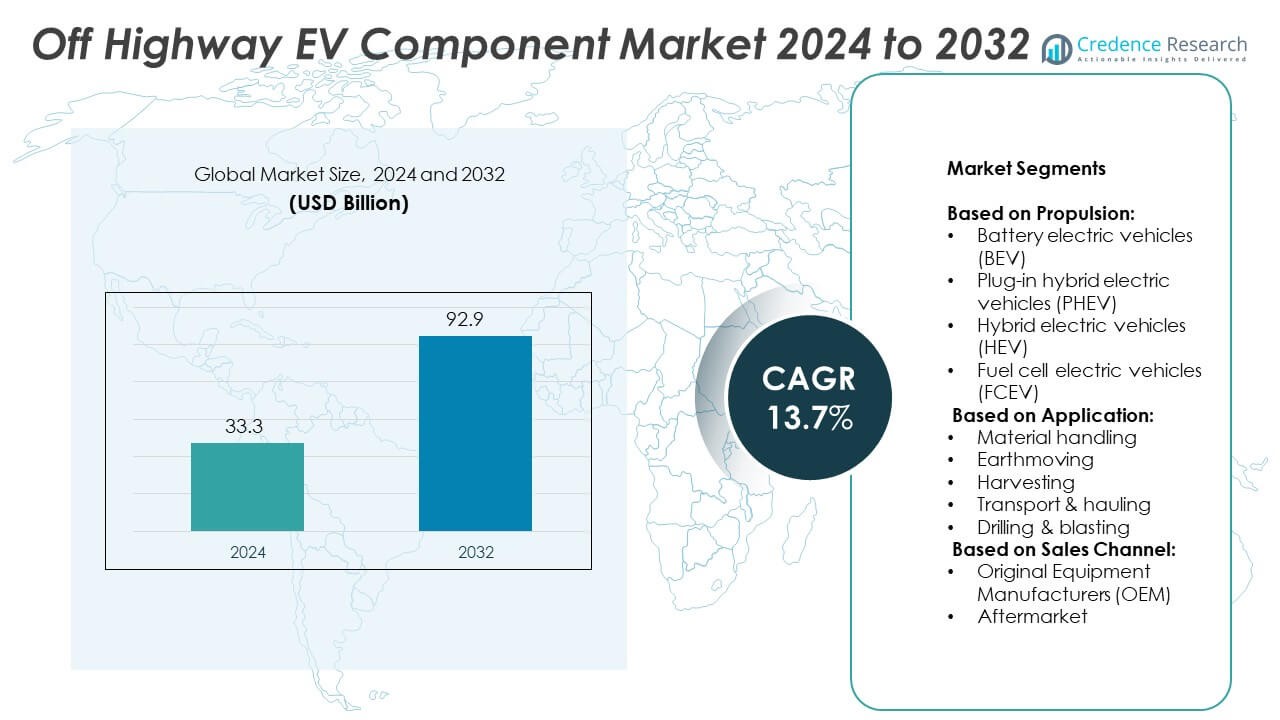
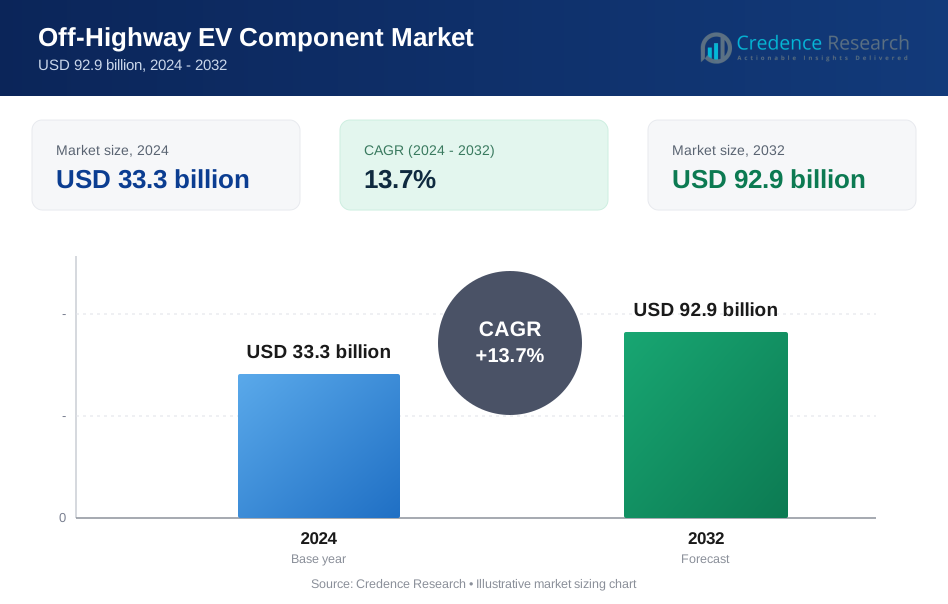
Off Highway EV Component Market size was valued at USD 33.3 billion in 2024 and is anticipated to reach USD 92.9 billion by 2032, at a CAGR of 13.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Off Highway EV Component Market Size 2024 | USD 33.3 Billion |
| Off Highway EV Component Market, CAGR | 13.7% |
| Off Highway EV Component Market Size 2032 | USD 92.9 Billion |
The Off Highway EV Component market grows rapidly due to rising electrification across construction, agriculture, and mining sectors. Increasing demand for energy-efficient solutions, government emission regulations, and sustainability goals drive adoption. Advancements in battery technologies, smart powertrain systems, and IoT integration enhance performance and operational efficiency. Growing investments in charging infrastructure and innovative EV components further accelerate market expansion. Collaboration between OEMs and technology providers supports development of advanced solutions, positioning the market for significant long-term growth.
The Off Highway EV Component market shows strong growth across Asia Pacific, North America, and Europe, driven by rising electrification and technological innovation. Asia Pacific leads adoption with rapid industrialization and infrastructure development, while North America focuses on advanced battery technologies and smart systems. Europe emphasizes sustainability and stringent emission regulations, boosting electric equipment demand. Key players such as Caterpillar, Komatsu, Volvo AB, and Deere & Company invest heavily in research, partnerships, and innovative solutions to enhance market competitiveness globally.
Market Insights
- The Off Highway EV Component market was valued at USD 33.3 billion in 2024 and is projected to reach USD 92.9 billion by 2032, growing at a CAGR of 13.7% during the forecast period.
- Rising demand for electrification in construction, mining, and agriculture drives market expansion, supported by government regulations and sustainability initiatives.
- Advancements in battery technologies, IoT integration, and smart powertrain systems create strong growth opportunities and enhance operational efficiency in off-highway vehicles.
- The market is highly competitive, with key players like Caterpillar, Komatsu, Volvo AB, and Deere & Company investing in innovation, partnerships, and advanced EV components to strengthen their global presence.
- High initial costs, limited charging infrastructure, and technical challenges in heavy-duty vehicle electrification act as restraints, slowing adoption in some regions.
- Asia Pacific leads the market due to rapid industrialization, infrastructure growth, and manufacturing strength, while North America and Europe focus on sustainability, technological innovation, and regulatory compliance.
- Emerging economies in Latin America and the Middle East & Africa offer significant growth potential, driven by fleet modernization, supportive policies, and increasing adoption of energy-efficient off-highway machinery.
Market Drivers
Rising Adoption of Electrification in Off-Highway Vehicles
The Off Highway EV Component market experiences strong growth driven by rapid electrification trends. Construction, agriculture, and mining industries increasingly shift toward electric powertrains to reduce emissions. Governments promote clean energy adoption through stricter regulations and incentive programs. Manufacturers integrate advanced battery systems, motors, and controllers for improved performance and efficiency. Growing environmental awareness encourages fleet owners to replace diesel-powered equipment with electric alternatives. This transition accelerates demand for high-performance EV components supporting sustainable operations.
- For instance, Sandvik has deployed a fleet of over 600 electric off‑highway units, including loaders, trucks, and drill rigs.
Advancements in Battery Technologies Enhancing Vehicle Performance
Lithium-ion and solid-state battery developments improve energy density and charging efficiency, fueling market expansion. The Off Highway EV Component market benefits from extended operational hours and lower maintenance requirements due to advanced battery designs. Manufacturers focus on producing compact, lightweight batteries with higher power output. Fast-charging technologies reduce downtime, supporting continuous equipment usage in demanding environments. Integration of battery management systems ensures greater safety and reliability. These advancements strengthen adoption across heavy-duty applications, increasing demand for premium components.
- For instance, a major mining application, such as the electrification of a 100-tonne haul truck, Xerotech supplied six modular battery packs, each rated at 290 kWh, which are connected together. These packs contain many thousands of individual cells to achieve the required energy capacity, but the final count depends on the specific battery configuration
Government Regulations and Incentives Driving Market Expansion
Stringent emission norms and sustainability goals drive industries to adopt electric-powered machinery. The Off Highway EV Component market sees rising investments due to policy-driven transitions from diesel to electric solutions. Governments introduce tax benefits, subsidies, and funding for research on EV technologies. Infrastructure development, including charging stations for off-highway vehicles, boosts overall adoption. Regulatory mandates encourage OEMs to innovate and deliver efficient, eco-friendly components. This support fosters wider electrification across multiple off-highway applications globally.
Integration of Smart Technologies for Operational Efficiency
IoT-enabled systems and advanced telematics optimize electric vehicle operations and maintenance schedules. The Off Highway EV Component market benefits from predictive analytics improving battery performance and overall machine uptime. Real-time data tracking enhances energy management, reducing operational costs for fleet operators. Manufacturers integrate intelligent power distribution units and control systems to maximize efficiency. AI-driven software assists in monitoring equipment health and extending component life cycles. These innovations accelerate the adoption of electric systems across the off-highway equipment landscape.
Market Trends
Growing Shift Toward Electrification Across Off-Highway Applications
The Off Highway EV Component market shows a strong transition from diesel-powered equipment to electric alternatives. Industries like construction, agriculture, and mining increasingly prefer electric machines for better efficiency and lower emissions. Manufacturers introduce advanced electric drivetrains to improve performance and meet sustainability targets. Rising fuel costs encourage operators to adopt electric solutions for long-term savings. Increased awareness of carbon reduction drives global demand for eco-friendly components. This shift creates growth opportunities for innovative suppliers supporting electric transformation.
- For instance, public listings show 325 models of electric and zero-emission construction and mining equipment included in a regulatory clean equipment list
Advancements in Powertrain and Energy Storage Technologies
Innovations in battery energy density, charging speed, and motor efficiency influence market dynamics significantly. The Off Highway EV Component market gains momentum with improved lithium-ion and solid-state battery technologies. Compact, high-capacity batteries enable extended machine operation with minimal downtime. Manufacturers develop efficient powertrain systems integrating smart controllers and regenerative braking technologies. High-voltage architectures enhance energy utilization while reducing overall weight and maintenance costs. These advancements strengthen adoption across heavy-duty sectors seeking reliable electric solutions.
- For instance, the electrification of material handling is a significant trend, driven by regulations and market demand. A July 2024 fact sheet from the California Air Resources Board (CARB) indicates that the number of certified zero-emission forklifts on their "Advanced Clean Off-Road Equipment" (ACE) list was 394 at that time.
Rising Integration of IoT and Telematics in EV Systems
Connected technologies enable real-time monitoring and improved operational efficiency in off-highway machinery. The Off Highway EV Component market benefits from IoT-enabled systems tracking battery health and performance. Telematics solutions provide predictive maintenance insights, reducing unexpected failures. Integration of AI-based analytics optimizes energy consumption and improves equipment uptime. Fleet managers leverage data-driven insights to enhance productivity and cost control. These intelligent technologies accelerate the adoption of smart, efficient EV components globally.
Increasing Investments and Collaborations Among Industry Players
Global manufacturers focus on strategic partnerships to advance electric vehicle technologies and infrastructure. The Off Highway EV Component market experiences rapid investment growth from OEMs and technology providers. Companies collaborate to develop innovative motors, batteries, and charging solutions tailored for heavy-duty applications. Expanding research efforts aim to achieve higher energy efficiency and lower production costs. Joint ventures between component makers and equipment manufacturers strengthen market competitiveness. This trend drives large-scale electrification across the off-highway equipment sector worldwide.
Market Challenges Analysis
High Initial Costs and Limited Charging Infrastructure
The Off Highway EV Component market faces significant challenges due to high upfront investment requirements. Electric powertrains, advanced batteries, and control systems increase equipment costs for manufacturers and end-users. Many operators in construction, agriculture, and mining hesitate to transition because of uncertain return on investment. Limited availability of fast-charging infrastructure in remote locations further slows adoption. It requires substantial funding to develop reliable charging networks that support heavy-duty operations. These cost-related barriers restrict large-scale deployment across multiple off-highway applications.
Technical Limitations and Supply Chain Constraints
Performance optimization of batteries and motors for demanding off-highway environments remains complex. The Off Highway EV Component market struggles with balancing energy efficiency, durability, and operational range. Extreme weather, high loads, and rough terrains challenge system reliability. Global supply chain disruptions create shortages of critical components such as semiconductors and lithium. It impacts production timelines and delays equipment delivery across key sectors. Manufacturers invest heavily in research to overcome technical limitations and ensure stable supply availability.
Market Opportunities
Expanding Demand for Sustainable and Energy-Efficient Equipment
The Off Highway EV Component market presents strong opportunities due to rising global focus on sustainability. Governments implement stricter emission regulations, driving industries to adopt electric-powered machinery. Operators seek energy-efficient solutions to reduce operational costs and meet environmental targets. Manufacturers develop advanced battery systems, motors, and control technologies to enhance performance and productivity. It creates growth potential for suppliers offering innovative and eco-friendly components. Increasing investments in green technologies support widespread adoption across construction, agriculture, and mining sectors.
Growing Infrastructure Development and Technological Innovation
Rapid advancements in charging infrastructure and smart energy solutions create significant market prospects. The Off Highway EV Component market benefits from ongoing investments in fast-charging systems and high-capacity batteries. Integration of IoT-enabled monitoring and AI-driven analytics enhances operational efficiency and machine performance. Manufacturers explore opportunities in developing modular, scalable EV components tailored for diverse applications. It drives collaboration between OEMs, technology providers, and energy companies to accelerate adoption. Expanding electrification projects in emerging economies further strengthen future market growth potential.
Market Segmentation Analysis:
By Propulsion:
The Off Highway EV Component market is segmented into battery electric vehicles (BEV), plug-in hybrid electric vehicles (PHEV), hybrid electric vehicles (HEV), and fuel cell electric vehicles (FCEV). BEVs lead the segment due to their zero-emission capabilities and lower operating costs. Manufacturers focus on developing high-capacity batteries to support longer operating hours in demanding conditions. PHEVs gain traction in sectors requiring flexibility between electric and fuel-based systems. HEVs remain popular in regions with limited charging infrastructure, offering better fuel efficiency and reduced emissions. FCEVs show growing potential, particularly in applications requiring extended range and high-power output, supported by ongoing hydrogen infrastructure developments.
- For instance, Komatsu has deployed more than 875 autonomous haul haul trucks that have collectively transported over 10 billion metric tonnes of material using electric-drive technology.
By Application:
The market is categorized into material handling, earthmoving, harvesting, transport and hauling, and drilling and blasting. Material handling equipment, including forklifts and loaders, holds a significant share due to rising warehouse automation and industrial electrification. The earthmoving segment shows rapid growth, driven by construction and mining projects requiring high-performance components. Harvesting equipment adoption rises with precision farming techniques and increasing demand for sustainable agricultural practices. Transport and hauling applications benefit from the shift toward electrification in logistics and mining sectors. Drilling and blasting equipment gradually adopts electric systems to reduce emissions and improve operational efficiency in extreme environments.
- For instance, Volvo Construction Equipment’s L120 Electric wheel loader features a 22‑ton operating weight, a 6‑ton lifting capacity, and a 282-kWh battery delivering up to nine hours of runtime per charge.
By Sales Channel:
The market is divided into original equipment manufacturers (OEM) and aftermarket. OEMs dominate the segment due to rising production of electric-powered equipment and strong collaborations with technology providers. Manufacturers invest in integrating advanced EV components into new machinery to meet regulatory and efficiency demands. The aftermarket segment gains momentum with the growing need for replacement batteries, motors, and control systems. It supports long-term operational performance and enhances the life cycle of off-highway vehicles. Both channels contribute significantly to expanding the overall market presence and driving continuous innovation.
Segments:
Based on Propulsion:
- Battery electric vehicles (BEV)
- Plug-in hybrid electric vehicles (PHEV)
- Hybrid electric vehicles (HEV)
- Fuel cell electric vehicles (FCEV)
Based on Application:
- Material handling
- Earthmoving
- Harvesting
- Transport & hauling
- Drilling & blasting
Based on Sales Channel:
- Original Equipment Manufacturers (OEM)
- Aftermarket
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
The region holds a commanding 30% share of the global Off Highway EV Component market. Its strong position stems from government incentives, sustainable policies, and rapidly expanding infrastructure. The United States and Canada lead growth, driven by electrification in construction, mining, and agriculture sectors. It benefits from substantial investment in charging networks and research collaborations between OEMs and technology firms. Growing adoption of BEVs and hybrid platforms fuels demand for high-performance components. Manufacturers focus on rugged, efficient batteries and electric drivetrains tailored to heavy-duty operations. The region’s advanced regulatory frameworks and financial support enhance its competitive edge.
Europe
Europe delivers approximately 25% of the global Off Highway EV Component market share. The region’s share stems from stringent emission standards, government subsidy schemes, and strong sustainability mandates. Key markets such as Germany, UK, and France push heavy machinery electrification in construction and agriculture. It shows rising demand for sophisticated EV components featuring smart control systems and high-density batteries. Collaboration between OEMs and energy firms accelerates charging infrastructure rollout. Component makers tailor solutions to meet tougher safety and performance regulations. Europe’s green industrial strategy underpins long-term market stability and innovation.
Asia Pacific
Asia Pacific commands the largest share at 35% of the Off Highway EV Component market, led by China and India. Urbanization, infrastructure expansion, and industrial electrification drive robust growth. It taps into deep supply chains, local manufacturing strength, and government backing for electric machinery. Component makers in the region ramp up production of cost-efficient batteries, motors, and power electronics. Manufacturers leverage IoT integration and modular designs to meet diverse application needs. Rapid adoption across mining and agriculture sectors strengthens demand. The region’s scale and manufacturing advantages position it as a global leader in off‑highway EV components.
Latin America
Latin America accounts for roughly 5% of the global Off Highway EV Component market. Adoption lags due to limited infrastructure and higher equipment costs. It shows early signs of growth in infrastructure projects and mining operations. Governments begin exploring EV incentives and subsidies for heavy machinery. Component suppliers target opportunities in fleet modernization and energy-efficient equipment deployment. Modular, lower-cost solutions make inroads in agriculture and construction sectors. The region holds long-term potential as policy shifts and funding improve market viability.
Middle East & Africa
This region contributes about 5% of the global Off Highway EV Component market share. Growth remains modest due to infrastructure gaps, regulatory challenges, and capital limitations. It reveals niche demand in mining and specialized material handling operations. Governments gradually promote cleaner technologies in key industries. Component providers explore opportunities in fleet electrification and renewable energy integration. Durability and compatibility with harsh environments guide component design. Expansion depends on policy support, infrastructure investment, and regional collaboration.
Key Player Analysis
- Liebherr
- Tata Elxsi
- Volvo AB
- Sona Comstar
- Komatsu
- Kubota
- Caterpillar
- Hitachi Construction Machinery
- Tata AutoComp
- Deere & Company
Competitive Analysis
The Off Highway EV Component market is highly competitive, with leading players including Caterpillar, Deere & Company, Hitachi Construction Machinery, Komatsu, Kubota, Liebherr, Sona Comstar, Tata AutoComp, Tata Elxsi, and Volvo AB. These companies focus on technological innovation, strategic partnerships, and expanding product portfolios to strengthen their market positions. They invest heavily in developing advanced batteries, electric drivetrains, and control systems to meet growing demand for sustainable and high-performance solutions. Strong research and development initiatives enable them to improve efficiency, durability, and energy optimization in off-highway machinery. Manufacturers emphasize collaboration with OEMs and technology providers to enhance integration of EV components across applications such as construction, agriculture, and mining. Market leaders also expand their global footprints by leveraging production capabilities, local partnerships, and aftersales networks. Increasing competition drives continuous improvements in product quality, cost-effectiveness, and operational reliability, ensuring sustained growth in a rapidly evolving industry landscape.
Recent Developments
- In 2025, Caterpillar also showcased investments in autonomy, connectivity, alternative fuels, and electrification at CES.
- In 2025, Deere unveiled its autonomy kit for large tractors and expanded capabilities for its 9RX autonomous tillage tractor.
- In February 2025, global private equity firm Carlyle acquired controlling stakes in India's Roop Automotives and Highway Industries, merging them to form a diversified global auto parts platform. The new platform, backed by Carlyle Asia Partners, manufactures forged and precision-machined components, steering assemblies, and powertrain parts for electric, hybrid, and internal combustion engine (ICE) vehicles.
Report Coverage
The research report offers an in-depth analysis based on Propulsion, Application, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for electric drivetrains will rise in construction, agriculture, and mining.
- Manufacturers will optimize battery systems for extended run-time and durability.
- Integration of smart controls and IoT will increase component efficiency.
- Growth in charging infrastructure will support remote, heavy-duty equipment.
- OEMs will form partnerships with tech firms to innovate EV components.
- Governments will expand subsidies and policies to boost sector electrification.
- Suppliers will develop modular components for scalability across applications.
- Fuel cell and hydrogen hybrid systems will gain momentum for high-load tasks.
- Aftermarket services will expand to support maintenance of EV systems.
- Adoption in emerging markets will grow as infrastructure and funding improve.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Off Highway EV Component market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Off Highway EV Component Market projected to grow between 2025 and 2032?
Which Off Highway EV Component market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Off Highway EV Component market?
Who are the leading companies in the Off Highway EV Component Market?
Which region commanded the largest share of the Off Highway EV Component market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Off-Highway EV Component Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Off-Highway EV Component Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 33.3 billion → 2032: USD 92.9 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Off-Highway EV Component Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Off-Highway EV Component Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Off-Highway EV Component Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Off-Highway EV Component Market Drivers
- 3.3 Off-Highway EV Component Market Restraints & Challenges
- 3.4 Off-Highway EV Component Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Off-Highway EV Component Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Off-Highway EV Component Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Off-Highway EV Component category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Off-Highway EV Component Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Off-Highway EV Component Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Off-Highway EV Component market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Off-Highway EV Component Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Off-Highway EV Component Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Off-Highway EV Component Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Off-Highway EV Component (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Off-Highway EV Component Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Off-Highway EV Component Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Off-Highway EV Component Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Off-Highway EV Component Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Off-Highway EV Component Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Off-Highway EV Component Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Off-Highway EV Component Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Off-Highway EV Component Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Off-Highway EV Component Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
