
Market Overview
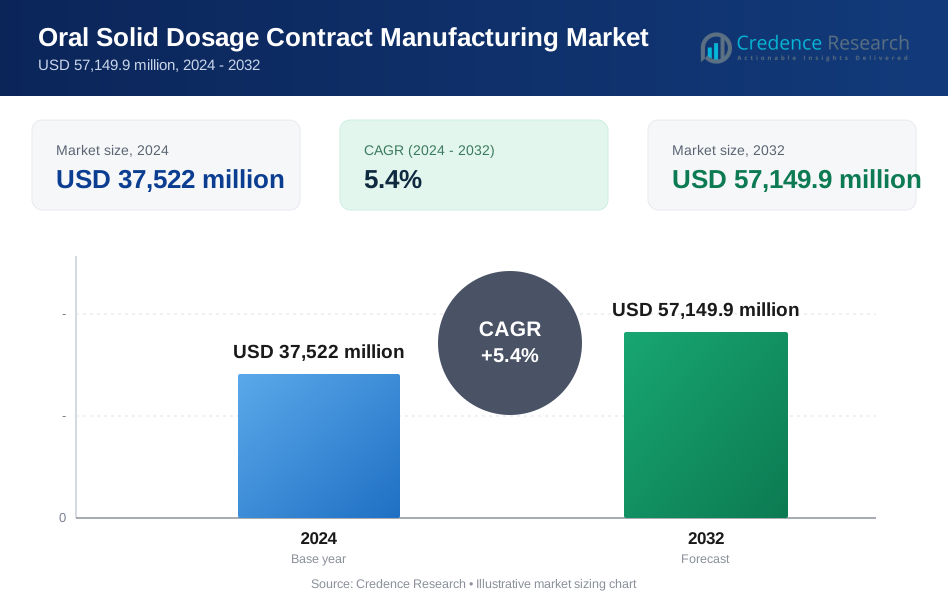
The Oral Solid Dosage Contract Manufacturing Market was valued at USD 37,522 million in 2024 and is projected to reach USD 57,149.9 million by 2032, expanding at a CAGR of 5.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Oral Solid Dosage Contract Manufacturing Market Size 2024 | USD 37,522 Million |
| Oral Solid Dosage Contract Manufacturing Market, CAGR | 5.4% |
| Oral Solid Dosage Contract Manufacturing Market Size 2032 | USD 57,149.9 Million |
The Oral Solid Dosage Contract Manufacturing market is driven by leading players such as Jubilant Pharmova Limited, Lonza, Siegfried Holding AG, Piramal Pharma Solutions, Patheon Pharma Services, Recipharm AB, Corden Pharma International, Boehringer Ingelheim International GmbH, Catalent Inc., and Aenova Group, each offering large-scale production capacity, advanced formulation services, and strong regulatory expertise. These companies focus on high-potency handling, controlled-release technologies, and cost-efficient manufacturing models to support global pharmaceutical outsourcing. Asia Pacific leads the market with 30% share, supported by cost advantages and expanding GMP-certified facilities. North America follows with 34% share, driven by strong generic drug demand and mature outsourcing networks, while Europe holds 28% share, reflecting its advanced manufacturing infrastructure and regulatory excellence.
Market Insights
- The Oral Solid Dosage Contract Manufacturing market reached USD 37,522 million in 2024 and will grow at a CAGR of 5.4% through 2032.
- Outsourcing rises as pharma companies seek cost-efficient production, with tablets dominating the product segment at 62% share due to high scalability and flexibility.
- Advanced formulation technologies, high-potency handling, and controlled-release capabilities shape key trends as CMOs invest in automation and continuous manufacturing.
- Competitive intensity grows as major players expand global footprints, strengthen regulatory compliance, and form partnerships to support complex OSD development and large-volume production.
- Asia Pacific leads with 30% share, North America follows with 34%, and Europe holds 28%, driven by strong generic drug demand, expanding manufacturing capacity, and rising adoption of outsourcing across both large and small pharmaceutical companies.
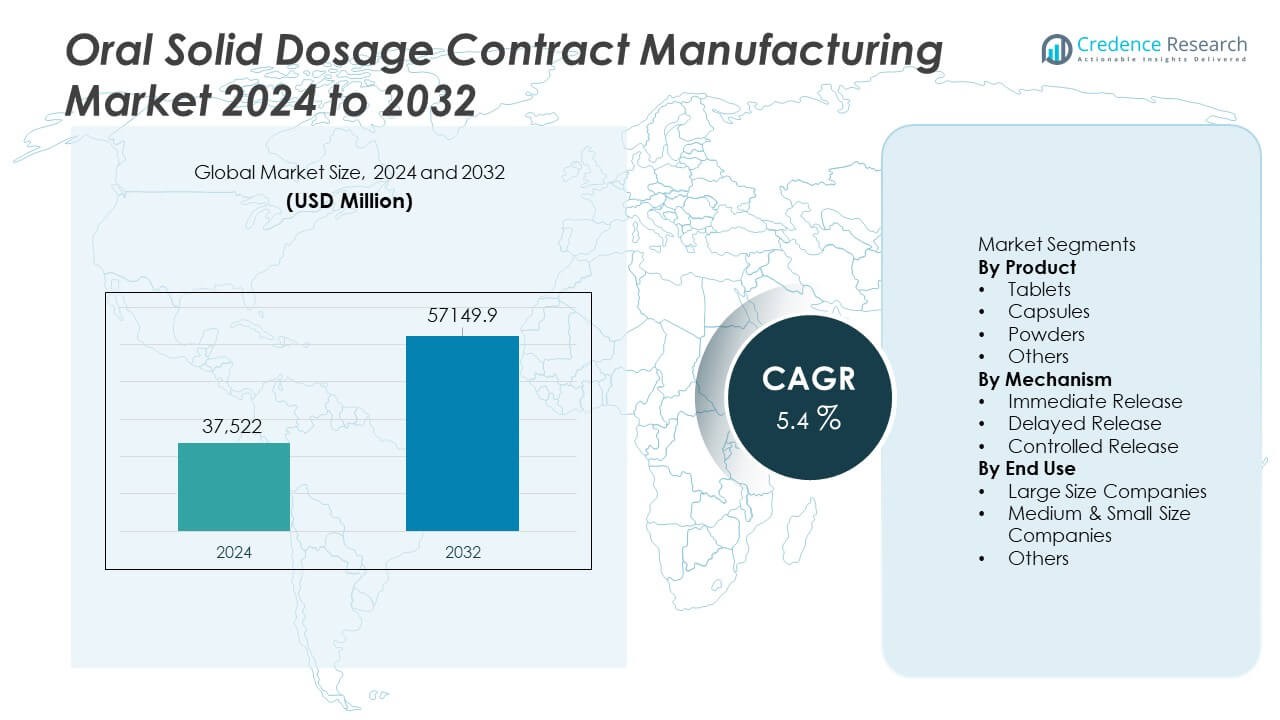 Market Segmentation Analysis:
By Product
Tablets dominate the product segment with 62% share, driven by their high stability, ease of manufacturing, and cost-effectiveness. Pharmaceutical companies continue to outsource tablet production due to rising demand for generic drugs, large-volume batch requirements, and improved formulation technologies such as film coating and taste-masking. Capsules gain momentum as they support complex formulations, including combination drugs and modified-release profiles. Powders and other oral formats serve niche therapeutic needs. Tablets maintain their leadership as contract manufacturers invest in high-capacity production lines, advanced compression systems, and flexible scalability to support global drug development pipelines.
- For instance, Catalent expanded its Winchester site with new rotary presses that raise output to 1.2 billion tablets per year. The upgrade includes a 300-liter high-shear granulator that supports complex blends.
By Mechanism
Immediate-release formulations lead this segment with 58% share, supported by their widespread use in chronic and acute therapies and faster regulatory approvals. These products offer rapid onset of action, making them preferred for pain management, cardiovascular drugs, and antibiotics. Delayed-release products grow as demand rises for acid-resistant coatings and targeted gastrointestinal delivery. Controlled-release formulations expand steadily due to increased development of long-acting therapies that enhance patient adherence. Immediate-release dominance continues as contract manufacturers optimize granulation, coating, and dissolution technologies to support high-volume, fast-turnaround production for global markets.
- For instance, Recipharm has fluid-bed processors that handle a range of granulation volumes for immediate-release drugs. The company also utilizes dissolution testing units capable of running automated samples each cycle.
By End Use
Large-size companies hold the leading 49% share, driven by extensive outsourcing strategies aimed at reducing manufacturing costs, improving supply chain resilience, and expanding production capacity for high-demand therapies. These companies rely on CMOs for technology-intensive operations such as high-shear granulation, high-potency handling, and advanced coating processes. Medium and small pharmaceutical firms grow rapidly as they outsource to access specialized expertise and avoid capital-intensive facility investments. Other end users contribute steady demand through niche formulations and regional supply needs. Large companies maintain dominance as they increasingly adopt flexible outsourcing models to accelerate product development and global distribution.
Key Growth Drivers
Rising Demand for Generic and Affordable Medications
Growing global demand for cost-effective generic drugs drives strong reliance on oral solid dosage contract manufacturing. As major patents expire and healthcare systems prioritize affordability, pharmaceutical companies increasingly outsource production to reduce operational costs and expand capacity. Contract manufacturers offer high-volume capabilities, advanced formulation expertise, and regulatory-compliant facilities that support rapid scale-up. This shift enables drug developers to focus on R&D and commercialization while leveraging CMO efficiencies. The rising burden of chronic diseases and expanding access to essential medicines further accelerates outsourcing growth.
- For instance, Piramal Pharma Solutions expanded its Pithampur site to support annual output of oral solid units and added a fluid-bed processor for large-scale granulation.
Increasing Outsourcing by Large Pharmaceutical Companies
Large pharmaceutical companies expand outsourcing to improve flexibility, reduce manufacturing burdens, and strengthen supply-chain resilience. Oral solid dosage forms such as tablets and capsules require high-capacity equipment, stringent quality control, and specialized handling, which CMOs provide at lower capital cost. Outsourcing enables faster global distribution and better alignment with fluctuating market demand. As innovation pipelines widen, companies rely on CMOs for formulation development, scale-up, and compliance management. This trend accelerates as firms adopt lean manufacturing models and prioritize efficiency in competitive therapeutic markets.
- For instance, Lonza expanded its Bend facility with new capabilities for clinical bottling and labeling, solid form services, and advanced particle engineering technologies like spray-drying and hot-melt extrusion for oral solid and inhaled applications.
Advancements in Formulation and Manufacturing Technologies
Technological progress supports the development of complex OSD formulations, including controlled-release, taste-masked, and high-potency products. CMOs invest in automated systems, continuous manufacturing, and advanced granulation and coating technologies to improve product consistency and reduce production time. These advancements attract pharmaceutical companies seeking reliable partners capable of producing high-quality, innovative oral dosage forms. Improved process analytics and quality-by-design approaches enhance regulatory compliance and reduce batch variability. As demand grows for specialized formulations, technology-driven CMOs gain significant competitive advantage.
Key Trends & Opportunities
Growth of High-Potency and Modified-Release Formulations
Demand increases for high-potency APIs and modified-release oral dosage forms that improve treatment outcomes and patient adherence. CMOs expand containment capabilities, precision dosing technologies, and coating expertise to support complex formulations. These capabilities create strong opportunities in oncology, hormonal therapies, and chronic disease management. Pharmaceutical companies increasingly partner with CMOs that provide specialized facilities and regulatory expertise. As the market shifts toward differentiated products, modified-release and high-potency solutions become a major growth avenue.
- For instance, Thermo Fisher Scientific (PPD) expanded its high-potency capability with contained isolators and added a large high-shear granulator for potent solid dose blends.
Expansion of Global Supply Networks and Regional Manufacturing Hubs
Pharmaceutical firms diversify production networks to reduce supply disruptions and meet regional regulatory requirements. Emerging markets in Asia and Eastern Europe become attractive hubs due to lower costs, skilled labor, and improving GMP-compliant infrastructure. CMOs expand global footprints to support local production, faster delivery, and compliance with country-specific standards. This trend opens opportunities for cross-border partnerships and capacity expansion. As global demand rises, regional manufacturing hubs strengthen resilience and enhance competitiveness.
- For instance, Recipharm expanded its India site with extensive tablet and capsule lines capable of producing significant volumes of solid dosage forms annually for global and regional programs.
Key Challenges
Strict Regulatory Compliance and Quality Requirements
The OSD contract manufacturing sector faces stringent regulatory expectations from agencies such as the FDA and EMA. CMOs must maintain rigorous quality systems, data integrity, and documentation practices to meet audit standards. Continuous regulatory updates increase compliance complexity, especially for companies operating across multiple regions. Failure to meet standards can delay product launches or result in penalties. Maintaining consistent quality while scaling production remains a significant operational challenge for many manufacturers.
High Capital Investment and Competitive Pricing Pressure
OSD manufacturing requires substantial investment in advanced equipment, containment systems, skilled labor, and facility upgrades. These costs create barriers for smaller CMOs and increase competition among established players. Pricing pressure intensifies as pharmaceutical companies seek cost-efficient outsourcing partners while demanding high quality and rapid turnaround. Maintaining profitability becomes challenging as firms balance operational expenses with competitive bids. CMOs must innovate, automate, and optimize processes to remain sustainable in a cost-sensitive market.
Regional Analysis
North America
North America holds 34% share of the Oral Solid Dosage Contract Manufacturing market, supported by strong outsourcing trends among large pharmaceutical companies and rising production of generics. The region benefits from advanced GMP-compliant facilities, strong regulatory oversight, and high investment in formulation development. Demand grows as companies shift to cost-efficient manufacturing models and expand biologics-to-OSD conversion strategies. Chronic disease prevalence and large-scale drug consumption further boost production needs. Collaborations between CMOs and branded drug manufacturers enhance innovation, while expansions in high-potency and modified-release capabilities strengthen the region’s leadership.
Europe
Europe accounts for 28% share, driven by strong pharmaceutical manufacturing infrastructure and high adoption of contract services among companies seeking regulatory excellence and technological expertise. The region’s focus on high-quality standards encourages outsourcing of tablets, capsules, and complex modified-release formulations. Increased demand for generics and rising emphasis on sustainability support market expansion. Western Europe leads with advanced capacity for high-potency OSD production, while Eastern Europe grows as a cost-competitive outsourcing hub. Ongoing modernization of facilities and strong R&D pipelines reinforce Europe’s position in the global OSD contract manufacturing landscape.
Asia Pacific
Asia Pacific holds 30% share, emerging as the fastest-growing region due to cost advantages, expanding GMP-certified facilities, and increased investment from global pharmaceutical companies. India and China lead in large-scale generic manufacturing and high-volume OSD production. Rising healthcare demand, supportive government policies, and growing clinical trial activity drive regional growth. CMOs in the region strengthen capabilities in controlled-release technologies, high-potency handling, and continuous manufacturing. The combination of competitive pricing and expanding technical expertise positions Asia Pacific as a key global outsourcing destination.
Latin America
Latin America accounts for 5% share, supported by growing pharmaceutical production in Brazil and Mexico and increasing demand for cost-effective outsourcing solutions. Regional CMOs expand capabilities in tablet and capsule manufacturing to serve both domestic and export markets. Market growth benefits from rising consumption of generics and strengthened regulatory harmonization across countries. However, economic fluctuations and variable regulatory environments limit rapid expansion. Despite challenges, investments in facility upgrades and partnerships with multinational drug companies drive steady growth in OSD contract manufacturing.
Middle East & Africa
Middle East & Africa hold 3% share, driven by expanding pharmaceutical manufacturing capacity in Gulf countries and rising demand for affordable oral solid dosage forms. Governments invest in local production to reduce import dependency, creating opportunities for regional CMOs. Growth remains moderate due to limited advanced manufacturing infrastructure in several African nations, but investments in technology and training continue to improve capabilities. Increasing demand for chronic disease medications and essential generics supports long-term growth prospects.
Market Segmentations:
By Product
- Tablets
- Capsules
- Powders
- Others
By Mechanism
- Immediate Release
- Delayed Release
- Controlled Release
By End Use
- Large Size Companies
- Medium & Small Size Companies
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Oral Solid Dosage Contract Manufacturing market is shaped by key players such as Jubilant Pharmova Limited, Lonza, Siegfried Holding AG, Piramal Pharma Solutions, Patheon Pharma Services, Recipharm AB, Corden Pharma International, Boehringer Ingelheim International GmbH, Catalent Inc., and Aenova Group. These companies focus on large-scale production capacity, advanced formulation technologies, and strong regulatory compliance to support global pharmaceutical outsourcing needs. Competitive strategies emphasize expansion of high-potency API handling, controlled-release capabilities, and continuous manufacturing platforms. Many players invest in automation, quality-by-design processes, and digital monitoring systems to enhance efficiency and reduce production variability. Strategic partnerships with pharmaceutical companies strengthen development pipelines and accelerate commercialization. As demand rises for generics, specialty formulations, and flexible manufacturing models, leading CMOs intensify efforts to offer scalable, cost-effective solutions. Firms with diversified service portfolios and global manufacturing footprints continue to maintain a strong competitive advantage.
Key Player Analysis
- Jubilant Pharmova Limited
- Lonza
- Siegfried Holding AG
- Piramal Pharma Solutions
- Patheon Pharma Services
- Recipharm AB
- Corden Pharma International
- Boehringer Ingelheim International GmbH
- Catalent Inc.
- Aenova Group
Recent Developments
- In October 2024, Catalent, Inc. agreed to sell its oral solids development and small-scale manufacturing facility in Somerset, New Jersey to Ardena.
- In July 2023, Aenova formed a partnership with Galvita to support formulation, development and production of oral dosage products.
- In January 2023, Catalent partnered with Ethicann to develop Ethicann’s clinical drug pipeline using Catalent’s ODT (orally disintegrating tablet) technology.
Report Coverage
The research report offers an in-depth analysis based on Product, Mechanism, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for OSD outsourcing will rise as pharmaceutical companies focus on cost efficiency and scalability.
- Tablets and capsules will remain dominant due to high stability, ease of production, and strong patient preference.
- High-potency API handling capabilities will expand as oncology and specialty drugs grow.
- Continuous manufacturing technologies will gain wider adoption for faster and more consistent production.
- Modified-release and complex formulations will increase as companies seek differentiation and improved patient adherence.
- Digitalization and automation will enhance quality control and reduce batch variability.
- Regional manufacturing hubs will strengthen supply-chain resilience and support localized production.
- Partnerships between CMOs and pharma companies will increase to accelerate development timelines.
- Regulatory expectations will push manufacturers to elevate GMP compliance and data integrity.
- Expansion of generic drug portfolios worldwide will continue to drive long-term outsourcing growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Oral Solid Dosage Contract Manufacturing market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Oral Solid Dosage Contract Manufacturing market projected to grow between 2025 and 2032?
Which Oral Solid Dosage Contract Manufacturing market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Oral Solid Dosage Contract Manufacturing market?
Who are the leading companies in the Oral Solid Dosage Contract Manufacturing market?
Which region commanded the largest share of the Oral Solid Dosage Contract Manufacturing market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Oral Solid Dosage Contract Manufacturing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Oral Solid Dosage Contract Manufacturing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 37,522 million → 2032: USD 57,149.9 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Oral Solid Dosage Contract Manufacturing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Oral Solid Dosage Contract Manufacturing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Oral Solid Dosage Contract Manufacturing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Oral Solid Dosage Contract Manufacturing Market Drivers
- 3.3 Oral Solid Dosage Contract Manufacturing Market Restraints & Challenges
- 3.4 Oral Solid Dosage Contract Manufacturing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Oral Solid Dosage Contract Manufacturing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Oral Solid Dosage Contract Manufacturing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Oral Solid Dosage Contract Manufacturing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Oral Solid Dosage Contract Manufacturing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Oral Solid Dosage Contract Manufacturing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Oral Solid Dosage Contract Manufacturing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Oral Solid Dosage Contract Manufacturing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Oral Solid Dosage Contract Manufacturing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Oral Solid Dosage Contract Manufacturing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Oral Solid Dosage Contract Manufacturing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Oral Solid Dosage Contract Manufacturing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Oral Solid Dosage Contract Manufacturing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Oral Solid Dosage Contract Manufacturing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Oral Solid Dosage Contract Manufacturing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Oral Solid Dosage Contract Manufacturing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Oral Solid Dosage Contract Manufacturing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Oral Solid Dosage Contract Manufacturing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Oral Solid Dosage Contract Manufacturing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Oral Solid Dosage Contract Manufacturing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
