
Market Overview
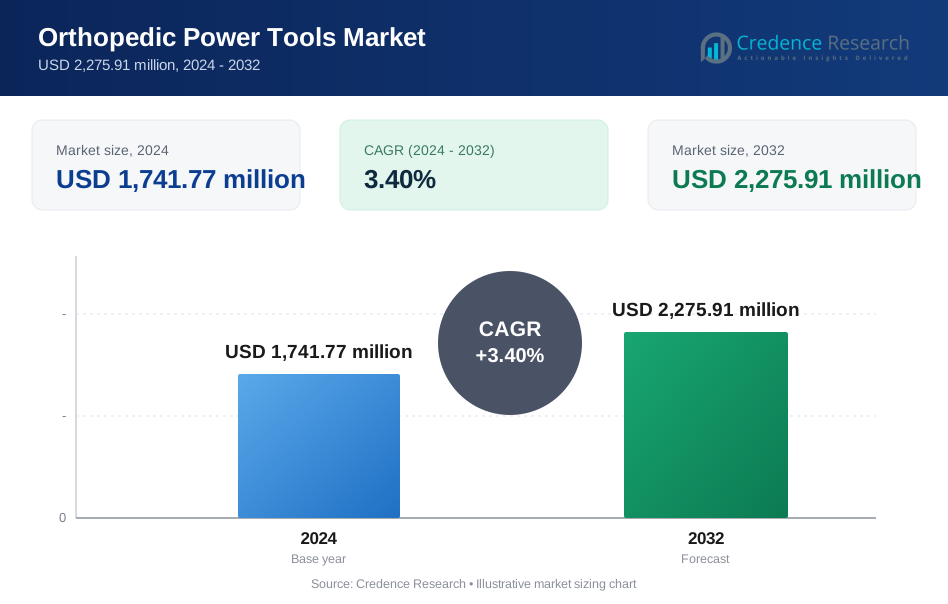
The Orthopedic Power Tools Market is projected to grow from USD 1,741.77 million in 2024 to USD 2,275.91 million by 2032, at a compound annual growth rate (CAGR) of 3.40%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2025 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Orthopedic Power Tools Market Size 2024 | USD 1,741.77 Million |
| Orthopedic Power Tools Market, CAGR | 3.40% |
| Orthopedic Power Tools Market Size 2032 | USD 2,275.91 Million |
The Orthopedic Power Tools Market is driven by advancements in surgical technology, increasing demand for minimally invasive procedures, and the rising prevalence of orthopedic conditions due to an aging population. Innovations such as smart tools and enhanced precision in surgeries are propelling market growth. Additionally, the expansion of healthcare facilities and the growing focus on improving surgical outcomes further support market expansion. Trends like the integration of robotics and automation in orthopedic surgeries are also shaping the market, leading to increased efficiency and precision in surgical procedures.
The orthopedic power tools market is characterized by a diverse range of key players operating across different regions. Major companies include Stryker and Conmed Corporation in the U.S., Zimmer Biomet and Johnson & Johnson Services, Inc., and Medtronic in Ireland. Notable European players are B. Braun Melsungen AG in Germany and De Soutter Medical in the U.K. Key Asian companies include AlloTech Co. LTD in South Korea and NSK/NAKANISHI in Japan. These global players leverage their regional strengths to innovate and compete in the orthopedic power tools market, driving advancements and market growth across various geographical areas.
Market Drivers
Rising Prevalence of Orthopedic Conditions
Saudi Arabia’s rising orthopedic case load is being driven by an aging population and a steady flow of trauma and injury cases, both of which increase demand for efficient orthopedic operating-room equipment, including power tools used in fixation, joint reconstruction, and spine procedures. Older adults face higher risk of degenerative joint disease, fragility fractures, and mobility-limiting conditions that often require surgical intervention and implant-based repair. For instance, according to the General Authority for Statistics Elderly Statistics Publication 2025, the population aged 60 years and over reached about 1.7 million people, representing 4.8% of the total population. Road trauma adds to surgical volumes and keeps fracture and emergency orthopedic workstreams active. According to GASTAT Road Transport Statistics 2024, the number of serious traffic accidents exceeded 17.2 thousand accidents..
Advancements in Surgical Techniques
Saudi providers are increasingly adopting minimally invasive, navigation-assisted, and robot-enabled techniques that raise the need for power tools designed for precision, speed, and tighter tolerances in complex procedures. These approaches typically rely on smaller working corridors and more exact bone preparation, which puts a premium on low-vibration, high-control systems and compatible instrumentation. For instance, according to King Faisal Specialist Hospital and Research Centre, it performed 1,370 robotic surgeries in 2024, a 28% increase from the previous year, indicating rapid scale-up of advanced surgery that drives demand for modern, procedure-ready tool ecosystems. Public-sector systems are also building orthopedics-specific robotic capacity for joint replacement and spine workflows. According to the Ministry of National Guard Health Affairs, its Robotic and Navigation Surgery Unit aims to perform robot-assisted surgeries in joint replacement and spine surgeries to support high accuracy in complex orthopedic operations.
Technological Innovations
Technology upgrades in Saudi operating rooms are pushing orthopedic power tools toward better ergonomics, stronger materials, improved battery systems, and tighter integration with navigation and robotics platforms. As hospitals and private groups compete on outcomes and throughput, tool performance, durability, and service support become more important to reduce downtime and standardize surgical quality. For instance, according to Almoosa Specialist Hospital, it achieved a milestone of 300 successful robotic knee replacement surgeries, which reflects growing adoption of technology-intensive orthopedic procedures that require compatible instrumentation and high-performing surgical systems. Private hospitals are also expanding robotic programs across specialties, which helps normalize advanced instrumentation requirements across broader provider networks. According to Mouwasat Hospital, it has performed over 250 robotic-assisted surgeries across multiple specialties since establishing its robotic surgery center.
Focus on Patient Outcomes
Hospitals and surgeons prioritize tools that reduce operating time, improve surgical accuracy, and support faster rehabilitation because these factors can translate into shorter length of stay and fewer complications in orthopedic pathways. Faster, cleaner cuts and more reliable fixation can lower variability and improve alignment and fit, which are central to joint and trauma outcomes. For instance, according to King Faisal Specialist Hospital and Research Centre, robotic procedures have reduced hospital stays by more than 50%, showing how precision-led approaches can improve efficiency and recovery, a benefit hospitals seek to replicate across technology-enabled surgical lines that include orthopedics. As these expectations rise, demand grows for power tools that can consistently deliver high precision under heavy procedural loads and in a wider range of complex cases.
Market Trends
Advancements in Technology
Technological advancements are driving significant trends in the orthopedic power tools market. For instance, the use of minimally invasive surgery (MIS) tools has led to a reduction in patient recovery time by 25%, with these tools being 50% more precise than traditional surgical instruments. Additionally, the integration of robotics has resulted in a 20% increase in surgical accuracy, and smart technology tools have provided real-time feedback in 80% of orthopedic surgeries, enhancing surgical outcomes.
A notable trend is the focus on minimally invasive surgery (MIS), which requires power tools designed for precision and maneuverability in smaller spaces. These tools are engineered to enhance surgical outcomes by minimizing tissue damage and facilitating quicker recovery. Additionally, the integration of robotics and automation into orthopedic procedures is shaping the market by necessitating advanced, compatible power tools that support automated and highly precise surgical techniques.
The incorporation of smart technology, including data tracking and real-time feedback, is further revolutionizing the field, providing surgeons with enhanced capabilities and information during procedures. These innovations collectively push the boundaries of what orthopedic power tools can achieve, catering to the evolving needs of modern surgical practices.
Emphasis on Patient Outcomes
The focus on improving patient outcomes is a driving force behind the latest trends in orthopedic power tools. For instance, ergonomic designs in orthopedic power tools have reduced surgeon fatigue by 30%, leading to a 15% improvement in surgical efficiency. Tools that offer exceptional precision have contributed to a 10% decrease in surgical complications, promoting faster recovery times and improving patient results.
There is an increasing demand for tools that offer exceptional precision and accuracy, aimed at minimizing surgical complications and promoting faster recovery times. Surgeons are seeking power tools that enable them to perform procedures with greater exactness, reducing the risk of errors and improving patient results. Additionally, ergonomic designs are becoming a priority, as tools that reduce surgeon fatigue can enhance surgical efficiency and overall performance.
This emphasis on ergonomics not only benefits surgeons but also contributes to better patient care by ensuring that surgeries are conducted with greater comfort and effectiveness.
Market Challenges Analysis
Stringent Regulatory Environment
The orthopedic power tools market faces significant challenges due to a stringent regulatory environment. Obtaining regulatory approvals for new tools involves complex, time-consuming, and costly processes. Manufacturers must navigate extensive documentation and rigorous testing to meet the high standards set by regulatory bodies, which can delay product launches and increase operational expenses. Additionally, adhering to stringent quality, safety, and performance standards imposes substantial compliance burdens. These requirements necessitate continuous investment in quality assurance and regulatory compliance, further escalating costs and complicating market entry for new players.
High Research and Development Costs
High research and development (R&D) costs represent a major challenge for the orthopedic power tools industry. The rapid pace of technological advancements requires significant investments in R&D to develop innovative and effective power tools. This continuous need for innovation drives up expenses as companies strive to stay ahead in a highly competitive market. Intense competition among manufacturers further exacerbates R&D costs, as firms must consistently invest in new technologies and enhancements to maintain their competitive edge. These financial pressures can strain budgets and impact profitability, particularly for smaller companies or those entering the market with new solutions.
Market Segmentation Analysis:
By Product:
The orthopedic power tools market is segmented by product into small bone orthopedic power tools, large bone orthopedic power tools, and high-speed orthopedic power tools. Small bone orthopedic power tools are essential for precision surgeries involving smaller bones, such as those in the hand and foot. These tools are designed for accuracy and are increasingly used in minimally invasive procedures. Large bone orthopedic power tools, on the other hand, are utilized for surgeries involving larger bones like the femur and tibia, where greater power and durability are required. High-speed orthopedic power tools are characterized by their ability to operate at higher speeds, making them suitable for procedures that demand rapid and efficient performance. Each product segment caters to specific surgical needs, driving demand based on the complexity and scale of orthopedic surgeries.
By Modality:
In terms of modality, the orthopedic power tools market is divided into single-use and reusable orthopedic power tools. Single-use orthopedic power tools are designed for one-time use, offering convenience and reducing the risk of cross-contamination. These tools are increasingly favored in environments where sterilization between uses is critical, such as in outpatient or emergency settings. Reusable orthopedic power tools, however, are built for multiple uses, providing cost-effectiveness and long-term reliability. These tools require rigorous sterilization processes but offer durability and are more economical over time. The choice between single-use and reusable modalities is influenced by factors such as the type of procedure, healthcare setting, and cost considerations, impacting market dynamics and adoption rates.
Segments:
Based on Product:
- Small Bone Orthopedic Power Tools
- Large Bone Orthopedic Power Tools
- High-Speed Orthopedic Power Tools
Based on Modality:
- Single-Use Orthopedic Power Tools
- Reusable Orthopedic Power Tools
Based on Technology:
- Pneumatic-Powered Systems
- Electric-Powered Systems
- Battery-Powered Systems
Based on End-User:
- Hospitals
- Ambulatory Surgical Centers
- Orthopedic Clinics
Based on the Geography:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America emerging as the dominant player, commanding approximately 40% of the market share. This region's leadership is primarily driven by its advanced healthcare infrastructure, high adoption rates of cutting-edge medical technologies, and a large patient pool requiring orthopedic surgeries. The United States stands at the forefront of the North American market, benefiting from substantial healthcare expenditure, a growing elderly population, and a high incidence of sports-related injuries.
The region's market is characterized by a strong focus on technological advancements, with key players continuously introducing innovative, ergonomic, and high-precision power tools. Canada also contributes significantly to the market, with its universal healthcare system supporting the widespread adoption of advanced orthopedic tools. The North American market is further bolstered by the presence of major orthopedic device manufacturers, robust research and development activities, and increasing demand for minimally invasive surgical procedures.
Europe
Europe follows closely, holding a 30% market share. The European market is driven by well-established healthcare systems, increasing geriatric populations, and a rising incidence of osteoarthritis and osteoporosis. Countries like Germany, the UK, and France lead the European market, known for their stringent regulatory standards and focus on patient safety. The Asia-Pacific region is experiencing the fastest growth in the orthopedic power tools market, attributed to improving healthcare infrastructure, rising disposable incomes, and growing awareness about advanced surgical techniques in countries like China, Japan, and India.
Key Player Analysis
- Stryker
- Conmed Corporation
- Zimmer Biomet
- Medtronic
- AlloTech Co. LTD
- Kaiser Medical Technology
- NSK/NAKANISHI
- Johnson & Johnson Services, Inc.
- B. Braun Melsungen AG
- De Soutter Medical
Competitive Analysis
The orthopedic power tools market is highly competitive, with leading players such as Stryker, Zimmer Biomet, and Johnson & Johnson Services, Inc., dominating the landscape. Stryker, headquartered in Kalamazoo, U.S., excels in technological innovation and a broad product range, focusing on enhancing surgical precision and efficiency. Zimmer Biomet, based in Warsaw, U.S., is known for its comprehensive portfolio and strong emphasis on research and development. Johnson & Johnson Services, Inc. leverages its extensive resources to advance orthopedic technologies and expand market reach. In Europe, B. Braun Melsungen AG and De Soutter Medical are key competitors, with B. Braun focusing on integrated solutions and De Soutter Medical offering specialized tools.
Recent Developments
- In June 2025, Arthrex announced the launch of its Synergy Power™ powered instrument system, featuring a dual-trigger rotary drill and a sagittal saw designed for a wide range of orthopaedic procedures.
- In June 2025, Johnson & Johnson MedTech announced the launch of the KINCISE™ 2 Surgical Automated System, a next-generation automated orthopaedic power tool intended to improve surgical efficiency and reduce physical burden on surgeons across primary and revision hip and revision knee replacement procedures.
- In February 2024, Zimmer Biomet Holdings, Inc. announced that its ROSA ® Shoulder System has received FDA clearance for robotic-assisted shoulder replacement. The ROSA Shoulder is the first robotic shoulder replacement system in the world, and is part of the ROSA® Robotics portfolio that also includes the ROSA® Knee System and the ROSA® Hip System.
- In January 2024, Paragon 28, Inc. launched FJ2000 Power Console and Burr System. The system is designed for minimally invasive foot and ankle surgical procedures.
- In January 2024,Arthrex launched a new online platform, NanoExperience.com, to educate people about Nano arthroscopy, a minimally invasive orthopaedic procedure.
Market Concentration & Characteristics
The orthopedic power tools market exhibits moderate to high concentration, dominated by a few major players who significantly influence market trends and dynamics. Leading companies such as Stryker, Zimmer Biomet, and Johnson & Johnson Services, Inc. hold substantial market shares due to their extensive product portfolios, technological advancements, and global presence. This concentration results in a competitive environment where innovation and quality are critical for market leadership. The market is characterized by high entry barriers, including stringent regulatory requirements and substantial R&D investments. Additionally, companies are increasingly focusing on strategic mergers, acquisitions, and partnerships to enhance their market position and expand their offerings. These dynamics contribute to a concentrated market structure where established players continuously innovate to maintain their competitive edge and address evolving customer needs.
Report Coverage
The research report offers an in-depth analysis based on Product, Modality, Technology, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The orthopedic power tools market is expected to grow steadily due to increasing orthopedic procedures and an aging population.
- Technological advancements, including robotics and smart tools, will drive innovation and enhance surgical precision.
- There will be a growing demand for minimally invasive surgical tools, which offer reduced recovery times and improved patient outcomes.
- The integration of digital technologies and data analytics in orthopedic tools will become more prevalent, improving surgical planning and execution.
- Emerging markets, particularly in Asia and Latin America, will see increased adoption of advanced orthopedic power tools due to rising healthcare expenditures.
- The trend toward outpatient and ambulatory surgical centers will drive the need for efficient and compact power tools.
- Sustainability concerns will prompt manufacturers to develop eco-friendly materials and practices for orthopedic tools.
- Strategic partnerships and mergers among leading players will intensify, enhancing product offerings and market reach.
- Regulatory challenges will persist, requiring companies to navigate complex approval processes and compliance standards.
- Rising competition will push companies to continually innovate and invest in research and development to maintain a competitive edge.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Advancements in Surgical Technology
Continuous innovation in orthopedic power tools, such as the integration of robotics, smart tools, and navigation systems, is enabling more precise and efficient surgeries, thereby increasing adoption among healthcare providers.
Increasing Demand for Minimally Invasive Procedures
The shift toward minimally invasive orthopedic surgeries requires specialized power tools that offer high precision and maneuverability, driving demand for advanced tool systems that support these techniques.
Rising Prevalence of Orthopedic Conditions
An aging global population and higher rates of trauma and degenerative joint diseases are leading to more orthopedic procedures, boosting the need for reliable and high-performing power tools in surgical settings.
Expansion of Healthcare Infrastructure
Growth in hospital networks, ambulatory surgical centers, and orthopedic clinics - especially in emerging markets - is increasing the installed base and replacement demand for orthopedic power tools.
Focus on Patient Outcomes and Surgical Efficiency
Healthcare providers are prioritizing tools that reduce operating time, improve surgical accuracy, and support faster patient recovery, which is driving the adoption of next-generation orthopedic power tools designed for optimal outcomes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Orthopedic Power Tools Market?
What factors are driving the growth of the Orthopedic Power Tools Market?
What are the key segments within the Orthopedic Power Tools Market?
What are some challenges faced by the Orthopedic Power Tools Market?
Who are the major players in the Orthopedic Power Tools Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Small Bone Orthopedic Power Tools
- 1.2.2 Large Bone Orthopedic Power Tools
- 1.2.3 High-Speed Orthopedic Power Tools
- 1.3 By End-User
- 1.3.1 Hospitals
- 1.3.2 Ambulatory Surgical Centers
- 1.3.3 Orthopedic Clinics
- 1.4 By Modality
- 1.4.1 Single-Use Orthopedic Power Tools
- 1.4.2 Reusable Orthopedic Power Tools
- 1.5 By Technology
- 1.5.1 Pneumatic-Powered Systems
- 1.5.2 Electric-Powered Systems
- 1.5.3 Battery-Powered Systems
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,741.77 million → 2032: USD 2,275.91 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Orthopedic Power Tools Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Orthopedic Power Tools Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Orthopedic Power Tools Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Orthopedic Power Tools Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Orthopedic Power Tools Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Orthopedic Power Tools Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Orthopedic Power Tools Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Orthopedic Power Tools Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,741.77 million → 2032: USD 2,275.91 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Orthopedic Power Tools Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Small Bone Orthopedic Power Tools
- 12.3.7.2 Large Bone Orthopedic Power Tools
- 12.3.7.3 High-Speed Orthopedic Power Tools
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Ambulatory Surgical Centers
- 12.4.7.3 Orthopedic Clinics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Modality - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Single-Use Orthopedic Power Tools
- 12.5.7.2 Reusable Orthopedic Power Tools
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Technology - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Pneumatic-Powered Systems
- 12.6.7.2 Electric-Powered Systems
- 12.6.7.3 Battery-Powered Systems
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Orthopedic Power Tools End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Orthopedic Power Tools Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Orthopedic Power Tools Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Orthopedic Power Tools Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Stryker
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Zimmer Biomet
- 18.4 Johnson & Johnson Services, Inc.
- 18.5 Medtronic
- 18.6 Conmed Corporation
- 18.7 B. Braun Melsungen AG
- 18.8 De Soutter Medical
- 18.9 AlloTech Co. LTD
- 18.10 NSK/NAKANISHI
- 18.11 Kaiser Medical Technology
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

