
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Osseointegration Implants Market Size 2024 | USD 7275 Million |
| Osseointegration Implants Market, CAGR | 8.1% |
| Osseointegration Implants Market Size 2032 | USD 13565.5 Million |
Market Overview:
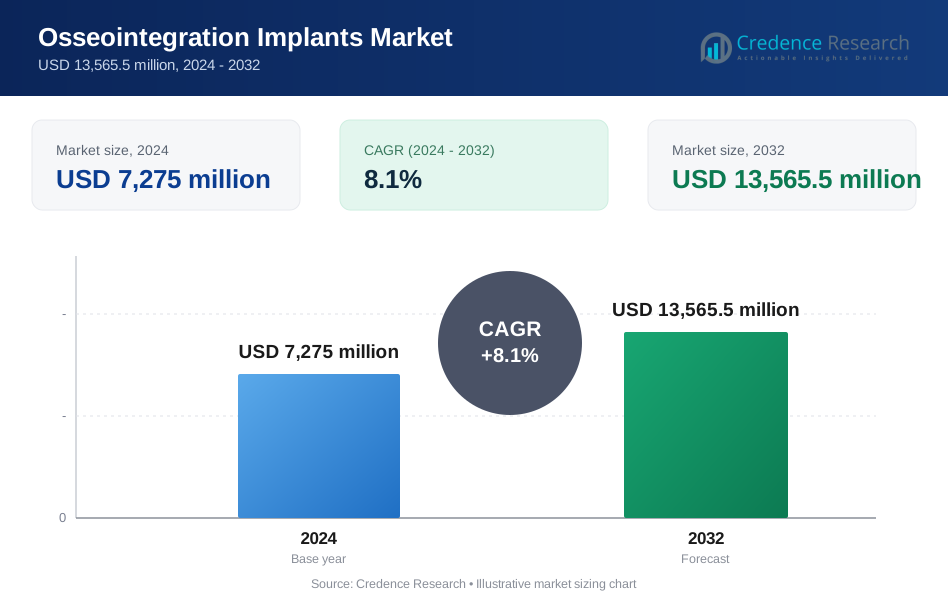
The Osseointegration Implants Market is projected to grow from USD 7275 million in 2024 to an estimated USD 13565.5 million by 2032, with a compound annual growth rate (CAGR) of 8.1% from 2024 to 2032.
The primary drivers fueling the osseointegration implants market include a growing global elderly population susceptible to bone-related ailments, such as osteoporosis, and conditions that necessitate dental and orthopedic procedures. Increased awareness about the benefits of osseointegration, such as improved functionality and reduced recovery time, is also contributing to market growth. Additionally, technological advancements in implant design and materials, including titanium-based and zirconia implants, are enhancing integration success rates and patient outcomes. The expanding healthcare infrastructure, coupled with increasing investment in research and development activities focused on bioengineering and advanced implant technology, further boosts market growth. Rising prevalence of trauma cases and orthopedic conditions, often resulting from lifestyle changes and an increase in accidents, further support the adoption of osseointegration implants.
The osseointegration implants market demonstrates a diverse regional distribution, with North America currently dominating due to factors such as advanced healthcare systems, high expenditure on medical technologies, and a growing prevalence of dental and orthopedic disorders. Europe follows closely, with a strong emphasis on innovation and the presence of major market players focusing on research initiatives. The Asia-Pacific region is projected to exhibit the fastest growth rate, driven by an increasing geriatric population, rising healthcare investments, and growing awareness about implant procedures. Countries like China, India, and Japan are key contributors to regional market growth due to the combination of a large patient base, improving healthcare access, and favorable government initiatives to support healthcare advancements.
Market Drivers:
Aging Population and Increasing Prevalence of Chronic Diseases:
The global rise in the elderly population is one of the key drivers fueling the osseointegration implants market. As individuals age, they are more likely to experience bone-related disorders, such as osteoporosis and arthritis, and may require orthopedic or dental implants due to tooth loss or degenerative bone conditions. The growing need for implants among older adults highlights the increasing demand for osseointegration technology, which offers improved integration of implants with bone tissue, leading to enhanced stability and better patient outcomes. For instance, the World Health Organization (WHO) reports that by 2030, 1 in 6 people in the world will be aged 60 years or over. The expanding pool of elderly patients worldwide creates a significant opportunity for market growth, as healthcare providers continue to focus on delivering advanced, long-lasting implant solutions.
Technological Advancements and Innovation:
Continuous technological advancements in implant design, materials, and surgical techniques are driving growth in the osseointegration implants market. Innovations such as titanium and zirconia implants offer superior biocompatibility, corrosion resistance, and mechanical strength, leading to more successful osseointegration. Additionally, developments in 3D printing and computer-aided design and manufacturing (CAD/CAM) have enabled customized implants tailored to individual patient anatomy, further enhancing treatment precision and outcomes. For example, 3D printing technology allows for the creation of patient-specific implants, improving the fit and integration with bone tissue. This focus on innovation has led to higher adoption rates of implants, as healthcare providers and patients recognize the benefits of improved functionality, reduced recovery times, and enhanced long-term results.
Rising Adoption of Minimally Invasive Surgeries:
The increasing demand for minimally invasive surgical procedures is another major driver of the osseointegration implants market. These procedures typically involve smaller incisions, reduced blood loss, shorter hospital stays, and faster recovery times compared to traditional surgical techniques. Osseointegration implants, designed for use in minimally invasive surgeries, provide a secure and stable connection between the implant and the bone, leading to better patient experiences and fewer post-operative complications. As patients and healthcare providers prioritize less invasive treatment options that offer improved clinical outcomes, the demand for advanced osseointegration implants continues to rise, further boosting market growth.
Government Support and Healthcare Infrastructure Expansion:
Government initiatives and investments aimed at strengthening healthcare infrastructure and increasing accessibility to advanced medical treatments are playing a crucial role in driving the osseointegration implants market. In many regions, governments are offering incentives and funding for research and development activities in the field of bioengineering and implant technology. This support encourages the development of cutting-edge implants and enables wider patient access to these life-enhancing devices. Moreover, the growth of healthcare infrastructure, particularly in emerging economies, has improved the availability of specialized surgical procedures and advanced implant solutions, further promoting market expansion. The combination of favorable policy support and healthcare advancements underscores the potential for sustained market growth in the coming years.
Market Trends:
Increasing Focus on Customization and Personalized Implants:
A notable trend in the osseointegration implants market is the growing emphasis on customization and personalized implants. Advances in 3D printing and computer-aided design (CAD) technology have allowed for the development of highly personalized implant solutions tailored to the specific anatomy of individual patients. For instance, Incredible 3D, an Indian metal additive manufacturing service provider, has successfully 3D printed over 3,000 patient-specific implants as of April 2024. Customized implants offer numerous benefits, including improved fit, enhanced stability, and more effective integration with bone tissue. This trend is driven by the rising demand for precision medicine, where treatment strategies are tailored to the unique characteristics of each patient. The adoption of personalized osseointegration implants is expected to accelerate as more healthcare providers recognize their potential to deliver better outcomes and patient satisfaction.
Increasing Use of Advanced Materials:
The use of advanced materials in osseointegration implants is another key trend shaping the market. Materials such as titanium alloys, ceramics, and zirconia have been increasingly adopted due to their superior biocompatibility, corrosion resistance, and ability to promote osseointegration. The development of bioactive coatings and surface modifications, such as nanostructured surfaces, further enhances the integration process by stimulating bone growth and reducing implant rejection rates. As material science continues to evolve, manufacturers are focusing on creating implants that offer greater longevity and reduced risk of complications. This trend is expected to drive the demand for more durable, high-performance implants in the coming years.
Growing Demand for Dental Implants:
The increasing demand for dental implants is significantly impacting the osseointegration implants market. Factors such as a rise in edentulism (tooth loss), advancements in dental technology, and a growing emphasis on aesthetic dentistry have contributed to this trend. Patients are seeking solutions that provide both functional and cosmetic benefits, making osseointegration-based dental implants a popular choice. Dental implants offer superior stability, improved oral function, and a natural appearance, making them preferable to traditional dentures. This surge in demand for dental implants is encouraging manufacturers to focus on developing innovative products and expanding their portfolios to cater to diverse patient needs.
Adoption of Robotic and Navigational Systems in Surgeries:
The adoption of robotic and navigational systems in surgical procedures is transforming the osseointegration implants market. These advanced systems enable greater precision during implant placement, reducing the risk of complications and enhancing surgical outcomes. Robotic-assisted surgeries allow for improved accuracy and consistency, particularly in complex procedures such as orthopedic and spinal implant placements. For instance, Restor3d has strategically expanded into robotics and navigation for surgical delivery of patient-specific implants. As healthcare providers increasingly adopt robotic and navigational technologies to enhance patient safety and procedural efficacy, the demand for osseointegration implants that are compatible with these systems continues to rise. This trend underscores the market's focus on integrating cutting-edge technologies into surgical practices to drive better outcomes for patients.
Market Restraints and Challenges:
High Costs of Osseointegration Procedures:
One of the primary restraints of the osseointegration implants market is the high cost associated with these procedures. The expense of osseointegration implants, coupled with the costs of surgical intervention, hospital stays, and post-operative care, can pose a financial burden for patients. While insurance coverage is available in some regions, it often varies significantly, limiting access for many individuals. The high initial investment and ongoing costs associated with implant procedures may deter potential patients and impede market growth, particularly in regions with limited healthcare reimbursement options.
Risk of Complications and Long Recovery Times:
Although osseointegration implants offer numerous benefits, the risk of complications such as infections, implant rejection, and issues related to integration failure remains a challenge. Successful osseointegration depends on several factors, including patient health, implant material, and surgical precision. Additionally, osseointegration often requires extended recovery periods, which can affect patient satisfaction and willingness to undergo the procedure. Addressing these risks and reducing recovery times is essential for broader market adoption.
Regulatory and Approval Challenges:
The osseointegration implants market faces stringent regulatory requirements that can delay product approvals and commercialization. Regulatory bodies often impose strict guidelines to ensure patient safety and efficacy, necessitating extensive clinical trials and testing. These lengthy and costly regulatory processes can hinder the market entry of innovative products and pose challenges for manufacturers, particularly small and medium-sized enterprises (SMEs) with limited resources. Navigating complex regulatory pathways while maintaining compliance remains a critical challenge for market participants, impacting product innovation and market expansion.
Market Segmentation Analysis:
The osseointegration implants market can be broadly segmented by product, material, and end-users, each of which plays a critical role in defining the market's growth dynamics.
By product, the market encompasses dental implants, crowns, abutments (including definitive and temporary), hip implants, knee implants, and spinal implants. Dental implants and abutments represent a significant share due to rising demand for tooth replacement solutions and aesthetic dentistry. Hip and knee implants are also witnessing substantial growth, driven by increasing orthopedic conditions among the aging population.
By material, the market is categorized into ceramic implants, zirconia implants, stainless steel implants, and titanium. Titanium is the most widely used material due to its excellent biocompatibility, high strength, and proven success in promoting osseointegration. Zirconia implants, known for their aesthetic appeal and hypoallergenic properties, are gaining traction in dental applications. Ceramic implants, with their high wear resistance, are also gaining attention in orthopedic and dental sectors.
By end-users includes hospitals, ambulatory surgical centers, and dental clinics. Hospitals account for a significant market share, attributed to the rising number of orthopedic and dental surgeries. Ambulatory surgical centers are witnessing growing adoption due to their cost-effectiveness and reduced patient recovery times. Dental clinics continue to be a crucial end-user segment, driven by the increasing demand for specialized dental procedures and implant-based restorations, further fueling market growth.
Segmentation:
By Product
- Dental Implants
- Crown
- Abutment
- Definitive abutment
- Temporary abutment
- Hip Implants
- Knee Implants
- Spinal Implants
By Material
- Ceramic Implants
- Zirconia Implants
- Stainless Steel Implants
- Titanium
By End Users
- Hospitals
- Ambulatory Surgical Centres
- Dental Clinics
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The osseointegration implants market exhibits a diverse geographical distribution, with North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa as the key regions. Each region demonstrates unique market dynamics, driven by healthcare infrastructure, demographic trends, and adoption rates of advanced medical technologies.
North America holds the largest market share, accounting for approximately X% of the global market. This dominance is driven by factors such as a well-established healthcare system, high healthcare expenditure, and widespread adoption of advanced medical technologies. The growing prevalence of dental and orthopedic conditions, coupled with rising awareness of minimally invasive procedures, continues to bolster market demand. The United States and Canada remain significant contributors, with a focus on innovation and robust investment in research and development further fueling market growth.
Europe is the second-largest market, with a share of around X%. The region's growth is supported by a strong emphasis on innovation, high prevalence of bone-related disorders, and the presence of key market players. Countries such as Germany, France, and the United Kingdom are leading markets, benefiting from favorable healthcare policies and increasing adoption of cutting-edge implants. Growing demand for aesthetic dental solutions and advancements in material technologies are further driving market expansion in this region.
The Asia-Pacific region is poised to exhibit the fastest growth over the forecast period, capturing a market share of approximately X%. Key factors driving this growth include a large and rapidly aging population, increasing healthcare expenditure, and rising awareness about implant-based treatments. Countries such as China, Japan, and India are at the forefront, with government initiatives aimed at improving healthcare infrastructure and access to advanced medical treatments. The increasing prevalence of lifestyle-related diseases and dental disorders further supports the market’s expansion in this region.
Latin America holds a moderate market share, driven by the gradual adoption of osseointegration implants and improving healthcare infrastructure. Brazil and Mexico are key markets, with rising demand for advanced orthopedic and dental procedures. However, challenges such as limited healthcare coverage and economic disparities may impact market growth.
The Middle East & Africa region accounts for a smaller share of the market but shows promising growth potential. Increasing healthcare investments, especially in countries like the UAE and Saudi Arabia, are enhancing access to specialized medical procedures. However, economic challenges and limited access to advanced technologies in certain parts of the region pose barriers to widespread adoption.
Key Player Analysis:
- Biocon
- Camlog
- CONMED Corporation
- Danaher
- Demant A/S
- Dentsply Sirona
- DePuy Synthes, Inc
- Henry Schein Inc
- Institut Straumann AG
- Integrum
- Medtronic, Inc.
- Nuvasive, Inc
- Osstem Implant
- Smith and Nephew PLC
- Southern Implants, Inc.
- Stryker
- Zimmer Biomet
Competitive Analysis:
The osseointegration implants market is characterized by intense competition, with a mix of established players and emerging companies vying for market share. Key players such as Zimmer Biomet, Danaher Corporation, Bicon, LLC, Dentsply Sirona, and Medtronic dominate the market through strong product portfolios, extensive distribution networks, and consistent innovation. These companies invest heavily in research and development to introduce advanced implant solutions with improved osseointegration properties and patient outcomes. Emerging companies focus on niche segments and technologically advanced, personalized implants to differentiate themselves and capture market share. Strategic partnerships, mergers and acquisitions, and product launches further intensify competition, enabling players to expand their global reach and strengthen their market position. The competitive landscape is marked by a strong emphasis on technological advancements, quality assurance, and regulatory compliance to meet evolving patient needs and industry standards.
Recent Developments:
- In May 2023, Zimmer Biomet Holdings Inc. finalized the acquisition of Ossis, a medical device company specializing in custom 3D-printed hip replacement implants. This strategic acquisition builds on a previous partnership in which Ossis collaborated with Zimmer Biomet in the Asia-Pacific region to provide hip and pelvic replacement solutions.
- In March 2023, Dentsply Sirona introduced the DS OmniTaper Implant System, a versatile solution designed for a wide range of clinical applications. This system features an intuitive drilling protocol that enhances procedural efficiency and a pre-mounted TempBase component that facilitates immediate restoration, thereby streamlining the overall workflow.
- In November 2023, Keystone Dental Holdings launched the GENESIS ACTIVE Implant System, a state-of-the-art surgical solution expected to transform dental implant placement and restoration approaches within the industry.
Market Concentration & Characteristics:
The osseointegration implants market is moderately fragmented, with a mix of established global players and emerging companies. The market is characterized by high levels of innovation, with companies focusing on developing advanced, biocompatible materials and customized implant solutions to enhance patient outcomes. Leading players such as Zimmer Biomet, Dentsply Sirona, and Keystone Dental Holdings maintain a competitive edge through extensive research and development investments, robust distribution networks, and strategic collaborations. Emerging firms often focus on niche applications and cutting-edge technologies to capture market share. The market’s growth is driven by an increasing demand for minimally invasive procedures, rising prevalence of orthopedic and dental conditions, and advancements in 3D printing and bioengineering. Despite intense competition, regulatory compliance, cost constraints, and the need for superior clinical efficacy remain critical factors influencing market dynamics and shaping competitive strategies.
Report Coverage:
The research report offers an in-depth analysis based on By Product, By Material and By End Users. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for customized and patient-specific implants will drive innovation in design and manufacturing technologies.
- Increasing prevalence of chronic orthopedic and dental disorders will continue to fuel the need for osseointegration implants globally.
- Advances in biocompatible materials, such as titanium and zirconia, will enhance implant durability and patient outcomes.
- Growing adoption of minimally invasive surgical techniques will increase the demand for implants offering faster recovery and superior integration.
- Expansion of healthcare infrastructure in emerging economies will improve access to advanced implant technologies.
- Regulatory changes focused on patient safety and clinical efficacy will shape product development and market entry strategies.
- Integration of robotics and AI in implant placement and surgical planning will streamline procedures and boost market adoption.
- Strategic partnerships and mergers will drive innovation, strengthen market positions, and expand product portfolios.
- Increasing awareness about aesthetic and functional benefits of dental implants will further boost demand.
- Investment in research for bioactive coatings and nanotechnology will lead to improved implant integration and reduced complications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Aging Population and Chronic Disease Prevalence
The global increase in the elderly population, who are more susceptible to bone-related disorders and tooth loss, is driving demand for osseointegration implants for both orthopedic and dental applications. This demographic shift is expanding the patient pool requiring advanced implant solutions.
Technological Advancements in Implant Design and Materials
Continuous innovation in implant materials such as titanium and zirconia, along with the adoption of 3D printing and CAD/CAM technologies, is improving implant integration, durability, and patient-specific customization, leading to higher success rates and broader adoption.
Rising Adoption of Minimally Invasive Surgeries
Minimally invasive surgical techniques, which offer reduced recovery times and fewer complications, are increasingly being used for implant placement. Osseointegration implants designed for these procedures are in higher demand as both patients and providers seek better clinical outcomes.
Expansion of Healthcare Infrastructure and Government Support
Growing investments in healthcare infrastructure, particularly in emerging markets, and supportive government policies for advanced medical treatments are increasing access to osseointegration procedures and driving market growth.
Increasing Awareness and Demand for Dental Implants
Greater awareness of the functional and aesthetic benefits of dental implants, combined with rising rates of edentulism and advancements in dental technology, is significantly boosting the adoption of osseointegration-based dental solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the osseointegration implants market?
What are the key drivers of market growth?
Which regions dominate the market?
What challenges does the market face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Dental Implants
- 1.2.2 Crown
- 1.2.3 Abutment
- 1.2.4 Definitive Abutment
- 1.2.5 Temporary Abutment
- 1.2.6 Hip Implants
- 1.2.7 Knee Implants
- 1.2.8 Spinal Implants
- 1.3 By Material
- 1.3.1 Ceramic Implants
- 1.3.2 Zirconia Implants
- 1.3.3 Stainless Steel Implants
- 1.3.4 Titanium
- 1.4 By End Users
- 1.4.1 Hospitals
- 1.4.2 Ambulatory Surgical Centres
- 1.4.3 Dental Clinics
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,275 million → 2032: USD 13,565.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Osseointegration Implants Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Osseointegration Implants Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Osseointegration Implants Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Osseointegration Implants Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Osseointegration Implants Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Osseointegration Implants Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Osseointegration Implants Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Osseointegration Implants Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,275 million → 2032: USD 13,565.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Osseointegration Implants Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Dental Implants
- 12.3.7.2 Crown
- 12.3.7.3 Abutment
- 12.3.7.4 Definitive Abutment
- 12.3.7.5 Temporary Abutment
- 12.3.7.6 Hip Implants
- 12.3.7.7 Knee Implants
- 12.3.7.8 Spinal Implants
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Ceramic Implants
- 12.4.7.2 Zirconia Implants
- 12.4.7.3 Stainless Steel Implants
- 12.4.7.4 Titanium
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End Users - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hospitals
- 12.5.7.2 Ambulatory Surgical Centres
- 12.5.7.3 Dental Clinics
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Osseointegration Implants End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Osseointegration Implants Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Osseointegration Implants Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Osseointegration Implants Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Zimmer Biomet
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Dentsply Sirona
- 18.4 Stryker
- 18.5 Medtronic
- 18.6 Institut Straumann AG
- 18.7 Smith & Nephew PLC
- 18.8 Osstem Implant
- 18.9 DePuy Synthes, Inc
- 18.10 Camlog
- 18.11 Southern Implants, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

