
Market Overview
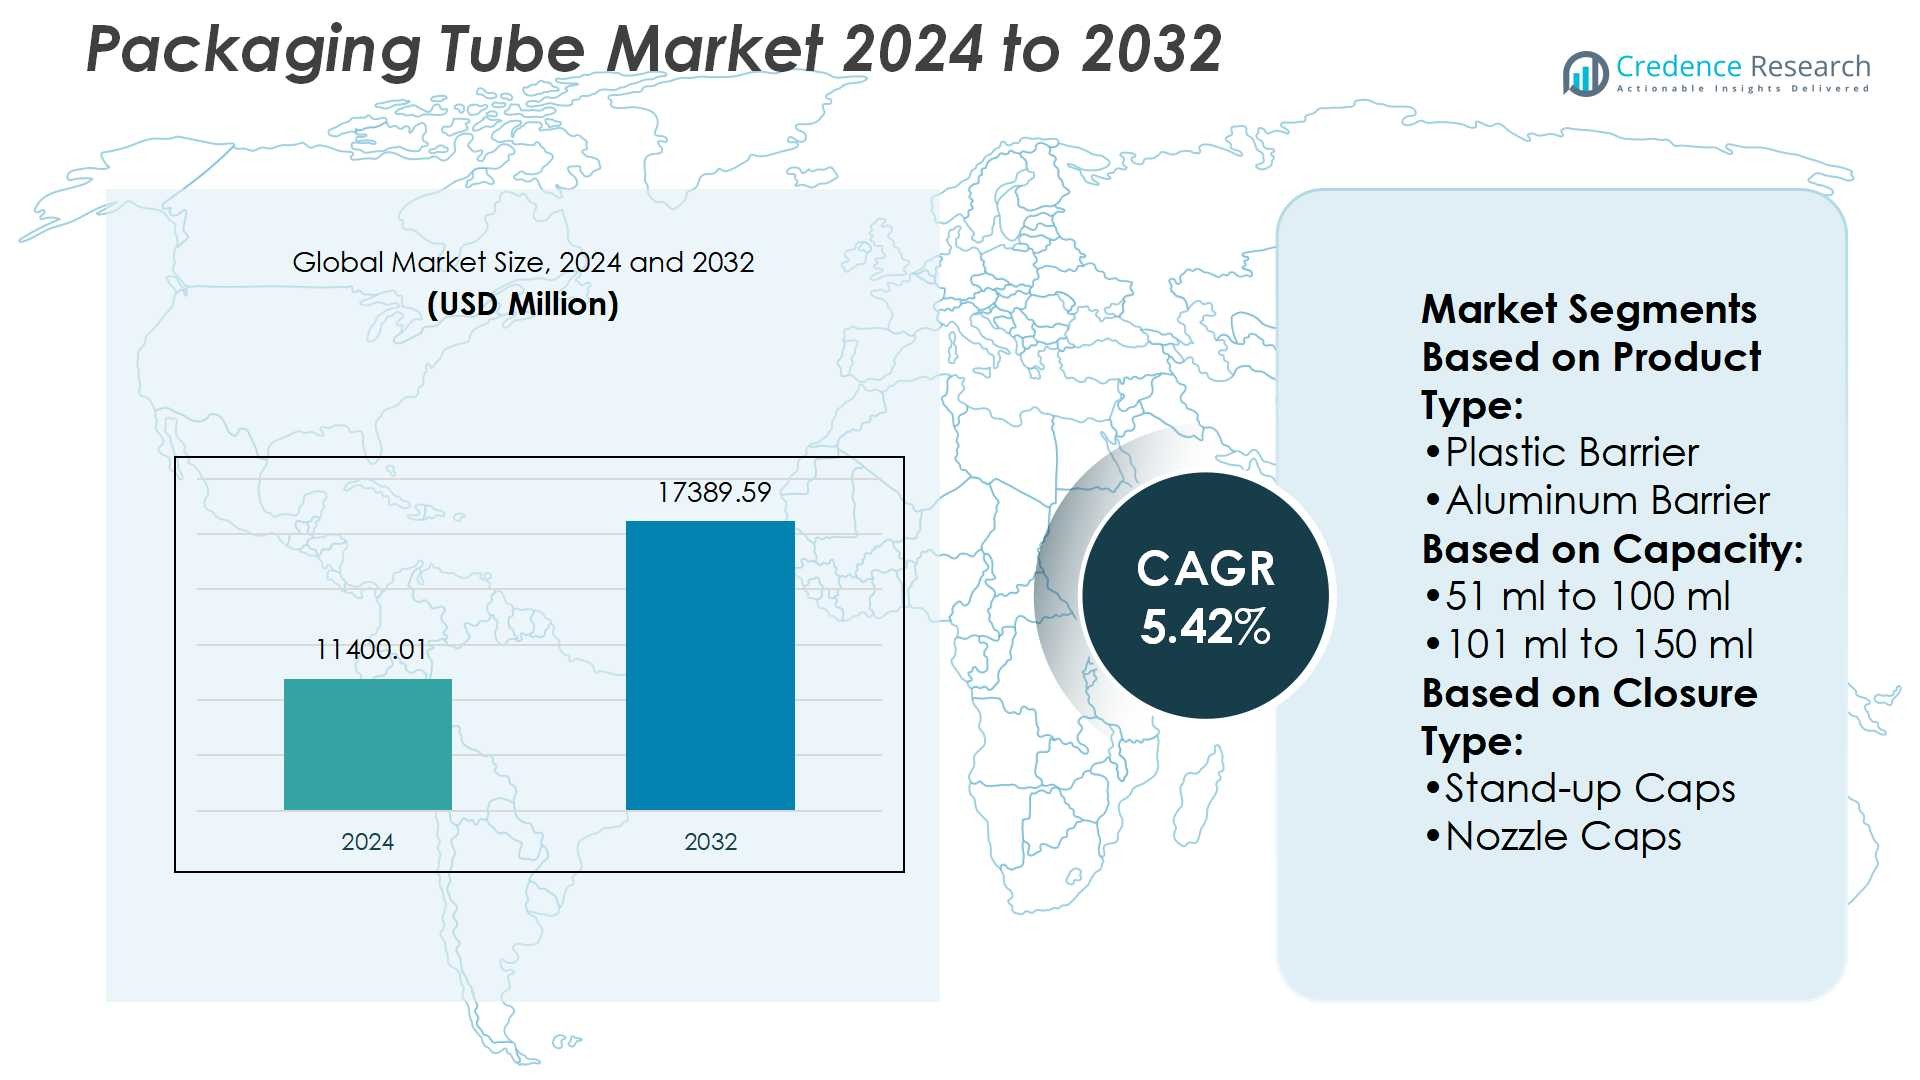
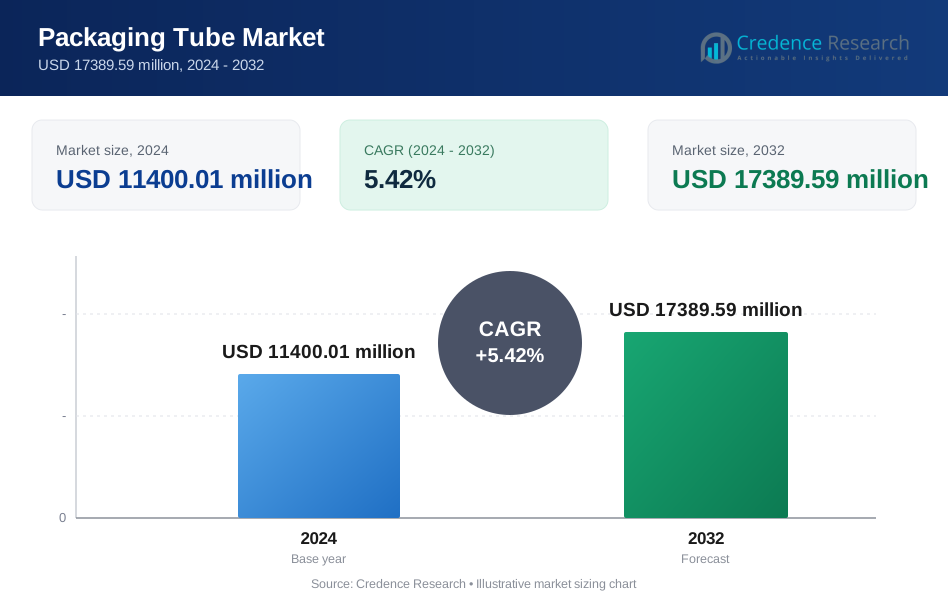
Packaging Tube Market size was valued USD 11400.01 million in 2024 and is anticipated to reach USD 17389.59 million by 2032, at a CAGR of 5.42% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Packaging Tube Market Size 2024 | USD 11400.01 Million |
| Packaging Tube Market, CAGR | 5.42% |
| Packaging Tube Market Size 2032 | USD 17389.59 Million |
The packaging tube market features strong competition with top players such as Amcor, Alpla Group, Berry Global, EPL, Albea, Antilla Propack, Evergreen Resources, Aphena Pharma Solutions, HCT Group, and CCL Industries. These companies emphasize innovation in laminated, plastic, and aluminum tube solutions to meet the growing demand from personal care, pharmaceuticals, and food sectors. Strategic investments in sustainable and recyclable materials, along with premium finishes and advanced printing, strengthen their market positioning. Regionally, Asia-Pacific leads the global market with a 34% share, driven by high consumption in cosmetics, pharmaceuticals, and rapid e-commerce growth.
 Market Insights
- The packaging tube market size was USD 11400.01 million in 2024 and will reach USD 17389.59 million by 2032, growing at a CAGR of 5.42%.
- Rising demand from personal care and pharmaceutical industries is driving adoption of laminated and plastic barrier tubes due to convenience, hygiene, and portability.
- Sustainability trends are shaping market growth, with companies focusing on recyclable, bio-based, and premium designs to align with consumer preferences and regulatory standards.
- Intense competition among players such as Amcor, Alpla Group, Berry Global, and EPL fosters innovation in printing technologies, closures, and lightweight structures, strengthening their global positions.
- Asia-Pacific leads with a 34% share, supported by high cosmetics and pharmaceutical consumption, while North America and Europe hold significant shares due to premium product demand; the 51 ml to 100 ml capacity segment dominates as the most consumed size across applications.
Market Segmentation Analysis:
By Product Type
Within the product type segment, laminated tubes dominate the market, holding the largest share. Their popularity stems from superior barrier protection, lightweight structure, and cost efficiency compared to aluminum alternatives. Laminated tubes are widely used in cosmetics, personal care, and pharmaceuticals, where aesthetics and product safety are critical. Demand is further supported by customization options, including high-quality printing and designs, which enhance brand appeal. The ongoing shift toward convenient, durable, and recyclable packaging continues to drive laminated tube adoption, making them the preferred choice across diverse end-use sectors.
- For instance, Essel Propack (now EPL Limited) supplies aluminum-barrier laminated (ABL) tubes to major companies like Colgate, Dabur, and Sanofi. With a global annual production of approximately 8 billion total tubes (both ABL and other types) and customizable sizing, including formats between 25-100 ml, the company provides tubes with excellent barrier properties for sensitive products.
By Capacity
The 51 ml to 100 ml capacity segment leads the market with the highest share. This dominance is driven by strong adoption in personal care products such as toothpaste, creams, and lotions, which require portable and user-friendly packaging sizes. These tubes offer a balance between convenience and cost-effectiveness, aligning with consumer demand for travel-friendly formats. Manufacturers focus on this range to cater to daily-use goods, making it the most consumed size category. Growth in e-commerce channels and increased purchases of mid-size packaged products further reinforce this segment’s leadership.
- For instance, Aisa’s Decoseam™ laminate tube production line runs between 100 and 240 tubes per minute while handling diameters from 19 mm to 63.5 mm, delivering decorated cosmetic tubes in the 50-100 ml range with full 360° printing and Synchroflow™ compression heading.
By Closure Type
Flip-top caps represent the dominant closure type in the packaging tube market, securing the largest share. Their popularity is attributed to ease of use, reusability, and secure sealing, which enhances consumer convenience. Flip-top caps are particularly favored in cosmetics, pharmaceuticals, and food packaging due to their ability to prevent leakage and ensure hygiene. Their ergonomic design and compatibility with various tube sizes strengthen their application range. Rising consumer preference for quick-dispensing and one-handed operation solutions continues to fuel growth in this sub-segment, consolidating its market leadership position.
Key Growth Drivers
Rising Demand in Personal Care and Cosmetics
The increasing consumption of skincare, haircare, and cosmetic products is a major driver for the packaging tube market. Tubes provide lightweight, portable, and user-friendly solutions that meet the needs of these industries. Their ability to preserve product integrity and support branding through advanced printing technologies enhances adoption. Growing consumer demand for premium and travel-size cosmetic products further boosts usage. Global brands rely on laminated and plastic barrier tubes to balance cost, aesthetics, and protection, solidifying their dominance in personal care packaging applications.
- For instance, Amcor offers a 1.5-inch laminate tube with a 22 mm threaded neck finish that can be paired with closures offering precise orifice sizes of 3.2 mm, 4.7 mm, and 6.4 mm for controlled dispensing.
Expansion of the Pharmaceutical Industry
Pharmaceutical growth is fueling demand for reliable and hygienic tube packaging formats. Tubes ensure accurate dosage, maintain product stability, and offer tamper-evident features, making them well-suited for ointments, gels, and creams. The industry’s focus on extending product shelf life through barrier protection is accelerating tube adoption. Additionally, regulatory emphasis on safe and convenient packaging supports this trend. With rising healthcare expenditure and the growing demand for OTC products, pharmaceutical companies are increasingly shifting to aluminum and laminated tubes for enhanced reliability.
- For instance, Aphena can manufacture and fill plastic or metal tubes in sizes from 1 gram micro-fills up to 225 grams large fills, using equipment handling items from lotions to heavy ointments, under cGMP-compliant, ISO 13485:2016 & ISO 9001:2015 certification.
Sustainability and Eco-Friendly Packaging Solutions
Growing environmental concerns and regulatory initiatives are pushing manufacturers toward sustainable packaging tubes. Consumers prefer recyclable and biodegradable options, encouraging companies to develop eco-friendly laminated and plastic tube alternatives. The shift toward bio-based plastics and recyclable aluminum tubes is gaining traction across food, cosmetics, and healthcare industries. Brands leverage sustainability as a differentiator, aligning packaging innovations with green commitments. This demand for environmentally responsible solutions is driving product development and positioning eco-friendly packaging as a key growth engine in the global tube market.
Key Trends & Opportunities
Premiumization and Customization in Tube Packaging
Brands are increasingly investing in premium designs and personalization features to strengthen market positioning. Advances in digital printing and decoration technologies allow high-quality graphics and textures that enhance shelf appeal. Customized tube sizes, shapes, and closures are being developed to suit specific product lines, especially in cosmetics and luxury skincare. This trend aligns with rising consumer preference for unique, aesthetic, and functional packaging. The growing importance of brand differentiation and customer experience continues to create opportunities in premiumized tube packaging.
- For instance, EPL’s “Platina™” laminate tubes use an EVOH barrier layer under 5% of total tube weight and have been certified fully recyclable including the shoulder and cap. The “Platina PRO 220” and “Platina PRO 250” product lines are cleared by RecyClass for entry into HDPE recycling streams.
Growth of E-Commerce and Direct-to-Consumer Sales
The rapid rise of e-commerce is transforming packaging tube demand. Online sales require packaging that is durable, lightweight, and easy to ship while maintaining product safety. Tubes meet these requirements, making them popular for personal care, pharmaceuticals, and food sold online. Compact, leak-proof, and travel-friendly packaging enhances consumer convenience in direct-to-consumer models. Manufacturers are optimizing tube structures for better performance in logistics and delivery. With digital retail expanding globally, this trend presents significant growth opportunities for innovative and protective tube packaging formats.
- For instance, Alpla’s “Tether Tube” for a 50 ml capacity weighs only 6 grams and is made entirely of one material, allowing it to be fully recyclable. The tethered closure is integrated in the tube body, permitting fall resistance from 2 metres onto the cap without causing leakage at the tear-off edge.
Adoption of Smart and Functional Features
The integration of smart features, such as QR codes and NFC-enabled packaging, is gaining traction in the tube market. These technologies enhance traceability, product authentication, and consumer engagement. Functional features like airless dispensing and precision nozzles are being adopted in cosmetics and pharmaceuticals to improve hygiene and usability. This trend allows brands to provide interactive experiences while ensuring product quality. The growing convergence of digital technology with packaging solutions is creating new opportunities for innovation and differentiation in tube packaging.
Key Challenges
Fluctuations in Raw Material Prices
Volatility in raw material costs, particularly plastics and aluminum, poses a challenge for manufacturers. Price fluctuations affect production expenses, forcing companies to adjust pricing strategies or absorb higher costs. These pressures can limit profit margins and hinder small and medium-sized producers from maintaining competitiveness. With rising demand for sustainable materials, sourcing recyclable or bio-based alternatives further adds to production complexity. Managing raw material dependency while balancing cost efficiency remains a key challenge in the packaging tube market.
Regulatory Compliance and Environmental Pressure
Stringent regulations on plastic usage and waste management are increasing compliance burdens for tube manufacturers. Governments worldwide are enforcing policies to reduce single-use plastics, driving companies to invest in sustainable alternatives. While necessary, these transitions require significant capital and R&D investment, affecting smaller firms. Failure to comply with environmental standards risks penalties and reputational damage. Balancing sustainability goals with performance, durability, and cost efficiency is a significant challenge, particularly in competitive markets with tight profit margins.
Regional Analysis
North America
North America holds a 32% share of the global packaging tube market, driven by strong demand from personal care, healthcare, and pharmaceutical sectors. The region benefits from high consumer spending on cosmetics and OTC products, which favor convenient and hygienic packaging. Technological advancements in tube manufacturing, coupled with the presence of leading packaging companies, reinforce regional growth. The United States dominates consumption, while Canada contributes through regulatory emphasis on eco-friendly packaging. Increasing adoption of sustainable laminated and plastic barrier tubes further strengthens market expansion across this region.
Europe
Europe accounts for 29% of the global packaging tube market, supported by advanced manufacturing capabilities and strong sustainability policies. Countries such as Germany, France, and the U.K. lead consumption due to high demand in cosmetics, pharmaceuticals, and premium personal care products. The European Union’s strict regulations on plastic waste have accelerated adoption of recyclable and biodegradable tube solutions. Consumers in this region also prefer premiumized and aesthetically designed packaging, driving innovation in customized tube formats. Sustainability commitments by global brands operating in Europe continue to boost market growth and product diversification.
Asia-Pacific
Asia-Pacific dominates the packaging tube market with a 34% share, driven by rapid urbanization, rising disposable incomes, and growing consumption of personal care and pharmaceutical products. China and India are key markets, benefiting from strong domestic demand and expanding manufacturing bases. Affordable laminated and plastic tubes are widely adopted, while increasing awareness of sustainable packaging fuels innovation. The region’s booming e-commerce sector further boosts the need for lightweight and protective tubes. With a large population base and expanding middle class, Asia-Pacific is expected to remain the fastest-growing regional market during the forecast period.
Latin America
Latin America captures 3% of the packaging tube market, with Brazil and Mexico serving as the primary contributors. Rising demand for personal care, beauty, and pharmaceutical products supports tube adoption across the region. Growth in disposable incomes and expanding retail networks enhance packaging consumption, particularly in urban areas. Local manufacturers focus on affordable plastic and laminated tube solutions, while sustainability awareness is gradually increasing. Although the regional share is smaller compared to others, growing investments in cosmetics and healthcare packaging indicate promising opportunities for future market expansion.
Middle East & Africa (MEA)
The Middle East & Africa accounts for 2% of the global packaging tube market, with growth concentrated in the Gulf Cooperation Council (GCC) countries and South Africa. Rising demand for personal care and pharmaceutical products is driving the adoption of convenient tube packaging formats. The region’s cosmetics market, supported by increasing consumer preference for premium products, is further stimulating tube demand. However, limited local manufacturing capabilities and high dependency on imports pose challenges. Despite its modest share, MEA offers long-term opportunities as global players expand distribution networks and sustainable packaging initiatives gain momentum.
Market Segmentations:
By Product Type:
- Plastic Barrier
- Aluminum Barrier
By Capacity:
- 51 ml to 100 ml
- 101 ml to 150 ml
By Closure Type:
- Stand-up Caps
- Nozzle Caps
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Competitive Landscape
The packaging tube market is highly competitive, with key players including Antilla Propack, Evergreen Resources, Amcor, Aphena Pharma Solutions, EPL, Alpla Group, Berry Global, HCT Group, Albea, and CCL Industries. The packaging tube market is characterized by intense competition, driven by innovation, sustainability, and customization. Manufacturers focus on developing advanced laminated, plastic, and aluminum barrier tubes that cater to diverse end-use industries, including personal care, pharmaceuticals, and food packaging. Growing emphasis on eco-friendly solutions, such as recyclable and bio-based materials, is reshaping strategies to align with global sustainability goals. Companies also prioritize premium designs, advanced printing, and functional closures to enhance product appeal and consumer convenience. Expansion into emerging markets, coupled with rising e-commerce demand, is encouraging investments in lightweight and durable packaging formats that ensure product safety and brand differentiation.
Key Player Analysis
- Antilla Propack
- Evergreen Resources
- Amcor
- Aphena Pharma Solutions
- EPL
- Alpla Group
- Berry Global
- HCT Group
- Albea
- CCL Industries
Recent Developments
- In October 2024, Albea Tubes launched its Greenleaf production at the Brampton, Ontario plant. This new plastic tube packaging line, which produces recyclable HDPE tubes, assists the oral care, cosmetics, and pharma industries in their shift from aluminum foil to all-plastic laminate tubes and further underscores Albea's commitment to sustainability.
- In January 2024, Kellanova Europe, in collaboration with Sonoco, redesigned its Pringles tubes by replacing the metal bottom with a recyclable paper-fiber alternative. This change adheres to the 4Evergreen Alliance guidelines and enhances curbside recyclability across Europe.
- In December 2023, Corpack introduced BioD, a sustainable screw cap made from cellulose-based material, designed for tube closures with a 35mm diameter. The industrially compostable cap features wood fibers for a natural appearance and is compatible with injection moulding and thermoforming processes.
- In March 2023, Prep & Smooth Face, a new one-step product from Nair, was introduced to assist customers in eliminating facial hair more quickly. It is also the first facial peel that offers extra skincare advantages
Report Coverage
The research report offers an in-depth analysis based on Product Type, Capacity, Closure Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily with rising demand in cosmetics and personal care.
- Pharmaceutical applications will expand due to increasing use of ointments, gels, and creams.
- Sustainable and recyclable materials will gain more importance in tube manufacturing.
- Premium and customized tube designs will attract stronger demand from global brands.
- Digital printing and decoration technologies will enhance brand visibility and product appeal.
- E-commerce growth will drive demand for durable, lightweight, and protective tube formats.
- Adoption of smart features like QR codes and NFC will improve traceability and engagement.
- Emerging economies will offer new opportunities through rising consumer spending.
- Regulations on plastic use will accelerate investment in eco-friendly packaging solutions.
- Strategic mergers and partnerships will strengthen global presence and product innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in Personal Care and Cosmetics Consumption
The increasing demand for skincare, haircare, and cosmetic products is fueling the adoption of packaging tubes, which offer portability, hygiene, and advanced branding opportunities through high-quality printing and customization.
Expansion of Pharmaceutical Applications
Pharmaceutical companies are increasingly using tube packaging for ointments, gels, and creams due to its ability to provide accurate dosing, tamper-evidence, and extended shelf life, aligning with regulatory and consumer safety requirements.
Sustainability and Eco-Friendly Packaging Initiatives
Rising environmental awareness and stricter regulations are driving manufacturers to develop recyclable, bio-based, and lightweight tube solutions, making sustainability a key differentiator and growth engine in the market.
E-Commerce and Direct-to-Consumer Channel Growth
The surge in online retail is boosting demand for durable, lightweight, and leak-proof tube packaging that ensures product safety during shipping and enhances consumer convenience, especially for personal care and pharmaceutical products.
Premiumization and Customization Trends
Brands are investing in premium tube designs, advanced decoration, and personalized packaging formats to enhance shelf appeal and differentiate products, responding to consumer preferences for unique and high-quality packaging.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Packaging Tube Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Packaging Tube Market projected to grow between 2025 and 2032?
Which Packaging Tube Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Packaging Tube Market?
Who are the leading companies in the Packaging Tube Market?
Which region commanded the largest share of the Packaging Tube Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Capacity
- 1.2.1 Below 50 ml
- 1.2.2 51 ml to 100 ml
- 1.2.3 101 ml to 150 ml
- 1.2.4 Above 150 ml
- 1.3 By Closure Type
- 1.3.1 Flip-top Caps
- 1.3.2 Stand-up Caps
- 1.3.3 Nozzle Caps
- 1.3.4 Screw Caps
- 1.4 By Product Type
- 1.4.1 Laminated Tubes
- 1.4.2 Plastic Barrier Tubes
- 1.4.3 Aluminum Barrier Tubes
- 1.5 By End-Use Industry
- 1.5.1 Personal Care & Cosmetics
- 1.5.2 Pharmaceuticals
- 1.5.3 Food & Beverages
- 1.5.4 Household Products
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 11400.01 million → 2032: USD 17389.59 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Packaging Tube Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Packaging Tube Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Packaging Tube Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Packaging Tube Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Packaging Tube Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Packaging Tube Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Packaging Tube Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Packaging Tube Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 11400.01 million → 2032: USD 17389.59 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Packaging Tube Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Capacity - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Below 50 ml
- 12.3.7.2 51 ml to 100 ml
- 12.3.7.3 101 ml to 150 ml
- 12.3.7.4 Above 150 ml
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Closure Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Flip-top Caps
- 12.4.7.2 Stand-up Caps
- 12.4.7.3 Nozzle Caps
- 12.4.7.4 Screw Caps
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Laminated Tubes
- 12.5.7.2 Plastic Barrier Tubes
- 12.5.7.3 Aluminum Barrier Tubes
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-Use Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Personal Care & Cosmetics
- 12.6.7.2 Pharmaceuticals
- 12.6.7.3 Food & Beverages
- 12.6.7.4 Household Products
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Packaging Tube End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Packaging Tube Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Packaging Tube Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Packaging Tube Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amcor
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Alpla Group
- 18.4 Berry Global
- 18.5 EPL (Essel Propack)
- 18.6 Albea
- 18.7 Antilla Propack
- 18.8 Evergreen Resources
- 18.9 Aphena Pharma Solutions
- 18.10 HCT Group
- 18.11 CCL Industries
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

