
Market Overview
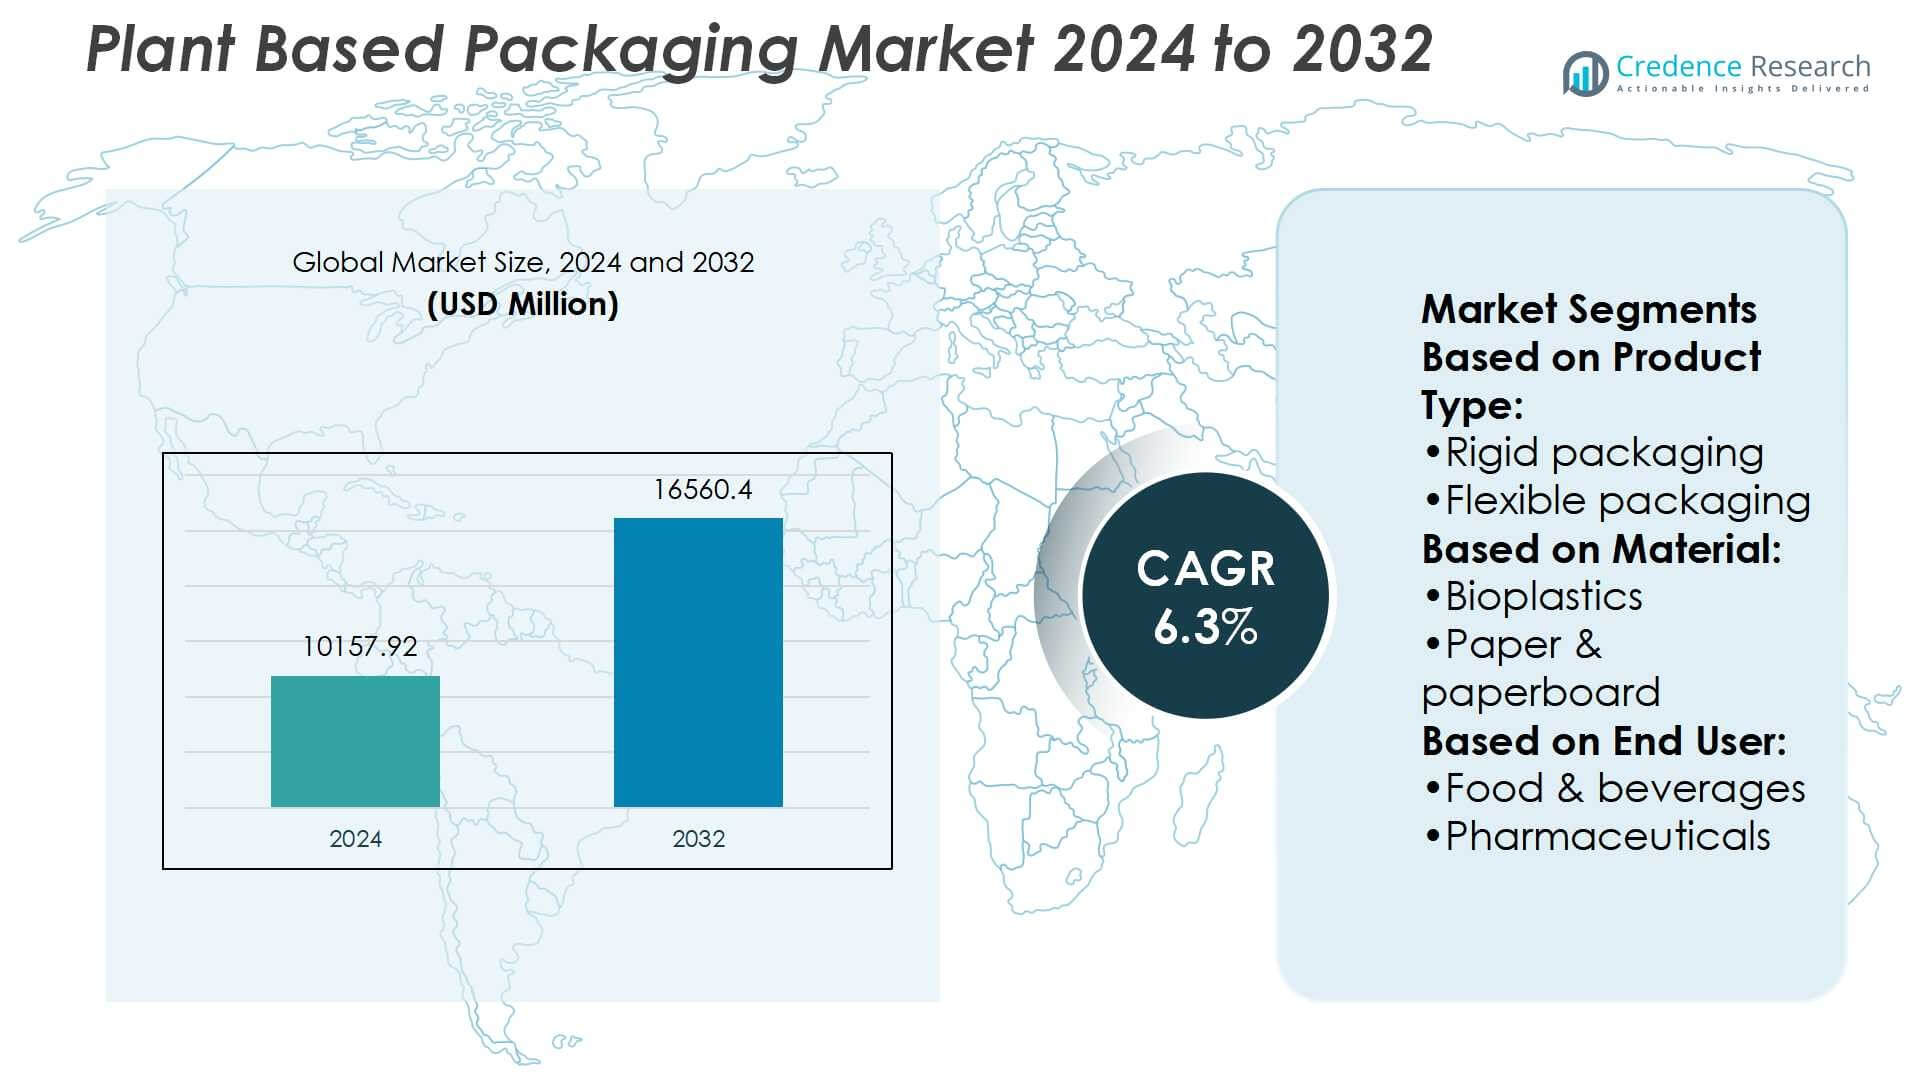
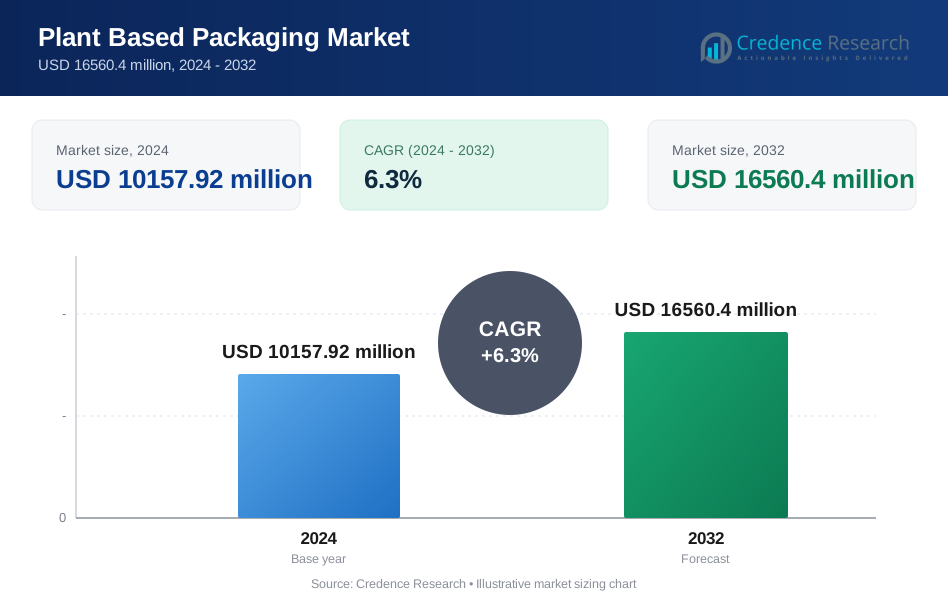
Plant Based Packaging Market size was valued USD 10157.92 million in 2024 and is anticipated to reach USD 16560.4 million by 2032, at a CAGR of 6.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Plant Based Packaging Market Size 2024 | USD 10157.92 Million |
| Plant Based Packaging Market, CAGR | 6.3% |
| Plant Based Packaging Market Size 2032 | USD 16560.4 Million |
The plant-based packaging market is shaped by leading players such as Amcor, Mondi Group PLC, Tetra Pak International SA, Berry Global, WestRock, BASF, Vegware, Biorgani, and Emsur, each contributing through innovation, scale, and sustainability-focused strategies. These companies emphasize advancements in bioplastics, molded fiber, and recyclable paperboard to strengthen their global positions and cater to food, beverages, cosmetics, and e-commerce sectors. Among regions, North America leads the market with a 35% share, supported by strong regulatory policies, consumer demand for eco-friendly products, and significant investments in sustainable packaging technologies. This leadership reflects a mature infrastructure and high adoption rates across industries.
 Market Insights
- The plant-based packaging market was valued at USD 10157.92 million in 2024 and is projected to reach USD 16560.4 million by 2032, growing at a CAGR of 6.3% during the forecast period.
- Rising demand for sustainable packaging solutions in food, beverages, and retail sectors acts as a key driver, supported by regulations on single-use plastics and growing consumer awareness.
- The market shows strong trends in bioplastics, molded fiber, and recyclable paperboard adoption, with leading companies investing in innovation and circular economy initiatives.
- High production costs and limited performance in water and heat resistance remain major restraints, restricting adoption in some industrial and pharmaceutical applications.
- North America leads with 35% market share, while rigid packaging dominates the product type segment, and food and beverages remain the top end-user category, highlighting strong adoption across developed markets and fast-growing opportunities in Asia-Pacific.
Market Segmentation Analysis:
By Product Type
Rigid packaging holds the dominant share in the plant-based packaging market due to its widespread use in bottles, trays, and containers. Its durability and protective features make it highly suitable for food and beverage applications, where maintaining product integrity is essential. The growing preference for sustainable rigid alternatives over petroleum-based plastics further strengthens this segment. Demand is supported by advancements in molded fiber and bioplastic rigid packaging that combine strength with eco-friendliness, ensuring compliance with stricter packaging regulations and boosting adoption across industries.
- For instance, ecovio® IS1335 is a mineral-filled, compostable injection-molding grade certified under DIN EN 13432. Its tensile (Young’s) modulus is about 3,600 MPa at 23 °C; strain at break is approximately 4 %.
By Material Type
Paper and paperboard represent the leading material segment, capturing the largest share of the market. Their recyclability, versatility, and cost-effectiveness drive extensive usage in retail and e-commerce packaging, including cartons, wraps, and bags. The rapid growth of online shopping and consumer demand for sustainable solutions has accelerated adoption in this category. Additionally, improvements in barrier coatings and strength-enhancing technologies have expanded applications of paper-based packaging to include liquid and perishable goods, strengthening its market dominance over other plant-based materials like bagasse and bamboo.
- For instance, Mondi Advantage High Strength sack kraft paper with a basis weight of 80 g/m² reaches a machine-direction (MD) tensile strength of 6.8 kN/m and cross-direction (CD) strength of 5.2 kN/m, per ISO 1924-3.
By End User
Food and beverages account for the largest end-user segment in the plant-based packaging market, supported by high consumption levels and strict sustainability requirements. This segment dominates due to rising consumer awareness of eco-friendly packaging and regulations targeting single-use plastics in food service and retail. Companies in this sector increasingly adopt compostable and recyclable solutions for cups, trays, bottles, and wrappers. Growing partnerships between food brands and packaging innovators further boost adoption, with plant-based alternatives helping reduce environmental footprints while meeting consumer expectations for safe and sustainable packaging.
Key Growth Drivers
Rising Demand for Sustainable Packaging
The shift toward eco-friendly packaging is a major driver in the plant-based packaging market. Increasing consumer awareness about plastic pollution and government bans on single-use plastics are fueling adoption. Companies across industries, particularly food and beverages, are actively transitioning to biodegradable, compostable, and recyclable alternatives. Plant-based packaging aligns with corporate sustainability goals, helping brands strengthen their environmental commitments and enhance consumer trust. The strong push for circular economy models further drives growth, positioning sustainable packaging as a strategic necessity rather than an option.
- For instance, Vegware's Close the Loop composting service processed 10,000 binloads of used packaging and food waste from customers in Central Belt Scotland, including sites like the Glasgow Science Centre and Fife College.
Expansion of Food and Beverage Industry
The food and beverage sector plays a pivotal role in driving plant-based packaging adoption. Growing demand for ready-to-eat meals, beverages, and packaged snacks has created significant opportunities for sustainable packaging solutions. Rigid and flexible formats made from paperboard, bioplastics, and bagasse are increasingly used to replace conventional plastics. Rising urbanization and a growing middle-class population worldwide further accelerate packaged food consumption. This sector’s dominance ensures continuous demand for innovative packaging that balances durability, food safety, and environmental responsibility, making it the largest growth contributor.
- For instance, Amcor's “Grace head” pump actuator is part of the mono-material Wave 2CC pump line, which uses 100% polyolefin construction. It can also be produced with Amcor’s CleanStream post-consumer recycled polypropylene (PCR).
Technological Advancements in Materials
Innovations in bioplastics, molded fiber, and coated paperboard are strengthening the capabilities of plant-based packaging. Advanced technologies enhance barrier properties, durability, and flexibility, enabling applications across diverse industries such as pharmaceuticals, cosmetics, and e-commerce. Developments in water-resistant coatings, heat-sealable bioplastics, and high-strength bamboo or bagasse composites are expanding market scope. These advancements address long-standing concerns over product safety and shelf life while offering cost-effective solutions. The integration of smart and functional features into sustainable packaging further boosts adoption, aligning with evolving consumer and regulatory expectations.
Key Trends & Opportunities
Growth of E-commerce and Retail Packaging
The rapid growth of e-commerce presents a significant opportunity for plant-based packaging providers. Online retailers require durable yet sustainable solutions for shipping goods across categories, from groceries to electronics. Paper-based cartons, molded fiber trays, and compostable mailers are gaining traction as eco-friendly options. Consumer preference for brands that prioritize green packaging also boosts adoption. With rising online sales worldwide, demand for plant-based solutions that ensure product protection while meeting sustainability goals is expected to remain a strong market trend.
- For instance, Tetra Pak's Tray Shrink 30 film-wrapper can handle 40 different tray sizes using a film as thin as 40 µm, aiming to minimize both material usage and electricity consumption.
Rising Adoption in Personal Care and Cosmetics
The personal care and cosmetics sector is emerging as a key adopter of plant-based packaging. Consumers increasingly demand eco-friendly solutions that align with natural and sustainable product positioning. Bioplastics, bamboo, and molded fiber are being used for jars, tubes, and cartons in this industry. Premium brands leverage sustainable packaging to differentiate themselves and appeal to environmentally conscious buyers. With growth in natural and organic cosmetics, this sector offers untapped potential for plant-based packaging companies, driving innovation and new product launches.
- For instance, Berry’s B Circular Range now includes 35 distinct items (closures, jars, triggers etc.) that can use 30% to 100% post-consumer recycled (PCR) plastic per item.
Key Challenges
Higher Production Costs Compared to Conventional Packaging
One of the key challenges for the plant-based packaging market is its relatively high production cost. Materials such as bioplastics and bamboo often require advanced processing technologies and specialized infrastructure, increasing manufacturing expenses. These costs can limit adoption, especially among small and medium enterprises. While large corporations absorb the costs for sustainability branding, widespread market penetration remains restricted. Reducing costs through economies of scale, government subsidies, and material innovations is essential to address this challenge and ensure competitive pricing.
Performance Limitations in Certain Applications
Despite advancements, plant-based packaging still faces performance-related challenges in areas like durability, water resistance, and heat tolerance. For instance, traditional plastic outperforms many biodegradable alternatives in preserving shelf life for perishable goods and ensuring leak-proof packaging. These limitations can restrict use in demanding sectors such as pharmaceuticals or industrial packaging. Although new coatings and composite solutions are emerging, widespread adoption depends on consistent performance that matches or exceeds conventional materials. Addressing these technical barriers is critical for market expansion across all end-user industries.
Regional Analysis
North America
North America holds the largest share of the plant-based packaging market, driven by strong regulatory frameworks and rising consumer awareness about sustainability. The U.S. leads the region with widespread adoption across food and beverages, retail, and pharmaceuticals. Companies invest heavily in bioplastics, paperboard, and molded fiber innovations to meet eco-friendly standards. Major brands such as Amazon and PepsiCo have integrated sustainable packaging into their operations, accelerating regional growth. Canada also supports expansion with government-backed initiatives promoting circular economy models. North America accounts for nearly 35% of global market share, reflecting its leadership in sustainable packaging adoption.
Europe
Europe maintains a significant position in the plant-based packaging market, supported by stringent EU directives on reducing single-use plastics and promoting recyclable materials. Countries such as Germany, France, and the U.K. are at the forefront of adopting paperboard, bagasse, and bioplastic solutions. Strong consumer demand for eco-friendly packaging in food and personal care sectors accelerates regional adoption. Investments in advanced recycling infrastructure and innovation in compostable materials further strengthen Europe’s market presence. With sustainability embedded in corporate and government strategies, Europe commands 30% of global market share, making it a critical hub for sustainable packaging innovation and compliance.
Asia-Pacific
Asia-Pacific is the fastest-growing region in the plant-based packaging market, driven by expanding food and beverage consumption and rapid e-commerce growth. Countries such as China, India, and Japan are leading adoption with government-backed bans on plastic usage and rising urbanization fueling demand. Manufacturers increasingly shift to paperboard and bagasse-based packaging to cater to eco-conscious consumers and regulatory requirements. The region’s vast population and rising middle class create large-scale opportunities for sustainable packaging adoption. Asia-Pacific accounts for 25% of global market share, and its strong growth trajectory positions it as a future leader in plant-based packaging solutions.
Latin America
Latin America is emerging as a growing market for plant-based packaging, supported by increasing environmental concerns and evolving regulatory frameworks. Brazil and Mexico are key contributors, with expanding retail and foodservice industries driving demand for compostable and recyclable alternatives. Companies in the region are gradually shifting from traditional plastics to paperboard and bagasse packaging, supported by consumer preference for eco-friendly products. Economic development and trade expansion further promote adoption across industrial and retail sectors. Latin America currently represents 6% of global market share, and ongoing sustainability initiatives are expected to strengthen its role in the global market.
Middle East & Africa
The Middle East & Africa region shows gradual growth in the plant-based packaging market, fueled by government policies to reduce plastic waste and promote sustainable alternatives. South Africa and the UAE lead regional adoption, with rising investments in eco-friendly packaging for food, beverages, and retail. Limited recycling infrastructure poses a challenge, but growing consumer awareness and international trade are encouraging adoption of paperboard and bioplastic packaging. The food and hospitality sectors serve as key growth areas in this region. Middle East & Africa account for 4% of global market share, with growth potential tied to regulatory advancements.
Market Segmentations:
By Product Type:
- Rigid packaging
- Flexible packaging
By Material:
- Bioplastics
- Paper & paperboard
By End User:
- Food & beverages
- Pharmaceuticals
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Competitive Landscape
The plant-based packaging market is highly competitive, with key players including Biorgani, BASF, Mondi Group PLC, Vegware, Amcor, Tetra Pak International SA, Berry Global, Emsur, and WestRock. The plant-based packaging market is characterized by strong competition, with companies focusing on innovation, sustainability, and scalability to gain an edge. Market participants are investing in advanced materials such as bioplastics, molded fiber, and coated paperboard to replace conventional plastics while maintaining product safety and durability. Strategic collaborations, mergers, and acquisitions are common approaches to expand regional presence and enhance production capacity. Continuous research into improving barrier properties, heat resistance, and recyclability ensures broader applications across food, pharmaceuticals, cosmetics, and e-commerce. The competitive landscape is further shaped by sustainability commitments and compliance with evolving environmental regulations.
Key Player Analysis
- Biorgani
- BASF
- Mondi Group PLC
- Vegware
- Amcor
- Tetra Pak International SA
- Berry Global
- Emsur
- WestRock
- Amcor
Recent Developments
- In August 2024, the Defence Research and Development Organisation (DRDO) developed PBAT-based biodegradable packaging that decomposes within three months. This eco-friendly packaging is used in various applications, including food and medical waste bags.
- In June 2024, Xampla’s plant-based coating was supplied to Huhtamaki for takeaway packaging. Huhtamaki and 2M Group of Companies will apply Xampla’s plant-based Morro Coating polymer to a range of takeaway boxes in a new, multi-year supply deal set to help Huhtamaki transition into recyclable, compostable, and renewable packaging solutions.
- In June 2024, Mondi adopts a traceless’ plant-based coating to upscale it into the paper industry. In a partnership with Mondi, traceless hopes to scale its plant-based coating across the paper industry and combat the generation of unnecessary plastic packaging waste.
- In December 2023, Novolex, through its brand Waddington North America (WNA), introduced food packaging containers that are recyclable and made with a minimum of 10% post-consumer recycled (PCR) content.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for sustainable packaging will continue to rise due to stricter plastic regulations.
- Food and beverage companies will remain the largest adopters of plant-based packaging solutions.
- Advancements in bioplastics will improve durability, heat resistance, and barrier performance.
- E-commerce growth will drive higher adoption of recyclable and compostable packaging formats.
- Personal care and cosmetics brands will increasingly use eco-friendly packaging for differentiation.
- Investment in recycling infrastructure will support wider adoption of circular packaging systems.
- Cost reduction strategies will make plant-based packaging more accessible to small businesses.
- Partnerships between material innovators and packaging manufacturers will accelerate product development.
- Asia-Pacific will emerge as the fastest-growing regional market for plant-based packaging.
- Corporate sustainability goals will push global brands to integrate plant-based solutions at scale.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Plant Based Packaging Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Plant Based Packaging Market projected to grow between 2025 and 2032?
Which Plant Based Packaging Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Plant Based Packaging Market?
Who are the leading companies in the Plant Based Packaging Market?
Which region commanded the largest share of the Plant Based Packaging Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Plant Based Packaging Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Plant Based Packaging Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 10157.92 million → 2032: USD 16560.4 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Plant Based Packaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Plant Based Packaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Plant Based Packaging Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Plant Based Packaging Market Drivers
- 3.3 Plant Based Packaging Market Restraints & Challenges
- 3.4 Plant Based Packaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Plant Based Packaging Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Plant Based Packaging Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Plant Based Packaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Plant Based Packaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Plant Based Packaging Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Plant Based Packaging market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Plant Based Packaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Plant Based Packaging Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Plant Based Packaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Plant Based Packaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Plant Based Packaging Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Plant Based Packaging Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Plant Based Packaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Plant Based Packaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Plant Based Packaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Plant Based Packaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Plant Based Packaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Plant Based Packaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Plant Based Packaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
