
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
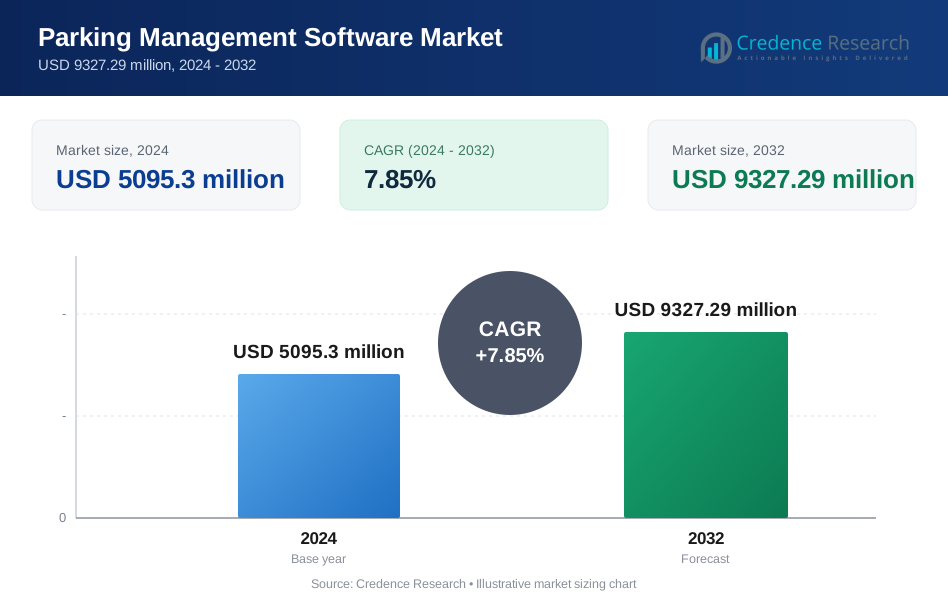
| Parking Management Software Market Size 2024 | USD 5095.3 million |
| Parking Management Software Market, CAGR | 7.85% |
| Parking Management Software Market Size 2032 | USD 9327.29 million |
Market Overview:
The Global Parking Management Software Market is projected to grow from USD 5095.3 million in 2024 to an estimated USD 9327.29 million by 2032, with a compound annual growth rate (CAGR) of 7.85% from 2024 to 2032.
Key drivers fueling the growth of the parking management software market include the rising adoption of smart city initiatives, increasing vehicle ownership, and growing demand for automated and digitalized parking systems. Government regulations aimed at reducing traffic congestion and promoting sustainable urban mobility have also accelerated the deployment of intelligent parking solutions. Additionally, advancements in technologies such as the Internet of Things (IoT), Artificial Intelligence (AI), and cloud computing have transformed traditional parking systems into integrated, data-driven platforms. These innovations enable predictive analytics, mobile payments, sensor-based navigation, and seamless parking reservations, thereby enhancing the overall user experience and operational efficiency. The increasing preference for contactless and cashless payment systems, especially after the COVID-19 pandemic, has further propelled the adoption of smart parking software across commercial, residential, and municipal segments.
Regionally, North America holds the largest market share in the global parking management software market, led by the United States and Canada. The region's dominance can be attributed to early technology adoption, strong infrastructure development, and proactive investments in smart transportation systems. Europe follows closely, with countries like the United Kingdom, Germany, and France investing heavily in smart mobility projects and environmentally sustainable transportation solutions. The Asia Pacific region is expected to witness the fastest growth during the forecast period, driven by rapid urban development, rising disposable incomes, and growing government focus on smart city frameworks in countries such as China, India, and Japan. Additionally, the Middle East and Africa and Latin America regions are gradually adopting parking management technologies, supported by increasing urbanization and improvements in digital infrastructure. Overall, the global parking management software market is poised for significant expansion as urban centers worldwide seek innovative ways to manage limited parking resources more efficiently.
Market Insights:
- The global parking management software market is projected to grow from USD 5095.3 million in 2024 to USD 9327.29 million by 2032, with a compound annual growth rate (CAGR) of 7.85% during the forecast period, driven by increasing urbanization and vehicle ownership, resulting in a heightened need for efficient parking solutions.
- The adoption of smart city initiatives is a key driver, as advanced technologies such as IoT, AI, and cloud computing are integrated into urban infrastructure, transforming traditional parking systems into intelligent, data-driven platforms.
- Government regulations aimed at reducing traffic congestion and promoting sustainable urban mobility are accelerating the adoption of parking management software, particularly those that align with eco-friendly goals like EV charging stations and shared mobility solutions.
- The demand for contactless and cashless payment systems has surged, especially post-COVID-19, as users seek safer, more convenient ways to access parking facilities and make payments.
- High initial implementation costs and the complexity of integrating new systems with existing infrastructure present significant barriers for small businesses and municipalities, potentially slowing down market adoption.
- Data security and privacy concerns are emerging as major challenges, with the increasing collection of sensitive user information and the need to ensure compliance with regulatory standards.
- While North America leads the market share, the Asia Pacific region is expected to experience the fastest growth due to rapid urbanization, rising disposable incomes, and increasing government investment in smart city frameworks.
Market Drivers:
Rising Urbanization and Vehicle Ownership
One of the primary drivers of the global parking management software market is the rapid pace of urbanization and the increasing number of vehicles on the roads. As cities expand and populations grow, the demand for efficient parking solutions becomes more critical. With more people owning private vehicles, urban areas face significant challenges in providing adequate parking spaces, which leads to traffic congestion and inefficient use of existing infrastructure. Parking management software offers an efficient solution by helping cities optimize available parking spaces, reduce congestion, and improve the overall flow of traffic. This trend is expected to continue as urban areas worldwide grow, pushing the need for advanced parking management solutions.
Technological Advancements in Smart City Infrastructure
The growing focus on smart cities and the integration of advanced technologies into urban infrastructure are fueling the demand for parking management software. The adoption of technologies such as the Internet of Things (IoT), Artificial Intelligence (AI), and cloud computing has revolutionized parking management systems. For example, IoT-enabled sensors can detect vehicle occupancy and transmit real-time data to cloud-based platforms, allowing users to access parking information via mobile apps or smart displays. These technologies enable real-time monitoring, dynamic pricing, space availability tracking, and the provision of mobile-based services for consumers. The integration of sensors, automated systems, and data analytics into parking systems enhances operational efficiency, reduces human error, and ensures a seamless experience for users. As governments and municipalities continue to invest in smart city initiatives, the demand for intelligent parking management solutions is expected to grow significantly.
Government Regulations and Sustainability Initiatives
Governments worldwide are introducing regulations to reduce traffic congestion and promote sustainable transportation. Policies aimed at reducing carbon emissions, encouraging the use of public transport, and optimizing the use of urban spaces have highlighted the importance of efficient parking systems. Parking management software helps authorities implement sustainable practices by ensuring optimal parking space usage, reducing the need for new parking constructions, and encouraging shared mobility solutions such as carpooling or ridesharing. Moreover, such software often integrates eco-friendly features like electric vehicle (EV) charging stations and digital parking reservations, aligning with government sustainability goals. These regulatory frameworks further stimulate market growth by encouraging the adoption of intelligent parking solutions.
Increased Demand for Contactless and Cashless Solutions
The COVID-19 pandemic has accelerated the global shift toward contactless and cashless solutions across various sectors, including parking management. As consumers prioritize health and safety, the demand for contactless payment systems in parking management has surged. For example, cities like Singapore have implemented contactless payment systems in parking facilities to enhance user safety and convenience. Parking management software that supports mobile payments, ticketless entry, and real-time tracking of available parking spaces allows users to avoid physical contact and reduces the need for cash transactions. This convenience and safety feature is becoming a key selling point for parking software solutions, especially in commercial and public spaces. The growing preference for touch-free solutions is expected to continue driving the adoption of advanced parking management systems, further enhancing market growth.
Market Trends:
Integration with Electric Vehicle (EV) Infrastructure
One of the key trends in the global parking management software market is the increasing integration of electric vehicle (EV) infrastructure. As the adoption of electric vehicles rises, the demand for EV charging stations within parking facilities is growing. Parking management software providers are incorporating features that allow users to locate available EV charging spots in real-time, facilitating a seamless experience for electric vehicle owners. This integration not only supports the transition to sustainable transportation but also enhances parking management systems by providing better data on the usage of EV charging stations. With governments and organizations pushing for greener solutions, the trend of incorporating EV infrastructure into parking management systems is expected to continue gaining momentum.
Mobile and Cloud-Based Parking Solutions
The shift toward mobile and cloud-based parking solutions is another significant trend in the parking management software market. Consumers and businesses alike are increasingly looking for more flexible, convenient, and accessible parking solutions. Mobile applications that allow users to find, reserve, and pay for parking spaces in real-time are becoming highly popular. Additionally, cloud-based parking management systems offer greater scalability, better integration capabilities, and cost efficiency, enabling cities and businesses to manage parking spaces more effectively. This trend is enabling users to access parking services remotely, enhancing customer convenience and operational efficiency for parking providers. As cloud computing and mobile platforms continue to evolve, the demand for these integrated parking management solutions is expected to rise.
Real-Time Data and Predictive Analytics
The use of real-time data and predictive analytics is transforming parking management systems. Parking management software solutions are increasingly incorporating sensors and data analytics to provide real-time information on parking availability, occupancy rates, and demand patterns. By using predictive analytics, these systems can forecast peak parking demand times, helping users find parking spaces more easily and enabling parking operators to optimize their resources. For instance, Parking Logix uses AI camera sensors to monitor EV charging spaces, ensuring they are used by eligible vehicles and providing valuable data insights to optimize station allocation. This trend improves operational efficiency and enhances the user experience, as it reduces the time spent searching for available parking spots. The continuous evolution of data analytics and machine learning technologies is expected to drive this trend, leading to more intelligent and responsive parking management systems.
Focus on Enhanced User Experience
Another growing trend in the parking management software market is the focus on enhancing the user experience. As competition among parking management software providers intensifies, there is an increasing emphasis on creating seamless, intuitive, and user-friendly platforms. Software solutions are now offering features such as personalized recommendations, easy payment options, and loyalty programs for frequent users. Moreover, the integration of voice recognition and navigation assistance into mobile apps is further improving the convenience for drivers. For example, mobile apps like 4Park guide users to the nearest charging station and allow for seamless payment and reservation management. As consumers continue to expect high levels of convenience and personalization in their digital experiences, the trend towards improving the user interface and experience in parking management software will continue to drive the market forward.
Market Challenges Analysis:
High Implementation Costs
One of the key restraints in the global parking management software market is the high initial cost of implementation. Developing and deploying advanced parking management solutions often require significant investments in hardware, software, and infrastructure. This can be a considerable barrier for small and medium-sized enterprises (SMEs) and municipalities with limited budgets. While the long-term benefits of parking management software, such as improved efficiency and revenue generation, can justify these costs, the upfront financial burden remains a challenge for many stakeholders. As a result, some organizations may hesitate to adopt these solutions, limiting the market’s overall growth potential.
Technological Integration and Compatibility Issues
Another challenge faced by the parking management software market is the complexity of integrating new systems with existing infrastructure. Many cities and businesses rely on legacy parking systems, which may not be compatible with modern, digital parking management solutions. The integration of various technologies, such as sensors, cloud computing, and mobile applications, requires significant technical expertise and can result in compatibility issues. These challenges can delay the adoption of new systems and increase operational costs, particularly for organizations that need to retrofit older systems to accommodate newer technologies.
Data Security and Privacy Concerns
As parking management software becomes more reliant on data, particularly real-time information and user-specific details, data security and privacy concerns have emerged as significant challenges. The collection, storage, and processing of sensitive user data raise the risk of data breaches and unauthorized access. For businesses and governments managing public parking, ensuring the security of their systems is crucial to maintaining user trust and complying with regulatory standards. For instance, EasyPark, Europe's largest parking app provider, experienced a data breach involving customer information, highlighting the importance of robust cybersecurity measures to protect user data and maintain trust. The increasing emphasis on data privacy laws and regulations further adds complexity to the deployment of parking management software, as developers must ensure compliance with various legal frameworks, particularly in different regions.
Lack of Standardization
The lack of standardization in parking management software presents a challenge to market growth. As the industry is still evolving, different parking management systems often use proprietary technologies, making it difficult to establish uniformity across platforms. This lack of standardization can create interoperability issues between different systems, reducing efficiency and complicating implementation for cities and businesses seeking to expand or integrate their parking operations. Standardizing solutions would promote more seamless integration and encourage broader adoption across various sectors.
Market Opportunities:
The global parking management software market presents several significant opportunities driven by the increasing adoption of smart city initiatives and advancements in technology. As urbanization accelerates, cities are investing heavily in smart infrastructure to improve mobility, reduce traffic congestion, and enhance the quality of life for residents. Parking management software plays a pivotal role in these smart city ecosystems by enabling real-time data tracking, dynamic pricing, and automated parking services. With the growing emphasis on creating efficient and sustainable urban environments, there is a tremendous opportunity for parking management software providers to offer solutions that align with government goals of reducing congestion and promoting sustainable transportation options. Additionally, the rise of electric vehicles (EVs) opens a new avenue for software providers to incorporate EV charging management into parking solutions, catering to the increasing demand for integrated, eco-friendly services.
Another key opportunity lies in the growing consumer preference for mobile-based, cashless parking solutions. The demand for contactless and convenient parking services continues to rise, particularly in the wake of the COVID-19 pandemic, which has accelerated the adoption of digital solutions across multiple sectors. Parking management software that integrates mobile applications for easy payments, reservations, and space finding offers a seamless user experience, making it increasingly attractive to both consumers and businesses. As businesses and municipalities recognize the benefits of optimizing parking resources, the market for innovative parking management solutions is expected to grow, creating opportunities for software providers to expand their customer base and develop new, more efficient solutions.
Market Segmentation Analysis:
By Solution Segment
The solution segment of the parking management software market includes, Access Control systems regulate vehicle entry and exit, ensuring secure and streamlined operations. Revenue Management focuses on optimizing pricing models, automating payment systems, and increasing financial returns. Parking Security and Surveillance integrates advanced surveillance technologies to provide safety for both vehicles and users. Parking Reservation Management allows users to pre-book parking spots, reducing congestion and improving customer experience. Finally, Analytics Solutions use real-time data and predictive analytics to optimize parking space usage, enhance operational efficiency, and reduce traffic congestion.
By Application Segment
In the application segment, On-Premise solutions are installed directly on-site, providing businesses with greater control over data security and infrastructure but often requiring higher initial investments. Cloud-Based applications, on the other hand, offer scalability, remote access, and cost-effectiveness. Cloud-based solutions are increasingly popular as they allow for easy updates, integration with other systems, and real-time data access, making them ideal for large-scale deployments.
By End-User Segment
The end-user segment serves a diverse range of customers. Residential parking solutions cater to private housing and apartment complexes, offering convenience through integrated smart home systems. Commercial parking is geared towards businesses, office buildings, and retail centers, focusing on optimizing customer parking experiences and maximizing available space. Government and Municipalities handle public parking and urban mobility challenges, deploying software solutions to improve efficiency and reduce congestion in city centers.
By Deployment Segment
The deployment segment includes both On-Premise and Cloud-Based solutions. On-Premise systems are installed locally, giving businesses control over their infrastructure and data security. They are typically used by organizations that require high levels of control and customization. Cloud-Based solutions, in contrast, are hosted remotely, offering flexibility, scalability, and lower upfront costs. They are increasingly favored for their ease of access, ability to integrate with other systems, and reduced maintenance requirements.
Segmentation:
By Solution Segment
- Access Control
- Revenue Management
- Parking Security and Surveillance
- Parking Reservation Management
- Analytics Solutions
By Application Segment
- On-Premise
- Cloud-Based
By End-User Segment
- Residential
- Commercial
- Government and Municipalities
By Deployment Segment
- On-Premise
- Cloud-Based
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The global parking management software market is characterized by varying growth dynamics across different regions, driven by local urbanization rates, technological adoption, and government initiatives. Among these, North America holds the largest market share, accounting for approximately 35% of the total market in 2024. The United States and Canada lead the region, where urban areas have already embraced advanced parking solutions. The region’s dominance can be attributed to its early adoption of smart city initiatives, high infrastructure development, and significant investments in IoT and cloud computing technologies. With a high concentration of tech-savvy consumers and parking management solutions providers, North America is expected to continue driving market growth throughout the forecast period.
Europe follows closely, contributing around 30% to the global market share. The demand for parking management software in Europe is primarily driven by countries like the United Kingdom, Germany, and France, where smart city frameworks and sustainability initiatives are key priorities. Governments in these countries are investing in technologies that reduce traffic congestion and enhance the overall efficiency of urban mobility. Additionally, the increasing number of electric vehicles (EVs) in Europe has led to a surge in the demand for parking management solutions that can accommodate EV charging stations. The region’s focus on eco-friendly policies and infrastructure development ensures continued growth in the adoption of parking management software.
The Asia Pacific region is experiencing the fastest growth in the parking management software market. The market share in this region is projected to increase from approximately 18% in 2024 to 22% by 2032. Rapid urbanization, rising vehicle ownership, and significant investments in smart city projects, particularly in countries like China, India, and Japan, are the primary drivers of this growth. With dense populations and increasing traffic congestion, the demand for intelligent parking solutions that optimize space and enhance convenience is substantial. Additionally, government policies aimed at modernizing transportation infrastructure are further contributing to the adoption of parking management software in this region.
The Middle East and Africa (MEA) and Latin America (LATAM) regions hold smaller market shares but present significant growth opportunities. MEA’s market share is estimated at around 7%, with the United Arab Emirates and Saudi Arabia showing considerable interest in smart city technologies. Similarly, LATAM is expected to account for approximately 10% of the global market, with Brazil and Mexico emerging as key players. Both regions are witnessing increasing investments in urban mobility and digital infrastructure, indicating the potential for growth in parking management software adoption in the coming years.
Key Player Analysis:
- ParkMobile, LLC
- Amano Corporation
- TIBA Parking Systems
- Passport Parking Inc.
- Skidata AG
- SAP SE
- Siemens AG
- Cisco Systems, Inc.
- Parkopedia
- Kapsch TrafficCom AG
Competitive Analysis:
The global parking management software market is highly competitive, with a mix of established players and emerging startups striving to capture market share. Leading companies such as Amano McGann, T2 Systems, and Flowbird dominate the market, offering a wide range of solutions, including real-time parking management, payment processing, and integrated mobile applications. These key players benefit from their strong brand presence, comprehensive product offerings, and established customer base in both private and public sectors. Emerging companies are increasingly focusing on innovative features such as Artificial Intelligence (AI)-based analytics, smart sensors, and EV charging station integration to differentiate themselves. The market also sees heightened competition in the form of partnerships, mergers, and acquisitions, as companies seek to expand their technological capabilities and geographical reach. As smart city initiatives grow globally, the competition is expected to intensify, prompting established and new players to continually innovate and enhance their offerings to meet the evolving needs of urban mobility and parking management.
Recent Developments:
- In May 2024, Nationwide Parking Services, a U.S.-based parking solutions provider, collaborated with Get My Parking, a U.S.-based software company. Through this partnership, they plan to develop innovative solutions, including the custom-branded NWPRK app, which offers a seamless way to find, book, and pay for parking across various facilities.
- In July 2022, Flowbird Groupexpanded its digital capabilities through the acquisition of YourParkingSpace. This strategic move enhances Flowbird’s off-street parking services, particularly in the UK market, but also aligns with the company’s broader strategy to broaden its offerings in digital parking solutions, tapping into the growing demand for integrated parking system.
- In September 2023, TIBA Parking Systems partnered with REEF Technology to create a data-driven platform for parking operators and landlords. This partnership aims to enhance the parking experience by leveraging data insights.
- In November 2022, DESIGNA announced the acquisition of NextGen Parking, LLC, based in Houston, Texas. This acquisition reflects the ongoing consolidation in the parking management industry, as larger companies expand their offerings and geographic reach.
Market Concentration & Characteristics:
The global parking management software market exhibits a moderate level of concentration, with a few large players holding a significant share of the market, while numerous smaller companies compete in niche segments. Key players such as Amano McGann, T2 Systems, and Flowbird dominate the landscape by offering comprehensive solutions that address various aspects of parking management, including ticketing, space reservation, and payment processing. These companies benefit from strong brand recognition, established customer bases, and robust product portfolios. However, the market is also characterized by innovation and fragmentation, with emerging players focusing on specialized features like Artificial Intelligence (AI), IoT integration, and EV charging management to differentiate themselves. The increasing demand for smart city solutions, sustainability initiatives, and mobile-based applications is fueling innovation, encouraging both established firms and startups to develop advanced, tailored solutions. This dynamic environment indicates a competitive landscape with opportunities for growth and technological advancements.
Report Coverage:
The research report offers an in-depth analysis based on By Solution Segment, By Application Segment, By End-User Segment and By Deployment Segment. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The global parking management software market is poised for significant growth in the coming years, driven by rising demand for efficient parking solutions.
- Urbanization and increased vehicle ownership will continue to propel the need for advanced parking management systems.
- Government initiatives focused on smart city development will enhance the adoption of intelligent parking technologies.
- The integration of electric vehicle (EV) charging stations within parking facilities will emerge as a critical area for growth.
- Cloud-based and mobile parking platforms will lead the market, offering greater flexibility and convenience to users.
- The use of real-time data analytics and predictive technologies will optimize parking operations and improve customer experiences.
- The growing preference for contactless and cashless payment solutions will drive further adoption of digital parking management systems.
- The Asia Pacific region will experience the fastest market growth, fueled by rapid urbanization and investments in smart infrastructure.
- Market competition will intensify as new players innovate with technologies such as AI, IoT, and blockchain.
- Increased focus on sustainability and eco-friendly transportation solutions will shape the future of parking management.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Urbanization and Vehicle Ownership
Rapid urbanization and increasing vehicle ownership are straining existing parking infrastructure, creating a critical need for efficient, technology-driven parking management solutions in cities worldwide.
Smart City Initiatives and Technological Advancements
Government and municipal investments in smart city projects are driving the adoption of IoT, AI, and cloud-based parking management platforms, transforming traditional parking into intelligent, data-driven systems.
Government Regulations and Sustainability Goals
Policies aimed at reducing traffic congestion, lowering carbon emissions, and promoting sustainable urban mobility are accelerating the deployment of parking management software that supports eco-friendly practices and shared mobility.
Demand for Contactless and Cashless Payment Systems
The shift toward contactless and cashless transactions, especially post-pandemic, is boosting the adoption of digital parking solutions that offer mobile payments, ticketless entry, and enhanced user convenience.
Integration with Electric Vehicle (EV) Infrastructure
The growing adoption of electric vehicles is increasing demand for parking management software that can support real-time EV charging station availability and reservations, aligning with broader sustainability and mobility trends.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Parking Management Software Market?
What factors are driving the growth of the Global Parking Management Software Market?
What are some challenges faced by the Global Parking Management Software Market?
Who are the major players in the Global Parking Management Software Market?
Which segment is leading the Global Parking Management Software Market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User Segment
- 1.2.1 Residential
- 1.2.2 Commercial
- 1.2.3 Government and Municipalities
- 1.3 By Solution Segment
- 1.3.1 Access Control
- 1.3.2 Revenue Management
- 1.3.3 Parking Security and Surveillance
- 1.3.4 Parking Reservation Management
- 1.3.5 Analytics Solutions
- 1.4 By Deployment Segment
- 1.4.1 On-Premise
- 1.4.2 Cloud-Based
- 1.5 By Application Segment
- 1.5.1 On-Premise
- 1.5.2 Cloud-Based
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5095.3 million → 2032: USD 9327.29 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Parking Management Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Parking Management Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Parking Management Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Parking Management Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Parking Management Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Parking Management Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Parking Management Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Parking Management Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5095.3 million → 2032: USD 9327.29 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Parking Management Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User Segment - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Residential
- 12.3.6.2 Commercial
- 12.3.6.3 Government and Municipalities
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Solution Segment - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Access Control
- 12.4.6.2 Revenue Management
- 12.4.6.3 Parking Security and Surveillance
- 12.4.6.4 Parking Reservation Management
- 12.4.6.5 Analytics Solutions
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment Segment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 On-Premise
- 12.5.6.2 Cloud-Based
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Application Segment - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 On-Premise
- 12.6.6.2 Cloud-Based
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Parking Management Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Parking Management Software Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Parking Management Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Parking Management Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ParkMobile, LLC
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Amano Corporation
- 18.4 TIBA Parking Systems
- 18.5 Passport Parking Inc.
- 18.6 Skidata AG
- 18.7 SAP SE
- 18.8 Siemens AG
- 18.9 Cisco Systems, Inc.
- 18.10 Parkopedia
- 18.11 Kapsch TrafficCom AG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

