
Market Overview
The passenger ferries market is projected to grow from USD 2,900 million in 2024 to USD 3,734 million by 2032, registering a CAGR of 3.21% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Passenger Ferries Market Size 2024 | USD 2,900 million |
| Passenger Ferries Market, CAGR | 3.21% |
| Passenger Ferries Market Size 2032 | USD 3,734 million |
The passenger ferries market is driven by rising demand for cost-effective and eco-friendly maritime transport, supported by increasing tourism, urban mobility needs, and expansion of coastal routes. Governments and operators are investing in modern fleets with enhanced fuel efficiency and lower emissions to meet environmental regulations. Trends highlight the adoption of electric and hybrid ferries, integration of digital ticketing and onboard connectivity, and growing emphasis on passenger safety and comfort. Expansion of ferry networks in emerging economies and partnerships between private operators and governments further strengthen the market’s long-term growth outlook.
The passenger ferries market shows diverse geographical dynamics, with Europe leading at 33% supported by advanced infrastructure and tourism demand. Asia-Pacific follows with 28%, driven by urbanization and coastal connectivity, while North America holds 26% with strong reliance on commuter and tourist routes. Latin America captures 7% through growing coastal tourism, and the Middle East & Africa account for 6% with rising urban mobility initiatives. Key players include BC Ferries, Brittany Ferries, DFDS Seaways, Irish Ferries, Jadrolinija, Minoan Lines, P&O Ferries, Stena Line, Tallink Grupp, and Washington State Ferries.
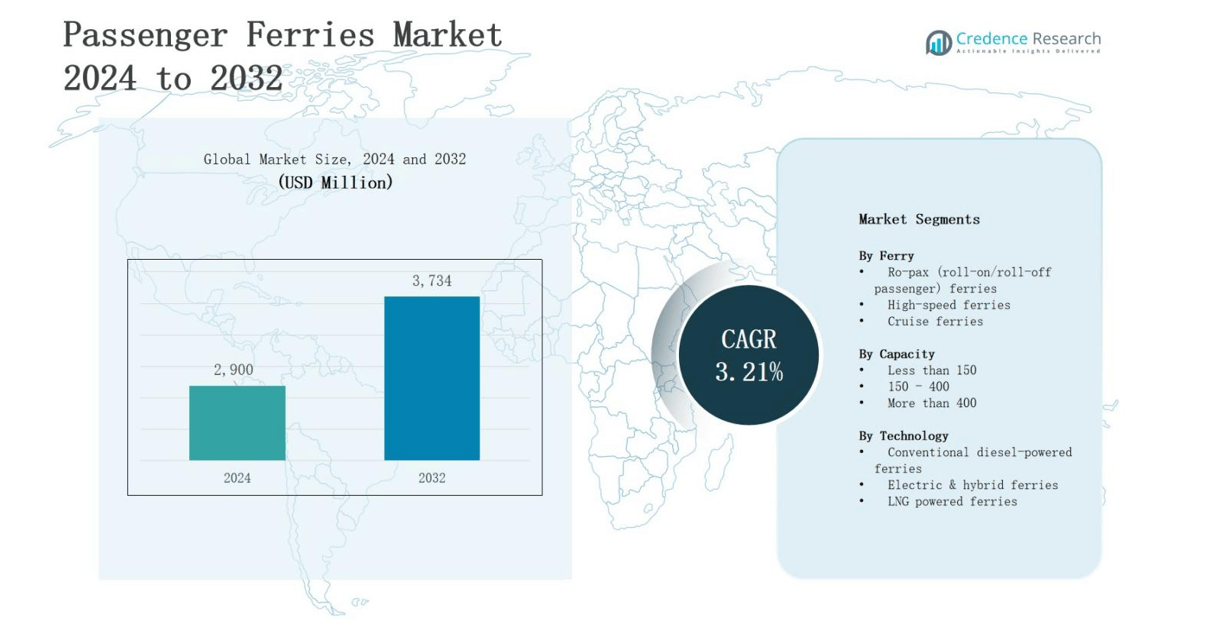
Market Insights
- The passenger ferries market is projected to grow from USD 2,900 million in 2024 to USD 3,734 million by 2032, registering a steady CAGR of 3.21% during the forecast period.
- By ferry type, Ro-pax ferries dominate with 48% share, followed by high-speed ferries at 32% and cruise ferries at 20%, reflecting strong demand across commuter and tourism sectors globally.
- By capacity, ferries with more than 400 seats lead at 44%, 150–400 capacity ferries account for 37%, while less than 150 seats contribute 19%, serving regional and community routes.
- By technology, conventional diesel-powered ferries still command 55% share, while electric and hybrid ferries rise to 28%, and LNG-powered ferries secure 17%, highlighting transition toward sustainable transport solutions.
- Europe leads regionally with 33% share, followed by Asia-Pacific at 28% and North America at 26%, while Latin America holds 7% and Middle East & Africa contribute 6%.
Market Drivers
Growing Tourism and Coastal Connectivity Demand
The passenger ferries market benefits strongly from the surge in global tourism and expansion of coastal transport services. Rising international travel and domestic leisure activities increase reliance on ferries as affordable and scenic transport options. Governments are expanding maritime routes to connect islands, coastal towns, and metropolitan hubs, enhancing regional accessibility. It creates sustainable demand for ferries that cater to both daily commuters and seasonal travelers. Operators invest in advanced vessels to meet growing passenger expectations.
- For instance, Thames Clippers launched Earth Clipper, Europe’s first hybrid high-speed passenger ferry in Central London, achieving nearly 90% reduction in CO2 emissions.
Focus on Sustainable and Eco-Friendly Transportation
The passenger ferries market is gaining traction with a strong push toward reducing carbon emissions and promoting sustainable transport solutions. Governments enforce stricter environmental regulations, prompting operators to adopt eco-friendly ferries powered by hybrid and electric propulsion. It positions ferries as a sustainable alternative to road or air travel in short-distance routes. Growing public awareness of climate issues also drives acceptance of greener solutions. Manufacturers actively develop fuel-efficient technologies to enhance market adoption.
- For instance, Brittany Ferries' fleet includes hybrid-electric deep-water vessels like the Guillaume de Normandie, which features a modular propulsion system capable of running on batteries alone at speeds up to 17.5 knots, significantly reducing fossil fuel usage and emissions.
Government Investments and Infrastructure Development
The passenger ferries market receives significant support from public investments in port infrastructure and fleet modernization. Governments fund expansion of ferry terminals, docking facilities, and navigation systems to improve efficiency and safety. It ensures reliable services that promote public preference for ferries in coastal and urban transport. Subsidies and partnerships with private operators further boost fleet upgrades. Enhanced infrastructure enables ferries to handle larger passenger volumes and ensures long-term service reliability across multiple regions.
Advancement in Technology and Passenger Experience
The passenger ferries market is shaped by technological upgrades that enhance safety, efficiency, and passenger comfort. Operators adopt digital ticketing, GPS navigation, and real-time scheduling to improve operations. It strengthens customer trust and convenience, particularly in urban and tourist-heavy areas. Introduction of luxury seating, Wi-Fi, and entertainment systems increases passenger satisfaction. Integration of smart systems also improves energy efficiency and vessel performance. These advancements help operators remain competitive in global maritime transportation.
Market Trends
Adoption of Electric and Hybrid Ferry Solutions
The passenger ferries market is witnessing a strong shift toward electric and hybrid propulsion systems to reduce fuel costs and emissions. Operators are investing in vessels equipped with battery storage and hybrid engines to comply with stricter emission standards. It creates opportunities for manufacturers to develop advanced propulsion technologies. Growing environmental awareness among travelers supports adoption of green transport solutions. Ports are also upgrading charging infrastructure to accommodate this emerging demand, further driving momentum globally.
- For instance, Washington State Ferries recently converted the Wenatchee, North America’s largest hybrid-electric passenger ferry, which is expected to reduce fuel consumption by 25% and climate pollution by up to 20% while providing a quieter and cleaner passenger experience.
Integration of Digitalization and Smart Ticketing
The passenger ferries market is increasingly shaped by digital transformation, with operators implementing online booking systems and contactless ticketing. Real-time tracking, mobile apps, and automated scheduling improve service efficiency and passenger convenience. It allows ferry operators to optimize routes and manage capacity effectively. Enhanced data analytics also supports predictive maintenance and cost savings. These developments strengthen customer loyalty while ensuring operational transparency, positioning digitalization as a critical trend in the maritime passenger sector worldwide.
Expansion of Luxury and Tourism-Oriented Services
The passenger ferries market is evolving with growing focus on enhancing passenger experience through premium services. Operators are introducing modern interiors, Wi-Fi connectivity, dining options, and entertainment systems to meet rising expectations of tourists. It aligns ferries with cruise-like experiences for short to medium routes. Luxury-focused investments are attracting high-value customers and expanding market reach. The trend supports strong growth in regions with vibrant tourism, particularly Europe, Southeast Asia, and island economies worldwide.
- For instance, Damen Shipyards launched the Ferry 3508 electric, which combines eco-friendly design with spacious seating and sophisticated climate control systems to elevate passenger comfort in an environmentally conscious product.
Strategic Partnerships and Fleet Modernization
The passenger ferries market reflects increasing collaborations between governments, private operators, and shipbuilders to modernize fleets. Joint ventures and public-private partnerships aim to expand ferry routes and improve service efficiency. It fosters innovation in vessel design, safety standards, and sustainability. Operators are replacing aging fleets with advanced models that meet modern regulations. This collaborative approach ensures resilience against rising passenger demand and positions ferries as a reliable transport mode in global maritime infrastructure.
Market Challenges Analysis
High Operating Costs and Fuel Price Volatility
The passenger ferries market faces challenges due to high operating expenses and unpredictable fuel costs. Operators struggle to maintain profitability while meeting environmental standards and offering competitive fares. It increases financial pressure on companies operating older fleets with lower efficiency. Rising maintenance costs, crew wages, and insurance premiums further strain margins. Many operators delay investments in fleet modernization due to limited funding, creating inefficiencies that restrict growth. These challenges hinder long-term expansion prospects.
Regulatory Pressures and Infrastructure Limitations
The passenger ferries market must comply with stringent safety and environmental regulations, which require costly upgrades. Smaller operators find it difficult to meet international standards on emissions and safety equipment. It restricts market participation and limits service expansion in underdeveloped regions. Inadequate port infrastructure and limited charging facilities for hybrid or electric ferries also slow adoption of sustainable solutions. Delays in government approvals for new routes add operational barriers. These issues collectively challenge the sector’s scalability.
Market Opportunities
Expansion of Green and Sustainable Ferry Solutions
The passenger ferries market holds strong opportunities through adoption of electric, hybrid, and alternative fuel-powered vessels. Governments and operators are prioritizing decarbonization efforts, creating demand for sustainable propulsion technologies. It allows manufacturers to innovate in energy-efficient engines, battery storage, and hydrogen-based systems. Growing investment in charging and refueling infrastructure further accelerates this transition. Operators offering eco-friendly solutions gain regulatory advantages and attract environmentally conscious passengers. This shift positions ferries as a sustainable alternative to road or air travel.
Rising Tourism and Emerging Coastal Economies
The passenger ferries market benefits from growing tourism and increasing development of coastal economies in Asia-Pacific, Latin America, and island nations. Expanding middle-class populations and rising disposable incomes create demand for affordable and scenic transport options. It enables operators to launch new routes that connect islands, ports, and metropolitan hubs. Governments encourage ferry adoption to ease urban congestion and strengthen regional connectivity. Opportunities also lie in luxury tourism services, combining convenience with premium passenger experiences across developing regions.
Market Segmentation Analysis:
By Ferry Type The passenger ferries market is segmented into Ro-pax ferries, high-speed ferries, and cruise ferries. Ro-pax ferries hold the largest share at around 48%, driven by their dual role in transporting passengers and vehicles. High-speed ferries account for nearly 32%, supported by urban mobility and tourism demand. Cruise ferries represent 20%, appealing to travelers seeking leisure-focused short journeys. It highlights diversified demand across commuter, logistics, and tourism applications in global markets.
- For instance, Damen, a leading shipbuilder, offers Ro-pax ferries such as the Fast RoPax series that can carry 60 passengers on the upper deck and 10 cars below, tailored for coastal and seagoing routes.
By Capacity
The passenger ferries market by capacity includes vessels with less than 150 seats, 150–400 seats, and more than 400 seats. Ferries with more than 400 seats dominate with a 44% share, serving dense urban routes and tourism hubs. The 150–400 segment holds 37%, balancing affordability and flexibility for regional operators. Ferries with less than 150 seats contribute 19%, mainly serving smaller coastal or island communities. It reflects varying regional demand patterns.
- For instance, Balearia in Spain deployed its 390-passenger eco-efficient ferry Eleanor Roosevelt, powered by dual engines designed to cut emissions on Mediterranean routes.
By Technology
The passenger ferries market by technology is divided into conventional diesel-powered ferries, electric & hybrid ferries, and LNG-powered ferries. Conventional diesel ferries still command 55% share, though operators face emission regulation pressures. Electric and hybrid ferries account for 28%, expanding quickly with strong sustainability focus and government support. LNG-powered ferries represent 17%, gaining traction in environmentally sensitive routes. It underscores a gradual industry transition toward cleaner and more efficient propulsion systems worldwide.
Segments:
Based on Ferry
- Ro-pax (roll-on/roll-off passenger) ferries
- High-speed ferries
- Cruise ferries
Based on Capacity
- Less than 150
- 150 - 400
- More than 400
Based on Technology
- Conventional diesel-powered ferries
- Electric & hybrid ferries
- LNG powered ferries
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The passenger ferries market in North America holds 26% share, driven by strong demand for coastal and inter-island transport. The United States and Canada emphasize modernization of ferry fleets to meet environmental standards. It benefits from significant investments in hybrid and electric ferries across urban regions. High reliance on ferries in Alaska, Washington, and British Columbia sustains consistent ridership. Tourism growth also supports services in coastal and island destinations. Regulatory frameworks continue to encourage sustainable vessel adoption.
Europe
Europe accounts for 33% share of the passenger ferries market, making it the largest regional contributor. Countries like Greece, Italy, Norway, and the United Kingdom rely heavily on ferries for connectivity. It benefits from advanced port infrastructure and strong integration with tourism sectors. Europe leads in adoption of LNG, hybrid, and electric ferries due to strict emission regulations. Government support accelerates replacement of older fleets with sustainable alternatives. Tourism-driven traffic in the Mediterranean further strengthens demand across this region.
Asia-Pacific
Asia-Pacific represents 28% share of the passenger ferries market, supported by growing urbanization and expanding coastal economies. High demand in countries such as Japan, China, and Indonesia drives fleet expansion. It reflects both commuter-based services and international tourism. Governments invest in ferry terminals and modern fleets to reduce congestion in urban centers. Expanding middle-class populations prefer ferries for affordable leisure and travel. The region also witnesses rising interest in eco-friendly ferries to meet environmental commitments.
Latin America
Latin America holds 7% share of the passenger ferries market, driven by growing coastal tourism and inter-island transport. Countries such as Brazil, Mexico, and Chile are expanding ferry operations to enhance regional connectivity. It faces challenges from limited port infrastructure, but rising tourism encourages investments in fleet modernization. Operators explore hybrid solutions for sustainable growth. Government initiatives aim to improve accessibility across islands and coastal regions. The region shows steady growth potential in both passenger and tourism services.
Middle East & Africa
The passenger ferries market in the Middle East & Africa accounts for 6% share, supported by tourism, urban mobility, and island transport services. Gulf nations invest in ferry services to diversify transport and attract visitors. It benefits from government-backed infrastructure projects in coastal cities. Africa shows rising adoption in countries with significant island communities such as Tanzania and Kenya. Limited infrastructure remains a challenge, but growth prospects improve with tourism and urbanization. Fleet expansion continues to emerge gradually across both regions.
Key Player Analysis
- Jadrolinija
- Washington State Ferries
- Stena Line
- Irish Ferries
- Tallink Grupp
- P&O Ferries
- DFDS Seaways
- Minoan Lines
- BC Ferries
- Brittany Ferries
Competitive Analysis
The passenger ferries market is highly competitive with global and regional players focusing on fleet modernization, sustainability, and customer experience to strengthen market presence. Leading operators such as BC Ferries, Brittany Ferries, DFDS Seaways, Irish Ferries, Jadrolinija, Minoan Lines, P&O Ferries, Stena Line, Tallink Grupp, and Washington State Ferries emphasize investments in hybrid and electric propulsion systems to meet strict emission norms. It demonstrates steady innovation in vessel design, onboard amenities, and digital services to attract passengers across commuter and tourism segments. Strategic alliances, government partnerships, and route expansions enable operators to enhance capacity while maintaining compliance with environmental regulations. Competition also intensifies in regions with strong tourism demand, where companies differentiate through premium services, faster transit times, and integrated ticketing solutions. Sustainability initiatives, such as LNG-powered vessels and electrification, are reshaping competitive strategies, positioning operators to capture long-term growth opportunities. The market reflects a balance of established companies and emerging players focusing on cost efficiency, route accessibility, and passenger safety to secure competitive advantage.
Recent Developments
- In May 2025, BC Ferries welcomed the launch of another Island Class ferry built by Damen Shipyards Galati, the first of four battery-equipped diesel-hybrid vessels planned for fleet expansion.
- In June 2025, Maritime Partners, LLC completed refinancing for the hydrogen-powered passenger ferry "Sea Change," developed by SWITCH Maritime LLC. This deal supports SWITCH’s expansion to build next-generation zero-emission vessels for major U.S. markets like San Francisco and Seattle.
- In August 2025, Baleària will launch its third natural gas–powered fast ferry, Mercedes Pinto, from the Armón shipyard on September 19. The eco-efficient vessel will serve in 2026.
- In 2025, Brittany Ferries introduced two hybrid‑electric E‑Flexer vessels: Saint‑Malo and Guillaume de Normandie, both operating partially or fully on battery power.
Market Concentration & Characteristics
The passenger ferries market demonstrates moderate concentration, with a mix of global operators and strong regional players competing across commuter and tourism segments. Established companies such as BC Ferries, Stena Line, DFDS Seaways, Tallink Grupp, and P&O Ferries dominate key routes with large fleets and advanced infrastructure. It reflects high barriers to entry due to capital-intensive investments, regulatory compliance, and environmental standards. Operators are increasingly focusing on hybrid and electric propulsion, digital ticketing, and enhanced passenger services to remain competitive. Government support through subsidies, partnerships, and infrastructure development strengthens industry stability while encouraging sustainability. The market is characterized by diverse service models ranging from short-distance urban ferries to luxury cruise ferries, catering to both mass transit and premium travel demand. Strong emphasis on fleet modernization, safety compliance, and emission reduction underpins the competitive environment, positioning established players to retain dominance while offering scope for innovation-driven entrants to gain market presence.
Report Coverage
The research report offers an in-depth analysis based on Ferry, Capacity, Technology and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Passenger ferries will adopt electric and hybrid propulsion systems to reduce emissions and improve efficiency.
- Operators will expand routes connecting urban centers, islands, and coastal towns to meet rising mobility demand.
- Governments will increase investments in ferry terminals, docking facilities, and charging infrastructure for sustainable transport growth.
- Digital ticketing, mobile applications, and real-time scheduling will become standard to enhance passenger convenience and efficiency.
- Fleet modernization programs will replace aging vessels with advanced designs focused on safety, speed, and sustainability.
- Tourism-driven demand will support luxury ferries offering premium seating, onboard dining, entertainment, and cruise-like experiences.
- LNG-powered ferries will gain momentum in environmentally sensitive regions, complementing hybrid and battery-electric vessel adoption.
- Collaborations between governments and private operators will expand ferry networks and improve accessibility in emerging economies.
- Rising urban congestion will drive greater reliance on ferries as efficient alternatives to road transport.
- Advanced navigation systems and predictive maintenance technologies will improve operational efficiency and fleet reliability worldwide.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Tourism and Coastal Connectivity Demand
The expansion of global tourism and the need for efficient coastal transport are increasing reliance on passenger ferries as affordable and scenic travel options. Governments are expanding maritime routes to connect islands, coastal towns, and metropolitan hubs, driving sustained demand for ferry services.
Focus on Sustainable and Eco-Friendly Transportation
Stricter environmental regulations and public awareness of climate change are pushing operators to adopt electric, hybrid, and LNG-powered ferries. This shift positions ferries as a sustainable alternative to road and air travel, especially for short-distance routes.
Government Investments and Infrastructure Development
Significant public investments in port infrastructure, ferry terminals, and fleet modernization are improving service reliability and capacity. Subsidies and partnerships with private operators are enabling the upgrade of fleets and expansion of ferry networks.
Advancement in Technology and Passenger Experience
The adoption of digital ticketing, real-time scheduling, onboard connectivity, and luxury amenities is enhancing passenger convenience and satisfaction. Technological upgrades also improve operational efficiency, safety, and energy performance, making ferry travel more attractive.
Expansion of Ferry Networks in Emerging Economies
Rising urbanization and economic growth in Asia-Pacific, Latin America, and island nations are creating new opportunities for ferry operators. Governments are encouraging ferry adoption to ease urban congestion and improve regional connectivity, supporting market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Passenger ferries market, and what is its projected size in 2032?
Which Passenger ferries market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Passenger ferries market?
Who are the leading companies in the Passenger ferries market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Capacity
- 1.2.1 Less than 150
- 1.2.2 150 - 400
- 1.2.3 More than 400
- 1.3 By Ferry Type
- 1.3.1 Ro-pax (roll-on/roll-off passenger) ferries
- 1.3.2 High-speed ferries
- 1.3.3 Cruise ferries
- 1.4 By Technology
- 1.4.1 Conventional diesel-powered ferries
- 1.4.2 Electric & hybrid ferries
- 1.4.3 LNG powered ferries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,900 million → 2032: USD 3,734 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Passenger Ferries Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Passenger Ferries Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Passenger Ferries Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Passenger Ferries Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Passenger Ferries Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Passenger Ferries Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Passenger Ferries Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Passenger Ferries Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,900 million → 2032: USD 3,734 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Passenger Ferries Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Capacity - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Less than 150
- 12.3.7.2 150 - 400
- 12.3.7.3 More than 400
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Ferry Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Ro-pax (roll-on/roll-off passenger) ferries
- 12.4.7.2 High-speed ferries
- 12.4.7.3 Cruise ferries
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Conventional diesel-powered ferries
- 12.5.7.2 Electric & hybrid ferries
- 12.5.7.3 LNG powered ferries
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Passenger Ferries Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Passenger Ferries Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Passenger Ferries Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 BC Ferries
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Brittany Ferries
- 17.4 DFDS Seaways
- 17.5 Irish Ferries
- 17.6 Jadrolinija
- 17.7 Minoan Lines
- 17.8 P&O Ferries
- 17.9 Stena Line
- 17.10 Tallink Grupp
- 17.11 Washington State Ferries
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

