
Market Overview:
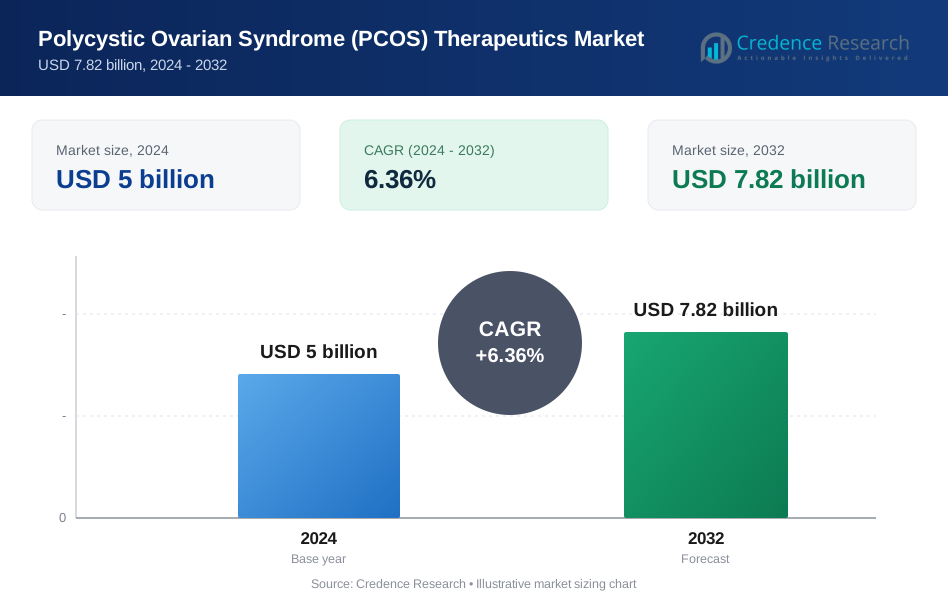
The Polycystic Ovarian Syndrome (PCOS) Therapeutics market was valued at USD 5 billion in 2024 and is expected to reach USD 7.82 billion by 2032, growing at a CAGR of 6.36% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Size 2024 | USD 5 billion |
| Polycystic Ovarian Syndrome (PCOS) Therapeutics Market, CAGR | 6.36% |
| Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Size 2032 | USD 7.82 billion |
The Polycystic Ovarian Syndrome (PCOS) therapeutics market is dominated by key players such as Abbott Laboratories, Bayer AG, Merck & Co., Inc., Sanofi S.A., Pfizer Inc., Novartis AG, Teva Pharmaceutical Industries Ltd., AstraZeneca plc, and Bristol Myers Squibb Company. These companies lead the market with a diverse range of treatments targeting hormonal imbalances, insulin resistance, and infertility associated with PCOS. North America holds the largest market share, accounting for approximately 40–45% due to its well-established healthcare infrastructure and high patient awareness. Europe follows with around 20–25% of the market share, while Asia Pacific is experiencing the fastest growth, currently holding about 15–20%. These regions are key focus areas for the top players, who are actively investing in research and expanding their product offerings to capture the increasing demand for effective PCOS treatments.

Market Insights
- The Polycystic Ovarian Syndrome (PCOS) therapeutics market is valued at USD 5 billion in 2024 and is expected to reach USD 7.82 billion by 2032, growing at a CAGR of 6.36%.
- The market is driven by the rising prevalence of PCOS, with increasing awareness of the condition leading to higher diagnosis rates and greater demand for effective treatments.
- Advancements in drug development are offering more personalized, targeted therapies that address the specific hormonal and metabolic imbalances associated with PCOS, driving the market forward.
- Key trends include a shift toward personalized medicine and the rapid growth of online pharmacies and telemedicine, providing new opportunities for delivering PCOS treatments more effectively and conveniently.
- North America dominates the market, accounting for a45% of the market share, followed by Europe at 25%, and Asia Pacific with the fastest growth rate, holding 20% share.
Market Segmentation Analysis
By Drug Class
The Polycystic Ovarian Syndrome (PCOS) therapeutics market is dominated by the Oral Contraceptives segment, which holds 40% of the market share. This sub-segment is driven by the increasing awareness of the benefits of oral contraceptives in managing symptoms such as irregular periods and excessive hair growth. Oral contraceptives are widely prescribed due to their effectiveness in regulating hormones, making them a popular choice among patients and healthcare providers. The growing adoption of combination oral contraceptives, which address both contraceptive and therapeutic needs, further boosts their dominance in the market.
- For instance, combined oral contraceptives (COCs) containing low-dose ethinyl estradiol and antiandrogenic progestins such as norgestimate or desogestrel are preferred choices, as they effectively reduce androgen levels and improve menstrual regularity.
By Route of Administration
The Oral route of administration leads the market in the PCOS therapeutics segment, capturing 55% of the market share. Oral medications are preferred by patients due to their ease of use and convenience. The widespread acceptance of oral contraceptives and insulin sensitizers as oral medications has fueled the growth of this sub-segment. Additionally, the preference for non-invasive treatments and the continuous development of oral therapies with improved bioavailability contribute to the sustained dominance of oral medications in treating PCOS.
- For instance, Clomiphene citrate, an oral ovulation stimulant, is available from companies like Cipla (brand name Fertomid) and Gynogen (brand name GENCURE 50). These brands are frequently prescribed to induce ovulation in PCOS-related infertility.
By Distribution Channel
Among the various distribution channels, Retail Pharmacies hold the largest market share, 50%. This is primarily due to the accessibility and widespread presence of retail pharmacies, allowing consumers to easily obtain their prescribed medications. The convenience and availability of a wide range of therapeutics at competitive prices in retail pharmacies drive their dominance. Additionally, retail pharmacies benefit from higher consumer footfall, increasing sales volume and contributing to the overall growth of the market. Online pharmacies are also growing rapidly, driven by convenience and increasing e-commerce adoption.
Key Growth Drivers
Rising Prevalence of PCOS
One of the primary drivers for the growth of the Polycystic Ovarian Syndrome (PCOS) therapeutics market is the increasing prevalence of PCOS worldwide. PCOS affects a significant proportion of women of reproductive age, with estimates suggesting it impacts around 10% of women globally. This rising prevalence has heightened awareness and demand for effective treatments. As the understanding of PCOS expands, more women are seeking medical advice and treatments to manage the condition’s symptoms, such as irregular periods, infertility, and excessive hair growth. The growing awareness among healthcare professionals, coupled with improved diagnostic tools, has led to an increase in the number of diagnoses and, consequently, a greater demand for therapeutics.
- For instance, a study of women across major Chinese provinces that used the Rotterdam criteria to diagnose Polycystic Ovary Syndrome (PCOS) found that the prevalence of the condition rose from 5.6% in 2010 to 7.8% in a subsequent survey in 2020.
Advancements in Drug Development
Advancements in drug development for PCOS therapeutics are fueling market growth by offering more targeted, effective, and personalized treatments. Over the past few years, new drug classes, such as insulin sensitizers, anti-androgens, and ovulation inducers, have gained approval, improving treatment outcomes for women with PCOS. The ongoing research into hormonal therapies, lifestyle modifications, and combination therapies has provided more options for treating the diverse symptoms of PCOS. Moreover, the development of drugs that specifically address underlying issues like insulin resistance and hormonal imbalances is expected to meet the evolving needs of patients.
- For instance, an anti-androgen intervention using Finasteride (5 mg daily) alone or in combination with metformin was compared against metformin alone in adult women with PCOS, over 12 months, showing substantive androgen level reductions.
Increasing Healthcare Awareness and Accessibility
The rising awareness of PCOS among women and healthcare providers is a key driver of growth in the PCOS therapeutics market. Increased awareness campaigns and initiatives by healthcare organizations, coupled with online information and support networks, have contributed significantly to the recognition of PCOS as a common yet underdiagnosed condition. Additionally, the expanding access to healthcare services, especially in emerging economies, has led to more women seeking treatment for PCOS. With improvements in healthcare infrastructure, diagnostic tools, and treatment availability, women are more likely to visit healthcare providers for PCOS diagnosis and management.
Key Trends & Opportunities
Shift Toward Personalized Medicine
The increasing trend toward personalized medicine presents a significant opportunity in the PCOS therapeutics market. Personalized approaches allow for treatment regimens that are tailored to the unique needs of each patient, considering factors such as age, medical history, and specific symptoms. For instance, therapies that target insulin resistance or androgen excess can be customized based on individual patient profiles. As genetic research and biomarker identification progress, there will be a surge in targeted therapies that can provide more effective and less invasive treatments. This trend towards personalized medicine is expected to improve treatment outcomes, minimize side effects, and foster patient satisfaction, creating growth opportunities for pharmaceutical companies to develop specialized PCOS therapies.
- For instance, research identified two glycolysis‑related gene biomarkers, TXNIP and TGFBI, which were significantly upregulated in granulosa cells from PCOS patients; TGFBI had 14 high‑confidence m6A modification sites, TXNIP had one.
Growth of Online Pharmacies and Telemedicine
The growth of online pharmacies and telemedicine is a key opportunity for the PCOS therapeutics market. The increasing adoption of telemedicine has revolutionized healthcare delivery, making it more convenient for patients to consult doctors, receive prescriptions, and access medications remotely. This trend has gained further momentum due to the COVID-19 pandemic, which accelerated the adoption of telehealth services. As a result, online pharmacies that offer PCOS medications are benefiting from a broader customer base, particularly in regions where traditional pharmacy access may be limited. This trend also allows for more discreet and convenient access to PCOS treatments, encouraging more women to seek therapy. The convenience of home delivery of prescriptions and medications is expected to drive growth in the online pharmacy segment of the market.
- For instance, Teladoc Health offers comprehensive care for PCOS including diagnosis and medication support, making it easier for women to access specialist care remotely through telemedicine consultations.
Key Challenges
Side Effects and Safety Concerns
One of the primary challenges in the PCOS therapeutics market is the side effects and safety concerns associated with various treatments. Medications such as oral contraceptives, anti-androgens, and insulin sensitizers may cause adverse effects like weight gain, nausea, and mood changes, which can deter patients from adhering to their prescribed therapies. The fear of long-term side effects, such as the risk of blood clots with oral contraceptives or liver damage with certain insulin sensitizers, may also discourage some women from seeking treatment. Healthcare providers need to address these concerns and work with patients to monitor side effects and adjust treatment plans accordingly. The challenge of ensuring patient compliance while balancing efficacy with safety continues to hinder the market’s growth potential.
High Treatment Costs
The high cost of PCOS treatments remains a significant challenge for many patients, particularly in developing regions. While pharmaceutical companies have introduced new treatments for PCOS, the prices of medications, diagnostic tests, and consultations can be prohibitively expensive for a large segment of the population. In countries with limited insurance coverage or healthcare infrastructure, out-of-pocket costs can make it difficult for women to access the necessary care. This pricing challenge restricts the potential market size and limits the ability of many women to afford ongoing treatment. Affordable solutions and government-backed healthcare initiatives will be essential to overcoming this barrier and ensuring that women worldwide have access to effective PCOS therapeutics.
Regional Analysis
North America
The North American region dominates the Polycystic Ovarian Syndrome (PCOS) therapeutics market, capturing 45% of global market share in 2024–2025. This leadership stems from well-established healthcare infrastructure, high awareness of PCOS among women of reproductive age, and substantial research investment by major pharmaceutical companies. Early diagnosis practices and accessible new therapies further reinforce demand. The considerable prevalence of PCOS in the region, combined with advanced patient monitoring and reimbursement mechanisms, ensures that North America will continue to lead market revenues in the foreseeable forecast period.
Europe
Europe holds a sizeable portion of the PCOS therapeutics market, estimated at 25% of global share. Strong public health initiatives, increasing diagnosis rates, and growing attention to women’s metabolic and reproductive health support the region’s market growth. The presence of established pharmaceutical manufacturers and favorable reimbursement policies for PCOS-related therapies also contribute. However, compared to North America, uptake is moderated by varied healthcare access across countries and differences in insurance coverage, making Europe a significant but slower-growing region in the global landscape.
Asia Pacific
In the Asia Pacific region, the PCOS therapeutics market is emerging strongly, with a current share of 20%, and the fastest anticipated growth rate among all regions. Earlier under-diagnosis is giving way to increasing awareness, improved healthcare infrastructure, and focused women’s health initiatives in countries such as India, China and Australia. These factors are driving higher adoption of PCOS treatments. Rising urbanization, lifestyle changes and increasing prevalence of metabolic disturbances in women further propel demand. The region offers significant opportunity for both global and regional players to expand their market presence.
Latin America
Latin America accounts for 10% of the global PCOS therapeutics market. Growth in this region is supported by increasing awareness of PCOS, efforts to strengthen women’s health services, and the gradual expansion of pharmaceutical distribution networks. Despite this progress, the market faces constraints in terms of varying access to care, reimbursement inconsistencies, and lower per-capita healthcare spending compared with developed regions. Nonetheless, the region presents a steady growth opportunity as awareness campaigns and access to diagnosis and treatment improve.
Middle East & Africa
The Middle East & Africa region represents the smallest share of the PCOS therapeutics market, estimated at 7% globally. Market growth is driven by a rising incidence of PCOS, a growing young female population, and governmental initiatives to enhance women’s healthcare access. However, challenges such as limited diagnostic infrastructure, variable reimbursement frameworks, and lower awareness of PCOS hinder faster adoption of therapies. As healthcare systems in the region improve and awareness increases, the market is poised for gradual expansion.
Market Segmentations
By Drug Class
- Oral Contraceptives
- Insulin Sensitizers
- Anti-Androgens
- Ovulation Inducers
By Route of Administration
- Oral
- Injectable
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the PCOS therapeutics market features a blend of major multinational pharmaceutical companies and specialized women's-health firms strategically advancing their offerings. Players such as Abbott Laboratories, Bayer AG, Merck & Co., Inc., Sanofi S.A., Pfizer Inc., Novartis AG, Teva Pharmaceutical Industries Ltd., AstraZeneca plc, and Bristol Myers Squibb Company consistently lead in research, development, and commercialization of PCOS-relevant treatments. These companies invest heavily in R&D to address hormonal, metabolic, and fertility-related aspects of the condition and often form alliances or licensing deals to expand pipelines and geographic reach. Competitive advantage hinges on novel mechanism-based therapies, differentiation through drug classes (such as insulin sensitisers or anti-androgens), and strong global marketing networks. As a result, market players aim to capture early adopter segments and solidify their positions through lifecycle management, generic launches, and emerging-market expansion.
Key Player Analysis
- Teva Pharmaceutical Industries Ltd.
- Pfizer Inc.
- Novartis AG
- Ferring Pharmaceuticals
- AstraZeneca plc
- Merck & Co., Inc.
- Sanofi S.A.
- Bayer AG
- Bristol Myers Squibb Company
- Abbott Laboratories
Recent Developments
- In 2025, Jagat Pharma introduced “PCOS Capsules For Her”, an Ayurvedic supplement formulated to help manage PCOS symptoms.
- In August 2024, Aurelle Health (via Balaxi Pharmaceuticals) launched a women’s hormonal health brand in India, with product lines that include support for PCOS‑related hormone issues.
- In August 2023, BioSyent Inc. launched Inofolic®, a soft‑gel capsule combining myo‑inositol and folic acid, specifically for women with PCOS
Report Coverage
The research report offers an in-depth analysis based on Drug Class, Route of Administration, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The PCOS therapeutics market is expected to continue expanding as awareness and diagnoses of the condition increase globally.
- Advances in personalized medicine will drive the development of more targeted treatments, enhancing the effectiveness of therapies for individual patients.
- New drug classes targeting specific PCOS symptoms, such as insulin resistance and androgen excess, will emerge, offering more tailored solutions.
- The increasing prevalence of PCOS, particularly in emerging economies, will fuel demand for effective therapeutic options and drive market growth.
- The rise of digital health tools, including telemedicine and online pharmacies, will improve patient access to PCOS treatments, particularly in remote areas.
- Enhanced drug delivery systems, such as novel oral and injectable forms, will improve patient adherence and outcomes in managing PCOS.
- Growing healthcare infrastructure and better access to healthcare services in developing regions will create new opportunities for market expansion.
- Pharmaceutical companies will continue to invest in R&D to discover more innovative treatments, creating a competitive environment in the market.
- Partnerships and collaborations between pharmaceutical companies and research institutions will accelerate the development and availability of new PCOS therapies.
- Regulatory advancements and favorable reimbursement policies in various regions will make PCOS treatments more affordable and accessible to a wider patient population.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Polycystic Ovarian Syndrome PCOS Therapeutics Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Polycystic Ovarian Syndrome PCOS Therapeutics Market projected to grow between 2025 and 2032?
Which Polycystic Ovarian Syndrome PCOS Therapeutics Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Polycystic Ovarian Syndrome PCOS Therapeutics Market?
Who are the leading companies in the Polycystic Ovarian Syndrome PCOS Therapeutics Market?
Which region commanded the largest share of the Polycystic Ovarian Syndrome PCOS Therapeutics Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Polycystic Ovarian Syndrome (PCOS) Therapeutics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5 billion → 2032: USD 7.82 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Drivers
- 3.3 Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Restraints & Challenges
- 3.4 Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Polycystic Ovarian Syndrome (PCOS) Therapeutics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Polycystic Ovarian Syndrome (PCOS) Therapeutics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Polycystic Ovarian Syndrome (PCOS) Therapeutics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Polycystic Ovarian Syndrome (PCOS) Therapeutics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Polycystic Ovarian Syndrome (PCOS) Therapeutics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Polycystic Ovarian Syndrome (PCOS) Therapeutics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Polycystic Ovarian Syndrome (PCOS) Therapeutics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Polycystic Ovarian Syndrome (PCOS) Therapeutics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Polycystic Ovarian Syndrome (PCOS) Therapeutics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Polycystic Ovarian Syndrome (PCOS) Therapeutics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Polycystic Ovarian Syndrome (PCOS) Therapeutics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Polycystic Ovarian Syndrome (PCOS) Therapeutics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Polycystic Ovarian Syndrome (PCOS) Therapeutics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Polycystic Ovarian Syndrome (PCOS) Therapeutics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Polycystic Ovarian Syndrome (PCOS) Therapeutics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Polycystic Ovarian Syndrome (PCOS) Therapeutics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
