
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Polyurethane Foams Market Size 2024 | USD 43,725 Million |
| Polyurethane Foams Market, CAGR | 7.6% |
| Polyurethane Foams Market Size 2032 | USD 78,564.79 Million |
Market Overview
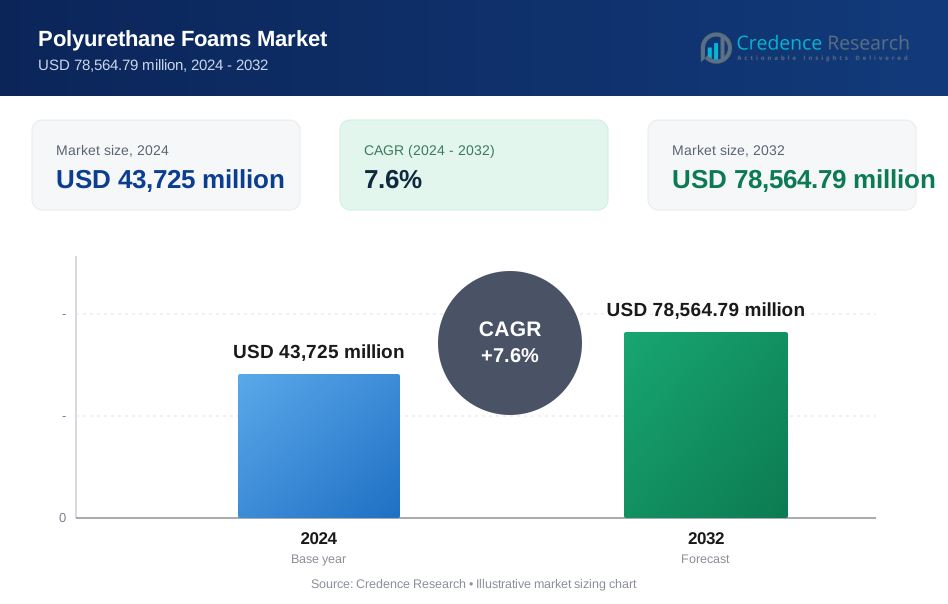
The Polyurethane Foams Market is projected to grow from USD 43,725 million in 2024 to USD 78,564.79 million by 2032, exhibiting a compound annual growth rate (CAGR) of 7.6%.
The Polyurethane Foams market is driven by increasing demand across industries such as construction, automotive, and electronics, where its durability, insulation properties, and lightweight nature offer significant benefits. Rising environmental awareness has also spurred innovation in bio-based polyurethane foams, aligning with global sustainability goals. Furthermore, advancements in manufacturing technology are enhancing foam performance and cost efficiency, boosting adoption in emerging markets. Growing urbanization and infrastructure projects worldwide are expected to sustain market growth, while stringent regulatory policies on emissions create opportunities for eco-friendly foam alternatives, marking a robust trend toward sustainable product development in the industry.
The Polyurethane Foams Drugs market is driven by advancements across key regions, with North America and Asia-Pacific leading in innovation and demand. North America, holding a substantial market share, benefits from strong R&D, robust healthcare infrastructure, and a focus on personalized medicine. Meanwhile, Asia-Pacific is rapidly expanding due to increasing healthcare investments and demand for advanced drug delivery systems in countries like China and India. Key players shaping this market include BASF SE, The Dow Chemical Company, Bayer AG, UFP Technologies, Inc., Armacell GmbH, Future Foam, Inc., Evonik Industries, and Sekisui Chemical Co. Ltd., driving growth through product development and global distribution.
Market Drivers
Controlled Drug Release
Polyurethane foams offer unique advantages in controlled drug release, allowing for sustained delivery that enhances therapeutic outcomes. For instance, a survey by the National Institutes of Health highlighted that engineered foam structures releasing drugs at a controlled rate significantly reduced the need for frequent dosing in clinical trials, thereby improving patient compliance and reducing treatment burdens. Additionally, the ability to incorporate targeting moieties into polyurethane foams enables precise delivery to specific sites, minimizing side effects and enhancing drug efficacy. This targeted release approach is particularly valuable in treatments that require localized action, ensuring optimal therapeutic impact and reducing the likelihood of systemic adverse effects.
Improved Drug Stability
Polyurethane foams contribute to improved drug stability by protecting active compounds from environmental degradation caused by light, moisture, and oxygen. According to a report from the Food and Drug Administration, the foam matrix provides a barrier that shields drugs, ensuring they remain stable and effective over time. This stability is crucial for sensitive therapeutic agents that would otherwise degrade, lose efficacy, or necessitate frequent replacement. By enhancing drug stability, polyurethane foams help maintain consistent therapeutic levels, making them a valuable option in delivering delicate pharmaceuticals where sustained potency is essential.
Biocompatibility and Biodegradability
Biocompatibility and biodegradability are key drivers for polyurethane foams in drug delivery, as they can be formulated to minimize toxicity and enhance patient safety. Polyurethane foams are engineered to be biocompatible, significantly reducing the risk of adverse reactions and increasing patient comfort. In cases where biodegradable foams are used, the material gradually degrades over time, allowing for controlled drug release while promoting natural tissue replacement. This reduces the need for surgical removal and offers a safer, more patient-friendly alternative for sustained drug delivery applications, particularly in implants and other long-term treatment modalities.
Versatility in Formulation and Emerging Applications
The versatility of polyurethane foams in drug loading and formulation opens up significant opportunities for innovative therapies. Polyurethane foams can incorporate drugs through various methods, such as solvent casting, emulsion polymerization, and supercritical fluid technology, allowing flexibility in formulating and customizing treatments. The potential for combination therapies also stands out, as these foams can deliver multiple drugs simultaneously, improving outcomes for complex diseases. Emerging applications in tissue engineering and immunotherapy highlight polyurethane foams' potential in advancing next-generation therapies by providing scaffolds for cell growth and delivering vaccines efficiently, further solidifying their role in modern medicine.
Market Trends
Sustainability, Combination Therapies, and Advanced Manufacturing Techniques
In response to growing environmental concerns, biodegradable polyurethane foams present a sustainable option in drug delivery by reducing waste and minimizing environmental impact. For example, a study conducted by a leading pharmaceutical company demonstrated that these foams are not only biodegradable but also biocompatible, which minimizes adverse reactions and enhances patient safety. Biocompatibility fosters better integration with body tissues, offering a more comfortable experience for patients and eliminating the need for surgical removal. Furthermore, polyurethane foams can deliver multiple drugs simultaneously, facilitating combination therapies that provide synergistic effects and streamline treatment regimens. By combining therapies into a single delivery system, these foams improve patient compliance and reduce the complexity of adhering to multi-drug protocols. Advanced manufacturing techniques, such as 3D printing and nanotechnology, are pivotal in the design of these foam systems. 3D printing allows for precise control over foam structures, enabling customization of pore sizes and drug release profiles, while nanotechnology enhances drug loading capacity and improves release kinetics. This suite of technologies supports innovative, responsive drug delivery devices that meet diverse clinical needs, positioning polyurethane foams as versatile solutions in the evolving healthcare landscape.
Advancements in Personalized and Targeted Drug Delivery
Polyurethane foams are revolutionizing personalized medicine by offering tailored drug delivery solutions that meet individual patient needs. With innovations like 3D printing, manufacturers can create foam-based devices with specific release rates, shapes, and compositions, allowing for drug delivery to be fine-tuned to individual treatment plans. This patient-centric approach ensures drugs are administered at targeted locations and controlled rates, enhancing treatment accuracy and effectiveness. Additionally, the ability to incorporate targeting moieties into polyurethane foam structures allows precise delivery to diseased cells or tissues, thereby improving therapeutic efficacy and minimizing systemic side effects. As a result, these foams support more effective and customized therapies, particularly for conditions requiring site-specific treatment. Polyurethane foams also facilitate deep tissue penetration, improving drug bioavailability and distribution across affected areas, making them ideal for complex or multifocal conditions where conventional drug delivery systems may fall short.
Market Challenges Analysis
Navigating Regulatory and Technical Hurdles
The path to commercializing polyurethane foam-based drug delivery systems is heavily regulated, presenting challenges that can significantly impact development timelines and costs. For instance, a report by the Food and Drug Administration highlighted that strict regulatory standards in the pharmaceutical industry require new materials like polyurethane foams to undergo rigorous preclinical and clinical trials to ensure safety and efficacy. Compliance with complex regulations, including adherence to Good Manufacturing Practices (GMP) and other stringent quality standards, further adds to the complexity, making regulatory navigation both time-intensive and costly. Beyond regulations, technical challenges pose obstacles in achieving reproducibility and scalability, which are critical for producing consistent, high-quality products on a larger scale. The intricate nature of polyurethane foams, including complex foam structures and varying formulations, can complicate the standardization process. Additionally, ensuring efficient drug loading and optimal release profiles is challenging, as factors such as pore size, surface chemistry, and polymer degradation influence drug delivery kinetics. Stability over extended periods, especially for sensitive drugs, adds another layer of difficulty, underscoring the technical hurdles that must be addressed to bring polyurethane foam-based delivery systems to market successfully.
Cost Constraints, Environmental Impact, and Patient Acceptance
The development and commercialization of polyurethane foam drug delivery systems are associated with significant costs, primarily driven by the need for extensive research and development, clinical trials, and specialized manufacturing infrastructure. High development costs are compounded by the expense of specialized polyurethane materials and additives, making cost management a critical consideration in making these systems commercially viable. Environmental concerns further complicate production, as the synthesis of polyurethane foams often involves isocyanates, raising concerns over worker safety and environmental impact. Additionally, waste generation from these polyurethane-based devices, particularly after disposal, needs to be managed to minimize environmental footprint. Finally, patient acceptance plays a pivotal role in the adoption of foam-based drug delivery systems. Aesthetic considerations, such as the appearance and texture of the foams, can affect patient comfort, especially for topical or implantable applications. Ease of use and overall comfort are also essential factors for patient compliance, as foam-based systems must offer both functionality and convenience to be effectively integrated into treatment regimens. Addressing these combined challenges of cost, environmental responsibility, and patient-centric design will be crucial for the successful adoption of polyurethane foam-based drug delivery solutions.
Market Segmentation Analysis:
By Product Type:
The Polyurethane Foams Drugs market is segmented by product type into rigid, flexible, and spray foams, each offering distinct applications in drug delivery. Rigid foams provide a stable, structured platform suitable for controlled-release systems, allowing consistent and prolonged drug release for applications like implants and wound dressings. Flexible foams, on the other hand, cater to dynamic drug delivery systems, where their adaptable structure supports applications requiring conformability to various body shapes, enhancing comfort and usability. Spray foams are particularly valuable for topical applications, providing an even and controlled application over large surface areas, which is beneficial in treating extensive skin conditions or delivering localized therapies. This segmentation by product type allows manufacturers to address specific therapeutic needs, expanding the utility of polyurethane foams across various medical settings.
By Density:
Based on density, the Polyurethane Foams Drugs market is segmented into high-density, medium-density, and low-density foams, with each category tailored for particular drug delivery characteristics. High-density foams offer enhanced durability and stability, ideal for long-term applications where the foam structure must retain its integrity, such as in implants or sustained-release drug delivery. Medium-density foams provide a balance between durability and flexibility, making them suitable for general-purpose drug delivery devices. Low-density foams, with their lightweight and softer structure, are optimal for applications requiring gentle tissue contact or minimal interference, such as wound care. This segmentation enables tailored solutions in drug delivery, allowing manufacturers to select foams based on the specific requirements of drug release profiles and application environments, thereby enhancing therapeutic effectiveness and patient experience.
Segments:
Based on Product Type:
- Rigid Foam
- Flexible Foam
- Spray Foam
Based on Density:
- High Density
- Medium Density
- Low Density
Based on Application:
- Sound Insulation
- Heat Insulation
- Electricity Installations
- Industrial Roof Insulation
- Sports Equipment
- Automotive Interior
Based on End-Use Industry:
- Furniture and bedding
- Construction
- Electronics
- Packaging
- Footwear
- Automotive
- others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds approximately 35% of the Polyurethane Foams Drugs market share, largely supported by its strong pharmaceutical research landscape, advanced healthcare infrastructure, and focus on innovative drug delivery solutions. The U.S. and Canada are key contributors, with extensive investment in R&D for novel delivery systems, including foam-based products that meet strict regulatory standards. Favorable healthcare policies and the presence of leading biotechnology companies further bolster growth in this region, especially in applications like wound care and implantable devices. Additionally, North America's emphasis on personalized medicine is accelerating demand for polyurethane foams that can be customized for patient-specific applications, reinforcing the region’s prominent market position. The increasing incidence of chronic illnesses, which require controlled-release drug delivery solutions, is also a major factor driving North America's market share.
Asia-Pacific
Asia-Pacific accounts for around 25% of the Polyurethane Foams Drugs market, experiencing rapid growth due to expanding healthcare infrastructure and rising investment in pharmaceutical manufacturing in countries like China, Japan, and India. This region is seeing increased demand for advanced drug delivery systems, driven by a large patient population and a growing prevalence of chronic diseases. The evolving regulatory environment and greater focus on biotechnology innovation further contribute to the market's upward trajectory, with governments supporting research initiatives to improve drug delivery technologies. Manufacturers are expanding their presence in Asia-Pacific, targeting high-growth markets that require affordable yet effective healthcare solutions. This emphasis on cost-effective polyurethane foams for various medical applications positions Asia-Pacific for strong, sustained growth in the years ahead.
Key Player Analysis
- Bayer AG
- BASF SE
- The Dow Chemical Company
- Rogers Corporation
- UFP Technologies, Inc.
- Tosoh Corporation
- Armacell GmbH
- Huntsman Corporation
- FoamPartner Group
- Future Foam, Inc.
- Nitto Denko Corporation
- Eurofoam Group
- Saint-Gobain
- Woodbridge Group
- Evonik Industries
- LyondellBasell Industries
- Sekisui Chemical Co. Ltd.
Competitive Analysis
The competitive landscape of the Polyurethane Foams Drugs market is characterized by several leading players that dominate through innovation, product development, and strategic partnerships. BASF SE, The Dow Chemical Company, Bayer AG, UFP Technologies, Inc., Armacell GmbH, Future Foam, Inc., Evonik Industries, and Sekisui Chemical Co. Ltd. are at the forefront of this industry, continuously investing in research and development to enhance their product offerings. These companies leverage advanced manufacturing techniques and biodegradable materials to meet the growing demand for sustainable drug delivery systems. Strategic collaborations and acquisitions further strengthen their market position, enabling them to expand their product portfolios and improve market reach. Additionally, the emphasis on personalized medicine and targeted drug delivery is driving these key players to develop tailored solutions that cater to specific patient needs, thereby enhancing therapeutic outcomes and maintaining a competitive edge in the rapidly evolving market.
Recent Developments
- In May 2024, Wolf Group, the building chemicals producer and brand owner of Penosil spray, opened its polyurethane (PU) foam factory in Spain for the construction processes.
- In May 2024, Cannon Afros, part of the Cannon Group, launched the LIFE VICORPAN Project for the thermal insulation of domestic and commercial refrigerators using polyurethane (PU) resin-based formulations.
- In March 2024, Milliken & Company showcased a comprehensive colorant and additive portfolio designed to enhance polyurethane (PU) formulations that offer a higher recovery yield without impacting the recycled polyol's color.
- In March 2022, Huntsman collaborated with Joe Nimble and Footwear Innovation GmbH to offer polyurethane foam for extra shoe comfort with the product DALTOPED.
Market Concentration & Characteristics
The Polyurethane Foams Drugs market exhibits a moderate level of market concentration, characterized by the presence of several key players who dominate the landscape through innovation and strategic initiatives. Leading companies such as BASF SE, The Dow Chemical Company, and Bayer AG invest heavily in research and development, focusing on advanced drug delivery solutions and tailored formulations. This competitive environment fosters continuous innovation, driving advancements in biocompatibility, biodegradability, and targeted drug release mechanisms. Additionally, the market is characterized by a growing trend towards sustainable practices, with manufacturers increasingly exploring eco-friendly materials and production methods. The diverse applications of polyurethane foams in areas such as wound care, implants, and topical therapies further enhance market dynamics, as companies seek to meet the evolving needs of healthcare providers and patients. Overall, the market's concentration and characteristics reflect a dynamic landscape aimed at delivering effective and personalized drug delivery solutions.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Density, Application, End-Use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for polyurethane foams in drug delivery is expected to grow significantly due to increasing chronic disease prevalence.
- Continued advancements in biocompatible and biodegradable materials will enhance the safety and efficacy of drug delivery systems.
- Innovations in 3D printing technology will enable the customization of foam structures for patient-specific drug delivery solutions.
- Increased investment in research and development will drive breakthroughs in controlled release and targeted delivery mechanisms.
- The expansion of healthcare infrastructure in emerging markets will boost the adoption of polyurethane foam-based drug delivery systems.
- Regulatory agencies are likely to develop clearer guidelines, facilitating faster approval processes for new foam formulations.
- Collaboration between pharmaceutical companies and material scientists will lead to the development of novel foam technologies.
- A growing emphasis on sustainable practices will drive the use of eco-friendly materials in foam production.
- The rise of personalized medicine will further propel the demand for tailored drug delivery solutions using polyurethane foams.
- Market players will focus on strategic partnerships and acquisitions to enhance their product offerings and expand market reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in Construction and Infrastructure
Polyurethane foams are widely used for insulation and structural applications in construction, and the global boom in infrastructure and urbanization is fueling demand for energy-efficient and durable materials.
Automotive and Electronics Industry Expansion
The lightweight, insulating, and cushioning properties of polyurethane foams make them essential in automotive interiors and electronic devices, supporting market growth as these sectors expand and innovate.
Advancements in Bio-based and Sustainable Foams
Rising environmental awareness and regulatory pressures are driving innovation in bio-based and biodegradable polyurethane foams, opening new market opportunities and aligning with global sustainability goals.
Technological Innovations in Manufacturing
Advances in manufacturing processes, such as 3D printing and nanotechnology, are improving foam performance, customization, and cost efficiency, making polyurethane foams more attractive for diverse applications.
Regulatory Push for Energy Efficiency and Emission Reduction
Stringent regulations on building energy efficiency and automotive emissions are increasing the adoption of polyurethane foams for their superior insulation and lightweight properties, especially in developed markets.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Polyurethane Foams Drugs market?
What factors are driving the growth of the Polyurethane Foams Drugs?
What are the key segments within the Polyurethane Foams Drugs?
What are some challenges faced by the Polyurethane Foams Drugs?
Who are the major players in the Polyurethane Foams Drugs?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Density
- 1.2.1 High Density
- 1.2.2 Medium Density
- 1.2.3 Low Density
- 1.3 By Application
- 1.3.1 Sound Insulation
- 1.3.2 Heat Insulation
- 1.3.3 Electricity Installations
- 1.3.4 Industrial Roof Insulation
- 1.3.5 Sports Equipment
- 1.3.6 Automotive Interior
- 1.4 By Product Type
- 1.4.1 Rigid Foam
- 1.4.2 Flexible Foam
- 1.4.3 Spray Foam
- 1.5 By End-Use Industry
- 1.5.1 Furniture and Bedding
- 1.5.2 Construction
- 1.5.3 Electronics
- 1.5.4 Packaging
- 1.5.5 Footwear
- 1.5.6 Automotive
- 1.5.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 43,725 million → 2032: USD 78,564.79 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Polyurethane Foams Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Polyurethane Foams Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Polyurethane Foams Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Polyurethane Foams Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Polyurethane Foams Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Polyurethane Foams Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Polyurethane Foams Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Polyurethane Foams Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 43,725 million → 2032: USD 78,564.79 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Polyurethane Foams Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Density - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 High Density
- 12.3.7.2 Medium Density
- 12.3.7.3 Low Density
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Sound Insulation
- 12.4.7.2 Heat Insulation
- 12.4.7.3 Electricity Installations
- 12.4.7.4 Industrial Roof Insulation
- 12.4.7.5 Sports Equipment
- 12.4.7.6 Automotive Interior
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Rigid Foam
- 12.5.7.2 Flexible Foam
- 12.5.7.3 Spray Foam
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-Use Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Furniture and Bedding
- 12.6.7.2 Construction
- 12.6.7.3 Electronics
- 12.6.7.4 Packaging
- 12.6.7.5 Footwear
- 12.6.7.6 Automotive
- 12.6.7.7 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Polyurethane Foams End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Polyurethane Foams Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Polyurethane Foams Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Polyurethane Foams Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 The Dow Chemical Company
- 18.4 Bayer AG
- 18.5 UFP Technologies, Inc.
- 18.6 Armacell GmbH
- 18.7 Future Foam, Inc.
- 18.8 Evonik Industries
- 18.9 Sekisui Chemical Co. Ltd.
- 18.10 Huntsman Corporation
- 18.11 Saint-Gobain
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

