
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Post-Traumatic Stress Disorder (PTSD) therapeutics Market Size 2024 | USD 5,395 million |
| Post-Traumatic Stress Disorder (PTSD) therapeutics Market, CAGR | 7% |
| Post-Traumatic Stress Disorder (PTSD) therapeutics Market Size 2032 | USD 9,269.614 million |
Market Overview
The market for Post-Traumatic Stress Disorder (PTSD) therapeutics is projected to grow from USD 5,395 million in 2024 to USD 9,269.614 million by 2032, reflecting a robust annual growth rate of 7%.The Post-Traumatic Stress Disorder (PTSD) therapeutics market is driven by increasing awareness of mental health issues and the growing prevalence of PTSD among various populations, including veterans and first responders. Advances in therapeutic options, such as novel pharmacological treatments and innovative psychotherapies, further propel market growth. Additionally, government initiatives aimed at improving mental health services and destigmatizing psychological disorders contribute to expanding access to care. The rising focus on personalized medicine and integrated treatment approaches enhances patient outcomes, positioning the PTSD therapeutics market for sustained expansion in the coming years.
The geographical analysis of the Post-Traumatic Stress Disorder (PTSD) therapeutics market reveals significant growth potential across North America and Europe, driven by rising awareness and supportive healthcare policies. Key players such as Jazz Pharmaceuticals, Pfizer Inc., and Merck KGaA dominate the market by leveraging innovative research and development. In addition, companies like Otsuka Pharmaceutical Development & Commercialization, Inc. and GlaxoSmithKline plc are pivotal in advancing therapeutic options. As mental health initiatives gain momentum globally, these key players are well-positioned to meet the increasing demand for effective PTSD treatments across diverse regions.
Market Drivers
Increasing Prevalence of PTSD
The rise in natural disasters, conflicts, and acts of violence has led to an increase in individuals experiencing traumatic events, contributing significantly to the prevalence of Post-Traumatic Stress Disorder (PTSD). For instance, the World Health Organization (WHO) reports that approximately 3.9% of the global population has experienced PTSD at some point in their lives. Greater recognition and understanding of PTSD and its symptoms have encouraged more individuals to seek help, thus driving demand for effective treatments. This heightened awareness plays a crucial role in reducing the barriers to treatment, enabling those affected to pursue appropriate therapeutic options more readily.
Advancements in Therapeutic Approaches
Ongoing research and development efforts have yielded novel therapeutic options, including innovative medications, psychotherapies, and combination approaches that enhance treatment efficacy. For example, recent advancements include MDMA-assisted therapy and repeated ketamine infusions, which have shown promise in treating PTSD. These advancements are complemented by the growing trend toward personalized treatment plans, which cater to individual needs and preferences. By focusing on tailored interventions, healthcare providers can improve treatment outcomes and patient satisfaction, making strides in the management of PTSD.
Improved Healthcare Access and Insurance Coverage
Mental health parity laws have been enacted in many countries, mandating that insurance providers offer mental health benefits on par with medical benefits. This legislative change has significantly increased access to treatment for PTSD. Additionally, the growth of telehealth and remote services has further enhanced accessibility, allowing individuals in remote areas or those with limited mobility to receive mental health care without the constraints of traditional in-person visits.
Destigmatization of Mental Health Issues
Public awareness campaigns aimed at reducing stigma around mental health have fostered an environment where individuals feel more comfortable seeking help for PTSD. The influence of celebrity advocacy has also played a pivotal role, as public figures sharing their mental health experiences normalize conversations about these conditions. These efforts collectively contribute to a more supportive atmosphere for those struggling with PTSD, encouraging them to seek the help they need without fear of judgment.
Market Trends
Shift Towards Combination Therapies and Focus on Early Intervention
The PTSD therapeutics landscape is increasingly characterized by a shift toward combination therapies, reflecting a holistic approach to treatment. There is growing recognition that integrating pharmacological and psychological treatments often yields superior outcomes for patients. Personalized treatment plans, which tailor various therapeutic modalities to individual needs, are becoming more prevalent as healthcare providers aim to address the unique experiences of those suffering from PTSD. Concurrently, there is a strong emphasis on early intervention strategies aimed at preventing PTSD from developing into chronic conditions. Proactive measures such as exposure therapy and cognitive-behavioral therapy are being implemented to address symptoms as soon as they emerge, significantly reducing long-term healthcare costs and enhancing the quality of life for affected individuals. By recognizing the importance of addressing PTSD early, the healthcare community can mitigate its long-term impacts on individuals and society.
Development of Novel Therapeutic Approaches and Increased Emphasis on Telehealth
The development of novel therapeutic approaches continues to shape the PTSD market, with researchers exploring neuropharmacological agents that target specific neurobiological pathways involved in the disorder. For instance, recent advancements include MDMA-assisted therapy and repeated ketamine infusions, which have shown promise in treating PTSD. These advancements are complemented by the emergence of innovative technologies such as virtual reality exposure therapy and neuromodulation, which hold promise as potential treatment options for PTSD. In tandem with these developments, there is an increased emphasis on telehealth and remote care solutions. Telehealth services provide greater accessibility to mental health care, particularly for individuals residing in rural areas or those with limited mobility. Online platforms are being utilized to deliver psychotherapy sessions, support groups, and medication management, thus expanding the reach of mental health resources. As digital therapeutics and mobile apps gain traction, they offer personalized treatment plans, reminders, and tracking capabilities that further enhance patient engagement. This convergence of novel therapeutic approaches and improved access through telehealth reflects a comprehensive effort to transform the landscape of PTSD treatment, ensuring that individuals receive timely and effective care tailored to their needs.
Market Challenges Analysis
Heterogeneity of PTSD and Limited Treatment Efficacy
One of the most significant challenges in addressing Post-Traumatic Stress Disorder (PTSD) lies in the heterogeneity of the condition itself. Individual variability in PTSD symptoms can be substantial, complicating the development of one-size-fits-all treatments. This variability is further exacerbated by the common occurrence of comorbidity, where PTSD coexists with other mental health conditions, making effective treatment even more challenging. As healthcare providers strive to tailor interventions to meet diverse patient needs, the complexity of these cases can hinder the efficacy of treatment strategies. Additionally, even when effective treatments are available, relapse rates remain high, particularly among individuals with severe PTSD. Factors such as resistance to treatment-often stemming from fear, stigma, or personal beliefs-can further complicate recovery, emphasizing the need for a multifaceted approach to therapy that addresses both symptoms and underlying concerns.
Access to Care and Stigma and Discrimination
Access to care presents another formidable challenge in the management of PTSD. Geographic disparities significantly limit mental health care availability, particularly in rural or underserved areas where resources are scarce. For example, the World Health Organization (WHO) reports that only 1 in 4 people with PTSD in low- and middle-income countries seek any form of treatment. Financial barriers also play a critical role, as the cost of treatment can deter individuals from seeking help, especially for those lacking insurance coverage. Compounding these issues is the pervasive stigma and discrimination associated with PTSD. Many individuals experience social isolation due to societal misconceptions surrounding mental health, which can create additional barriers to seeking support. Fear of judgment often prevents individuals from disclosing their symptoms or pursuing necessary treatment, further entrenching their struggles. This complex interplay of access challenges and stigma highlights the urgent need for systemic changes in the mental health care landscape. By addressing these barriers, stakeholders can enhance access to care and create a more supportive environment that encourages individuals to seek help and engage in effective treatment for PTSD.Top of Form
Market Segmentation Analysis:
By Drug Class:
The Post-Traumatic Stress Disorder (PTSD) therapeutics market is segmented by drug class into several categories, each playing a vital role in addressing the condition's multifaceted nature. Antidepressants, particularly selective serotonin reuptake inhibitors (SSRIs), dominate the market due to their efficacy in alleviating depressive symptoms often associated with PTSD. Anti-anxiety drugs are also critical, providing immediate relief for anxiety-related symptoms that frequently accompany the disorder. Additionally, antipsychotics are gaining traction as adjunct therapies, particularly for patients experiencing severe PTSD symptoms or co-occurring disorders. Other drug classes, including mood stabilizers and beta-blockers, contribute to the therapeutic landscape, catering to patients with unique treatment needs. This diverse drug class segmentation underscores the importance of a tailored approach to PTSD treatment, allowing healthcare providers to address the individual needs of patients more effectively and improve overall treatment outcomes.
By Distribution Channel:
The distribution channels for PTSD therapeutics are primarily divided into retail pharmacies and online pharmacies, each offering distinct advantages. Retail pharmacies remain the most traditional and widely utilized channel, providing patients with face-to-face consultations and immediate access to medications. This channel is particularly beneficial for individuals seeking guidance from pharmacists regarding their prescriptions and potential side effects. Conversely, online pharmacies are gaining popularity due to their convenience and accessibility, especially for patients living in remote areas or those with mobility challenges. These platforms enable individuals to obtain their medications discreetly and often at competitive prices. The shift towards digital solutions is further supported by the growing acceptance of telehealth services, which facilitate remote consultations and prescriptions. Together, these distribution channels enhance access to PTSD therapeutics, ensuring that individuals can obtain the necessary medications in a manner that best suits their needs and circumstances.
Segments:
Based on Drug Class:
- Antidepressants
- Anti-anxiety Drugs
- Antipsychotics
- Other Drug Classes
Based on Distribution Channel:
- Retail Pharmacies
- Online Pharmacies
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the Post-Traumatic Stress Disorder (PTSD) therapeutics market, accounting for approximately 45% of the global market. This dominance is largely attributed to the high prevalence of PTSD among veterans and active military personnel, driven by ongoing conflicts and military operations. The region benefits from advanced healthcare infrastructure, extensive research initiatives, and robust funding for mental health programs, facilitating the development and accessibility of effective treatment options. Additionally, increasing awareness and destigmatization of mental health issues contribute to higher rates of diagnosis and treatment uptake in this region. Healthcare policies that promote mental health parity and insurance coverage for PTSD treatments further bolster market growth, ensuring that individuals receive the necessary care and support.
Europe
In Europe, the PTSD therapeutics market accounts for approximately 30% of the global share, driven by rising awareness of mental health disorders and the implementation of supportive healthcare policies. The region is experiencing a growing focus on integrated treatment approaches that combine pharmacological and psychotherapeutic interventions, enhancing the effectiveness of PTSD management. European countries are investing in mental health initiatives, fostering research and development of novel therapeutic options. Moreover, the increased availability of digital therapeutics and telehealth services has improved access to care for individuals living in rural or underserved areas. However, challenges such as cultural variability in mental health perceptions and economic disparities across different countries can impact treatment accessibility and effectiveness. Addressing these challenges through targeted interventions will be crucial for further growth in the European PTSD therapeutics market.
Key Player Analysis
- Aurobindo Pharma Limited
- Aptinyx
- Merck KGaA
- Jazz Pharmaceuticals
- GlaxoSmithKline plc
- Otsuka Pharmaceutical Development & Commercialization, Inc.
- Jubilant Pharmova
- Viatris Inc.
- Pfizer Inc.
- Bionomics Limited
Competitive Analysis
The competitive landscape of the Post-Traumatic Stress Disorder (PTSD) therapeutics market is shaped by several leading players, including Jazz Pharmaceuticals, Pfizer Inc., Merck KGaA, Otsuka Pharmaceutical Development & Commercialization, Inc., and GlaxoSmithKline plc. Companies are investing heavily in research and development to enhance treatment options, focusing on novel formulations and combination therapies that cater to individual patient needs. The emphasis on personalized medicine has led to tailored approaches, improving treatment adherence and outcomes. Additionally, firms are leveraging strategic partnerships and collaborations to expand their reach and enhance access to therapies. The increasing awareness of mental health issues and supportive healthcare policies are also fostering a favorable environment for competition. As the market evolves, continuous innovation and a focus on patient-centric solutions will be crucial for companies to maintain a competitive edge and effectively address the growing demand for effective PTSD treatments.
Recent Developments
- In May 2022, At Biomed Israel, Madrigal Mental Care debuted its nanotechnology for the management and avoidance of post-traumatic stress disorder.
- In January 2022,for the purpose of treating veterans with post-traumatic stress disorder (PTSD) using psychoactive-assisted psychotherapy, Mydecine Innovations Group Inc. has partnered with Combat Stress and the King's College London.
Market Concentration & Characteristics
The market concentration of Post-Traumatic Stress Disorder (PTSD) therapeutics is characterized by a blend of established pharmaceutical companies and emerging biotech firms, leading to a competitive yet fragmented landscape. Major players dominate the market, leveraging significant resources for research and development to innovate and improve therapeutic options. This concentration facilitates the advancement of novel treatment modalities, including personalized medicine and combination therapies, addressing the diverse needs of patients. Additionally, the presence of numerous small to mid-sized companies contributes to a dynamic environment, fostering innovation through specialized approaches and niche therapies. The growing emphasis on mental health awareness has spurred investments in PTSD treatments, encouraging collaborations and partnerships to enhance drug development and distribution. As a result, the market is evolving toward greater accessibility and effectiveness, aiming to provide comprehensive solutions for individuals affected by PTSD while adapting to the changing healthcare landscape and patient needs.
Report Coverage
The research report offers an in-depth analysis based on Drug Class, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued growth in the PTSD therapeutics market is expected as awareness and diagnosis rates increase.
- Advancements in personalized medicine will lead to more tailored treatment plans for individuals suffering from PTSD.
- The integration of digital therapeutics and mobile health applications will enhance treatment accessibility and patient engagement.
- Ongoing research will focus on developing novel pharmacological agents targeting specific neurobiological pathways related to PTSD.
- Combination therapies will become more prevalent, addressing both psychological and physiological aspects of the disorder.
- The expansion of telehealth services will facilitate remote access to mental health care for underserved populations.
- Increased funding and support from government initiatives will drive innovation and improve mental health services.
- Collaborations between pharmaceutical companies and mental health organizations will enhance treatment development and patient support.
- Stigma reduction efforts will encourage more individuals to seek help, further boosting market growth.
- A focus on resilience-building and preventive measures will play a crucial role in reducing the incidence of PTSD.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Prevalence of PTSD
The rising incidence of traumatic events such as natural disasters, conflicts, and violence has led to a higher prevalence of PTSD globally. Greater recognition and understanding of PTSD symptoms have encouraged more individuals to seek treatment, expanding the patient pool for therapeutics.
Advancements in Therapeutic Approaches
Ongoing R&D has resulted in novel pharmacological treatments and innovative psychotherapies, such as MDMA-assisted therapy and ketamine infusions, which are improving treatment efficacy and expanding therapeutic options for PTSD.
Improved Healthcare Access and Insurance Coverage
Mental health parity laws and the growth of telehealth services have made PTSD treatments more accessible, especially for individuals in remote or underserved areas, thereby increasing market penetration.
Destigmatization of Mental Health Issues
Public awareness campaigns and advocacy by public figures have reduced the stigma associated with PTSD, encouraging more people to seek help and driving demand for effective therapeutics.
Shift Toward Combination Therapies and Early Intervention
The trend toward integrating pharmacological and psychological treatments, along with a focus on early intervention, is improving patient outcomes and expanding the market for PTSD therapeutics.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Post-Traumatic Stress Disorder Therapeutics market?
What factors are driving the growth of the Post-Traumatic Stress Disorder Therapeutics?
What are the key segments within the Post-Traumatic Stress Disorder Therapeutics?
What are some challenges faced by the Post-Traumatic Stress Disorder Therapeutics?
Who are the major players in the Post-Traumatic Stress Disorder Therapeutics?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Class
- 1.2.1 Antidepressants
- 1.2.2 Anti-anxiety Drugs
- 1.2.3 Antipsychotics
- 1.2.4 Other Drug Classes
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
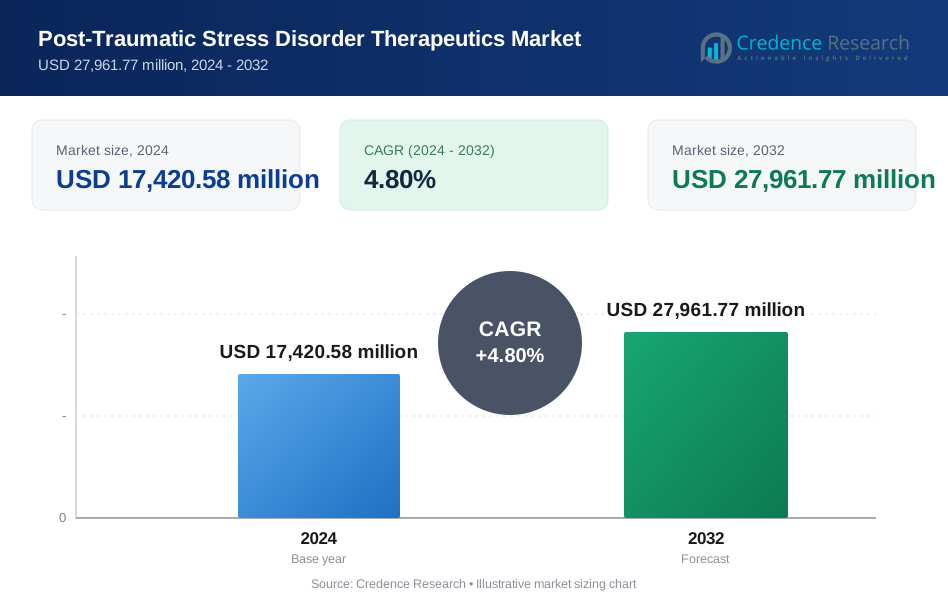
- 2.5.1 2024: USD 17,420.58 million → 2032: USD 27,961.77 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Post-Traumatic Stress Disorder Therapeutics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Post-Traumatic Stress Disorder Therapeutics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Post-Traumatic Stress Disorder Therapeutics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Post-Traumatic Stress Disorder Therapeutics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Post-Traumatic Stress Disorder Therapeutics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Post-Traumatic Stress Disorder Therapeutics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Post-Traumatic Stress Disorder Therapeutics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Post-Traumatic Stress Disorder Therapeutics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 17,420.58 million → 2032: USD 27,961.77 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Post-Traumatic Stress Disorder Therapeutics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Class - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Antidepressants
- 12.3.7.2 Anti-anxiety Drugs
- 12.3.7.3 Antipsychotics
- 12.3.7.4 Other Drug Classes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 Segment Growth Comparison
- 12.5 Segment Attractiveness and Priority Matrix
Chapter 13 Global Post-Traumatic Stress Disorder Therapeutics Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Post-Traumatic Stress Disorder Therapeutics Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Post-Traumatic Stress Disorder Therapeutics Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Jazz Pharmaceuticals
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Pfizer Inc.
- 17.4 Merck KGaA
- 17.5 Otsuka Pharmaceutical Development & Commercialization, Inc.
- 17.6 GlaxoSmithKline plc
- 17.7 Aurobindo Pharma Limited
- 17.8 Aptinyx
- 17.9 Jubilant Pharmova
- 17.10 Viatris Inc.
- 17.11 Bionomics Limited
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

