
Professional Gear Bags Market Overview:
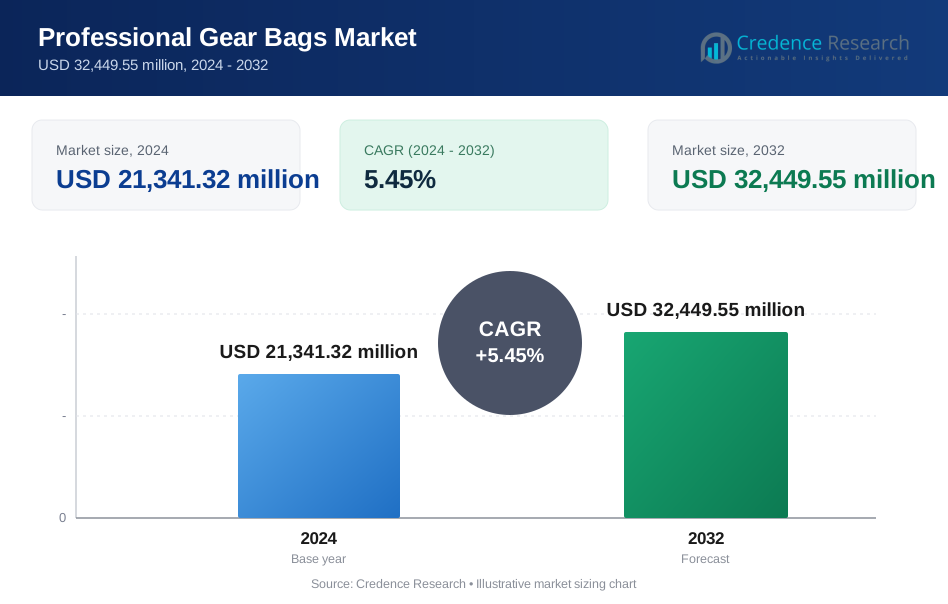
The Professional Gear Bags Market size was valued at USD 18,200.00 million in 2018 to USD 21,341.32 million in 2024 and is anticipated to reach USD 32,449.55 million by 2032, at a CAGR of 5.45% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Professional Gear Bags Market Size 2024 | USD 21,341.32 million |
| Professional Gear Bags Market, CAGR | 5.45% |
| Professional Gear Bags Market Size 2032 | USD 32,449.55 million |
Top players in the Professional Gear Bags market include Targus International LLC, Tumi Holdings, Inc., Case Logic, Nomatic, and SwissGear, each offering specialized solutions for professionals across photography, travel, and technology sectors. These companies lead through innovation, durable materials, and ergonomic design. Targus dominates the laptop and tech gear bag segment, while Tumi and Nomatic excel in premium travel and hybrid-use categories. Case Logic and SwissGear maintain strong presence through functional and affordable designs. North America emerges as the leading region, holding a 42.2% market share in 2024, driven by high professional mobility, tech adoption, and brand preference for quality gear solutions.

Professional Gear Bags Market Insights
- The Professional Gear Bags market was valued at USD 18,200.00 million in 2018, reached USD 21,341.32 million in 2024, and is projected to hit USD 32,449.55 million by 2032, growing at a CAGR of 5.45%.
- Rising demand from photographers, technicians, and mobile professionals is driving consistent product innovation and adoption across camera bags, laptop bags, and tool bags.
- Multifunctional and hybrid-use gear bags, along with eco-friendly materials like recycled nylon and canvas, are gaining popularity, especially among urban and travel-focused consumers.
- Leading companies such as Targus, Tumi, and Case Logic focus on design, durability, and digital integration, while emerging regional brands target price-sensitive users in Asia Pacific and Latin America.
- North America holds a 42.2% share, followed by Europe at 25% and Asia Pacific at 21%, with Camera Bags dominating the product segment due to rising digital content creation and equipment protection needs.
Professional Gear Bags Market Segmentation Analysis:
By Product Type
Camera bags dominate the professional gear bags market by product type, accounting for the largest revenue share. Their popularity stems from rising demand among content creators, journalists, and professional photographers who require protective, compartmentalized storage. Laptop bags follow closely due to increasing mobile workforce trends and digital work lifestyles. Tool bags and sports gear bags are gaining traction among technicians and athletes for their durable, purpose-specific designs. Travel gear bags appeal to business and leisure travelers for convenience and multi-use functionality. The “Others” category includes niche products like drone cases and audio gear bags used in specialized industries.
- For instance, Lowepro supplies camera bags used by professionals in over 100 countries, with its ProTactic series supporting professional DSLR kits and accessories in configurations up to 25–28 liters in volume.
By Material Type
Nylon leads the market among material types, contributing the highest share due to its lightweight, tear-resistant, and water-repellent properties. It offers a favorable balance between durability and cost, making it ideal for frequent-use gear bags. Polyester follows, especially in sports and travel bags, for its resilience and ease of cleaning. Leather bags attract premium users, particularly among photographers and executives, due to their aesthetic appeal and longevity. Canvas material finds use in rugged tool bags and eco-conscious products. The “Others” segment includes hybrid materials and innovations like recycled PET and TPU coatings, catering to sustainability trends.
- For instance, Samsonite uses high-density nylon fabrics in laptop and travel bags tested for over 10,000 abrasion cycles in durability labs.
By End-User
Photographers hold the largest market share in the end-user segment, driving demand for camera bags with padded interiors, customizable compartments, and weather protection. Athletes are another key group, fueling growth in sports gear bags that meet high-capacity and durability needs. Technicians prefer tool bags designed with reinforced compartments and ergonomic features for field operations. Travelers demand versatile and lightweight gear bags that combine style with utility, particularly for carry-on and multi-day use. The “Others” segment includes musicians, medical professionals, and media crews who rely on tailored storage solutions to protect sensitive or high-value equipment.
Professional Gear Bags Market Key Growth Drivers
Expanding Professional Workforce and Specialization
The rise in specialized professionals such as photographers, technicians, athletes, and remote workers has boosted demand for purpose-built gear bags. Each profession requires custom features shock-proof compartments for cameras, reinforced frames for tools, or breathable sections for sports gear. As job roles become more equipment-intensive and mobility-driven, professionals prefer bags that enhance organization, durability, and convenience. The global gig economy and freelancing trend further reinforce this shift, with individuals investing in professional-grade gear protection. Urban professionals also seek travel-friendly solutions that double as both work and personal bags. This expanding workforce, coupled with an emphasis on functional design, significantly contributes to market growth.
- For instance, Think Tank Photo designs roller and backpack systems tested to carry professional DSLR kits weighing over 20 kilograms, meeting airline carry-on standards used by working photographers
Surge in Digital Content Creation and Mobile Tech Use
Widespread adoption of digital tools cameras, drones, tablets, and laptops drives the need for protective and portable carrying solutions. With millions of content creators, vloggers, and media professionals operating on-the-go, demand for camera and laptop bags with integrated compartments and shock resistance has grown rapidly. The increasing popularity of platforms like YouTube, TikTok, and Instagram has made equipment transport an essential part of creators’ workflows. Similarly, remote work and mobile offices require laptop bags with charging ports, theft protection, and RFID shielding. These tech-driven lifestyles have transformed gear bags from simple carriers into essential accessories that blend security, utility, and style.
- For instance, Manfrotto produces camera backpacks rated to hold DSLR bodies with lenses up to 70–200 mm, alongside laptops up to 15 inches, supporting mobile creator workflows.
Innovation in Materials and Functional Design
Advances in lightweight, weather-resistant, and sustainable materials are redefining product innovation in gear bags. Nylon and polyester blends dominate for their strength-to-weight ratio, while demand for eco-friendly fabrics like recycled PET and canvas is rising. Brands now offer ergonomic straps, modular compartments, anti-theft zippers, and heat-resistant linings to appeal to users seeking performance and comfort. Smart features such as USB charging ports, GPS tracking, and water-resistant coatings further attract tech-savvy buyers. Innovation also includes rugged bags with MIL-spec construction for defense, aerospace, or industrial applications. Continuous product upgrades across design, durability, and function act as key enablers for long-term market expansion.

Professional Gear Bags Market Key Trends & Opportunities
Rising Demand for Multi-Utility and Hybrid Bags
A growing segment of consumers prefers multi-purpose bags that serve work, travel, and personal needs in one. This trend supports demand for hybrid designs that blend features of laptop, travel, and camera bags into a single, sleek product. Urban professionals and digital nomads seek convertible gear bags with laptop sleeves, gear padding, and travel compartments offering flexibility and space-saving benefits. The “one-bag travel” movement also supports this demand. As more buyers value minimalist lifestyles and multifunctionality, gear bag makers have an opportunity to offer premium designs with cross-functional utility, creating value across segments and reducing product redundancy for end users.
- For instance, Peak Design designed the Travel Backpack to carry up to 45 liters with modular dividers, fitting laptops up to 16 inches and full camera kits in one bag.
Sustainability as a Differentiation Strategy
Sustainable product lines are emerging as a key opportunity in a crowded market. Consumers are increasingly selecting gear bags made from recycled, organic, or biodegradable materials. Brands that emphasize ethical sourcing, carbon-neutral production, or zero-waste packaging are gaining traction, particularly among younger demographics. Incorporating green certifications or lifecycle traceability helps gear bag makers appeal to environmentally conscious users. This trend also supports long-term brand loyalty and higher price realization. Companies investing in R&D for bio-based fabrics, non-toxic coatings, and circular design systems can position themselves as innovation leaders while aligning with ESG expectations from both consumers and investors.
Professional Gear Bags Market Key Challenges
Price Sensitivity in Emerging Markets
Despite growing demand, price sensitivity remains a major barrier in regions like Asia-Pacific, Africa, and parts of Latin America. Professional-grade gear bags often carry high price tags due to premium materials, patented features, and brand value. Many potential buyers in emerging markets opt for unbranded or low-cost alternatives that offer similar utility at a fraction of the cost. This limits penetration for global brands and reduces margins. While durability and performance justify premium pricing, affordability issues challenge wider adoption. Brands must strike a balance between product quality and cost optimization to sustain growth in price-conscious regions.
Risk of Product Counterfeiting and Brand Dilution
The proliferation of counterfeit products poses a persistent threat to established gear bag brands. Fake products, often made with substandard materials, not only erode brand reputation but also confuse customers seeking genuine gear solutions. Online marketplaces make it easier for counterfeiters to distribute lookalike goods under popular brand names. This undermines consumer trust and creates price distortions. Additionally, counterfeit gear bags often fail to deliver the expected durability and protection, risking equipment damage for end users. Addressing this challenge requires stronger brand authentication, legal enforcement, and digital watermarking or QR verification systems to protect intellectual property.
Professional Gear Bags Market Regional Analysis
North America
North America leads the global Professional Gear Bags market, accounting for the highest revenue share of over 42% in 2024, with market size rising from USD 7,753.20 million in 2018 to USD 8,997.37 million in 2024, and projected to reach USD 13,664.56 million by 2032, growing at a CAGR of 5.5%. The region benefits from high adoption among photographers, technicians, and business travelers. The U.S. and Canada dominate due to strong demand for premium, technologically integrated gear bags. Consumer preference for durable and branded products, coupled with strong retail and e-commerce infrastructure, continues to drive growth in this region.
Europe
Europe contributes a significant 25% share to the Professional Gear Bags market in 2024, growing from USD 4,659.20 million in 2018 to USD 5,245.11 million in 2024, and anticipated to reach USD 7,520.27 million by 2032 at a CAGR of 4.7%. The region shows steady growth driven by professional content creators, industrial tool users, and eco-conscious travelers. Western Europe, particularly Germany, the UK, and France, dominate due to advanced professional gear ecosystems and high disposable incomes. Demand for stylish, sustainable, and multifunctional bags supports market expansion across both premium and mid-range segments.
Asia Pacific
Asia Pacific is the fastest-growing regional market, expanding at a CAGR of 7.0%, with its size increasing from USD 3,539.90 million in 2018 to USD 4,382.35 million in 2024, and projected to reach USD 7,521.83 million by 2032. It accounts for a 21% share in 2024, with China, Japan, India, and South Korea driving adoption due to rising professional workforces and rapid urbanization. Increased smartphone and camera usage, gig economy expansion, and growth in consumer electronics fuel demand for gear bags. Local and international brands are also targeting price-sensitive buyers with multifunctional, tech-friendly, and affordable options.
Latin America
Latin America holds a 7.7% share of the Professional Gear Bags market in 2024, rising from USD 1,419.60 million in 2018 to USD 1,651.60 million in 2024, and forecasted to reach USD 2,364.60 million by 2032, registering a CAGR of 4.7%. Brazil and Mexico lead the region, driven by increased activity in content creation, sports, and small-scale entrepreneurship. While growth is slower compared to Asia Pacific, improving logistics, retail access, and rising brand awareness are supporting demand. Regional brands offering practical, low-cost gear bags are gaining market traction among mobile professionals and technicians.
Middle East
The Middle East Professional Gear Bags market is projected to grow at a 3.6% CAGR, with revenue expanding from USD 509.60 million in 2018 to USD 546.20 million in 2024, and reaching USD 717.31 million by 2032, holding a 2.6% market share in 2024. Growth is moderate due to lower market penetration, but increasing tourism, events, and technology adoption in the UAE and Saudi Arabia are creating new demand. Consumers in urban areas show rising interest in premium travel and tech gear bags. Retail expansion and e-commerce platforms are gradually improving accessibility and brand reach across the region.
Africa
Africa represents the smallest share of the market at 2.4% in 2024, growing from USD 318.50 million in 2018 to USD 518.68 million in 2024, and expected to reach USD 660.97 million by 2032, at a CAGR of 2.6%. Growth remains limited due to lower purchasing power and dependence on unbranded or low-cost alternatives. However, urban centers like Nairobi, Lagos, and Johannesburg are seeing gradual increases in demand for professional and travel gear bags. The rise in skilled labor, field technicians, and mobile professionals contributes modestly. Retail development and digital commerce may unlock future potential.
Professional Gear Bags Market Segmentations:
By Product Type:
- Camera Bags
- Laptop Bags
- Tool Bags
- Sports Gear Bags
- Travel Gear Bags
- Others
By Material Type:
- Leather
- Nylon
- Polyester
- Canvas
- Others
By End-User:
- Photographers
- Athletes
- Technicians
- Travelers
- Others
By Sales Channel:
- Supermarkets/Hypermarkets
- Specialty Stores
- Online
- Departmental Stores
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Competitive Landscape
The professional gear bags market is moderately fragmented, with both global brands and regional players competing across product innovation, material quality, and price positioning. Leading companies such as Targus International LLC, Tumi Holdings, Inc., Case Logic, and Nomatic focus on product differentiation through ergonomic design, tech integration, and sustainable materials. These players invest in R&D to enhance durability, utility, and style, targeting professionals in photography, travel, and tech. New entrants and regional brands offer affordable alternatives, especially in price-sensitive markets like Asia Pacific and Latin America. E-commerce platforms have expanded access for both premium and mid-range brands, intensifying competition. Strategic collaborations with retailers, influencer-driven marketing, and customizable offerings are common approaches to capture niche demand. Companies are also focusing on expanding their international footprint and product lines across business travel, outdoor use, and mobile work scenarios. Innovation, branding, and global distribution remain critical to maintaining market position.
Key Player Analysis
- Targus International LLC
- Case Logic
- Ogio International, Inc.
- Brenthaven
- Crumpler
- Tumi Holdings, Inc.
- SwissGear
- Everki USA, Inc.
- Incase Designs Corp.
- Billingham Bags
- Nomatic
Recent Developments
- In April 2025, TacticalGear Pro, a leading manufacturer of professional and tactical gear bags, launched a new line of eco-friendly, high-durability bags designed specifically for law enforcement and emergency responders. These bags incorporate recycled materials and modular compartments for optimized organization. This launch underscores TacticalGear Pro’s commitment to sustainability while meeting the rigorous demands of professional users, enhancing their position in the growing global Professional Gear Bags Market.
- In January 2025, Peak Design, known for its innovative camera bags, introduced a new Outdoor Line integrating modular components for photographers and hobbyists, with enhanced padding and customizable inserts. This launch addresses the growing market for versatile and protective storage among professional and amateur photographers, reflecting shifting consumer preferences towards multifunctional gear bags.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material Type, End-User, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for durable, multifunctional gear bags will continue rising among mobile professionals and creatives.
- Camera and laptop bags will remain dominant due to growing digital media and remote work culture.
- Asia Pacific will see the fastest growth, driven by expanding middle-class and content creator base.
- Brands will invest more in sustainable materials to align with eco-conscious consumer preferences.
- Smart features like built-in charging, GPS tracking, and RFID protection will become more common.
- E-commerce and direct-to-consumer sales channels will drive market accessibility and brand expansion.
- Premium and hybrid-use gear bags will gain traction among frequent travelers and tech users.
- Regional manufacturers will increase competition by offering low-cost, functional alternatives.
- Product customization and modular designs will attract professionals with specific equipment needs.
- Partnerships with influencers and professional communities will shape brand visibility and loyalty.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Professional Workforce and Specialization
The increasing number of specialized professionals such as photographers, technicians, and remote workers is fueling demand for purpose-built gear bags with custom features like shock-proof compartments and reinforced frames. As job roles become more equipment-intensive and mobility-driven, professionals seek bags that enhance organization, durability, and convenience.
Surge in Digital Content Creation and Mobile Tech Use
The widespread adoption of digital tools such as cameras, drones, and laptops has made protective and portable carrying solutions essential. The rise of content creators and remote work culture is driving demand for camera and laptop bags with integrated compartments, shock resistance, and tech-friendly features.
Innovation in Materials and Functional Design
Advancements in lightweight, weather-resistant, and sustainable materials are leading to new product innovations. Brands are incorporating ergonomic straps, modular compartments, anti-theft zippers, and smart features like USB charging ports to attract tech-savvy and performance-oriented users.
Rising Demand for Multi-Utility and Hybrid Bags
Consumers increasingly prefer multi-purpose gear bags that serve work, travel, and personal needs in one product. This trend is driving the popularity of hybrid designs that combine features of laptop, travel, and camera bags, appealing to urban professionals and digital nomads seeking flexibility and space-saving solutions.
Sustainability as a Differentiation Strategy
Eco-friendly materials and ethical manufacturing practices are becoming key differentiators as consumers, especially younger demographics, seek gear bags made from recycled or biodegradable materials. Brands investing in sustainable product lines and green certifications are gaining traction and building long-term loyalty.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Professional Gear Bags market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Professional Gear Bags market projected to grow between 2024 and 2032?
Which Professional Gear Bags market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Professional Gear Bags market?
Who are the leading companies in the Professional Gear Bags market?
Which region commanded the largest share of the Professional Gear Bags market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Photographers
- 1.2.2 Athletes
- 1.2.3 Technicians
- 1.2.4 Travelers
- 1.2.5 Others
- 1.3 By Product Type
- 1.3.1 Camera Bags
- 1.3.2 Laptop Bags
- 1.3.3 Tool Bags
- 1.3.4 Sports Gear Bags
- 1.3.5 Travel Gear Bags
- 1.3.6 Others
- 1.4 By Material Type
- 1.4.1 Leather
- 1.4.2 Nylon
- 1.4.3 Polyester
- 1.4.4 Canvas
- 1.4.5 Others
- 1.5 By Sales Channel
- 1.5.1 Supermarkets/Hypermarkets
- 1.5.2 Specialty Stores
- 1.5.3 Online
- 1.5.4 Departmental Stores
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 21,341.32 million → 2032: USD 32,449.55 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Professional Gear Bags Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Professional Gear Bags Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Professional Gear Bags Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Professional Gear Bags Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Professional Gear Bags Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Professional Gear Bags Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Professional Gear Bags Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Professional Gear Bags Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 21,341.32 million → 2032: USD 32,449.55 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Professional Gear Bags Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Photographers
- 12.3.7.2 Athletes
- 12.3.7.3 Technicians
- 12.3.7.4 Travelers
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Camera Bags
- 12.4.7.2 Laptop Bags
- 12.4.7.3 Tool Bags
- 12.4.7.4 Sports Gear Bags
- 12.4.7.5 Travel Gear Bags
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Leather
- 12.5.7.2 Nylon
- 12.5.7.3 Polyester
- 12.5.7.4 Canvas
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Supermarkets/Hypermarkets
- 12.6.7.2 Specialty Stores
- 12.6.7.3 Online
- 12.6.7.4 Departmental Stores
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Professional Gear Bags End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Professional Gear Bags Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Professional Gear Bags Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Professional Gear Bags Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Targus International LLC
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Tumi Holdings, Inc.
- 18.4 Case Logic
- 18.5 Nomatic
- 18.6 SwissGear
- 18.7 Ogio International, Inc.
- 18.8 Brenthaven
- 18.9 Crumpler
- 18.10 Everki USA, Inc.
- 18.11 Peak Design
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

