
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Protein Based Sports Supplements Market Size 2024 | USD 7,372.05 Million |
| Protein Based Sports Supplements Market, CAGR | 7.49% |
| Protein Based Sports Supplements Market Size 2032 | USD 13,140.51 Million |
Market Overview
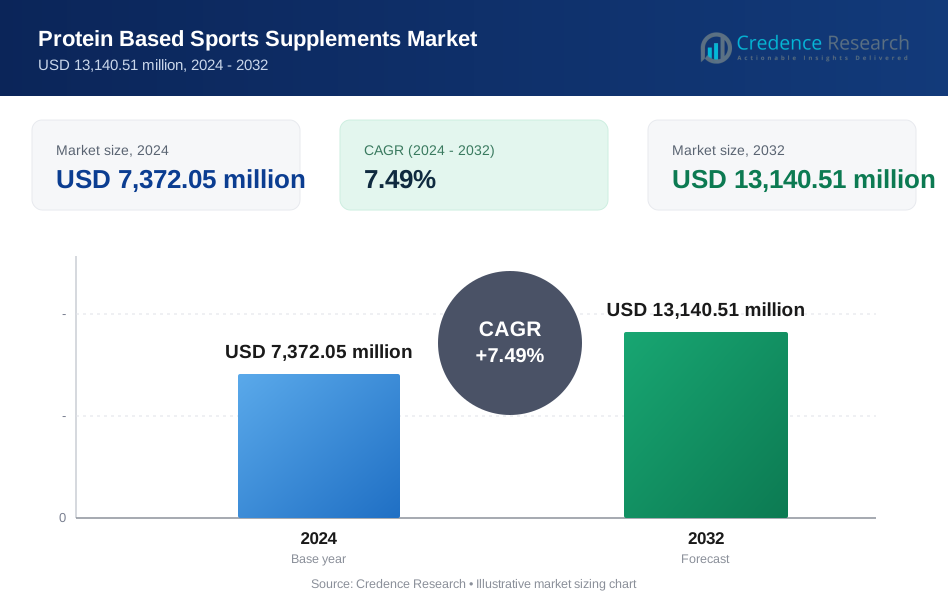
Global Protein Based Sports Supplements Market size was valued at USD 7,372.05 million in 2024 and is anticipated to reach USD 13,140.51 million by 2032, at a CAGR of 7.49% during the forecast period (2024-2032).
The global protein-based sports supplements market is primarily driven by the increasing adoption of active lifestyles and a growing emphasis on physical fitness among consumers across all age groups. Rising awareness of the benefits of protein for muscle growth, recovery, and overall wellness has significantly fueled demand. Additionally, the expanding participation in fitness activities, such as gym workouts, sports, and endurance training, is further accelerating market growth. The trend of clean-label, plant-based, and personalized nutrition is gaining momentum, with consumers seeking high-quality ingredients and tailored supplement solutions. E-commerce expansion and the influence of social media fitness influencers are also playing a pivotal role in promoting product visibility and consumer engagement. Innovations in flavors, formats, and delivery mechanisms such as ready-to-drink protein shakes and protein bars are enhancing consumer convenience and driving repeat purchases. Together, these factors are shaping a dynamic and fast-evolving landscape for protein-based sports supplements worldwide.
The geographical landscape of the global protein-based sports supplements market showcases strong presence across North America, Europe, Asia-Pacific, and Latin America. North America leads due to well-established fitness culture, while Europe follows with rising demand for clean-label and plant-based supplements. Asia-Pacific is emerging rapidly, driven by urbanization, fitness awareness, and increased health-consciousness among the youth. Latin America and the Middle East & Africa are also experiencing growth, supported by shifting consumer lifestyles and expanding retail access. Key players operating in the global market include Glanbia PLC, Abbott Laboratories, MusclePharm Corporation, Quest Nutrition LLC, The Hut Group (Myprotein), Iovate Health Sciences International Inc., AMCO Proteins, NOW Foods, Optimum Nutrition, Inc., and Dymatize Enterprises, LLC. These companies focus on innovation, diverse product portfolios, and strategic partnerships to strengthen market presence. Their efforts are also geared toward catering to evolving dietary preferences and leveraging digital platforms to expand consumer outreach globally.
Market Insights
- The global protein-based sports supplements market was valued at USD 7,372.05 million in 2024 and is projected to reach USD 13,140.51 million by 2032, growing at a CAGR of 7.49%.
- Growing health awareness and increased gym memberships are significantly driving the demand for protein-based sports supplements.
- Rising trends in plant-based and clean-label protein supplements are reshaping consumer preferences across various regions.
- Companies like Glanbia PLC, Abbott Laboratories, and Quest Nutrition are investing in product innovation and expanding global distribution channels.
- High product costs and concerns regarding potential side effects or mislabeling remain key challenges for market growth.
- North America leads the market due to a mature fitness culture and high product availability, while Asia-Pacific shows rapid growth potential.
- Consumers are increasingly purchasing supplements through online platforms, influenced by digital marketing and social media fitness trends.
Report Scope
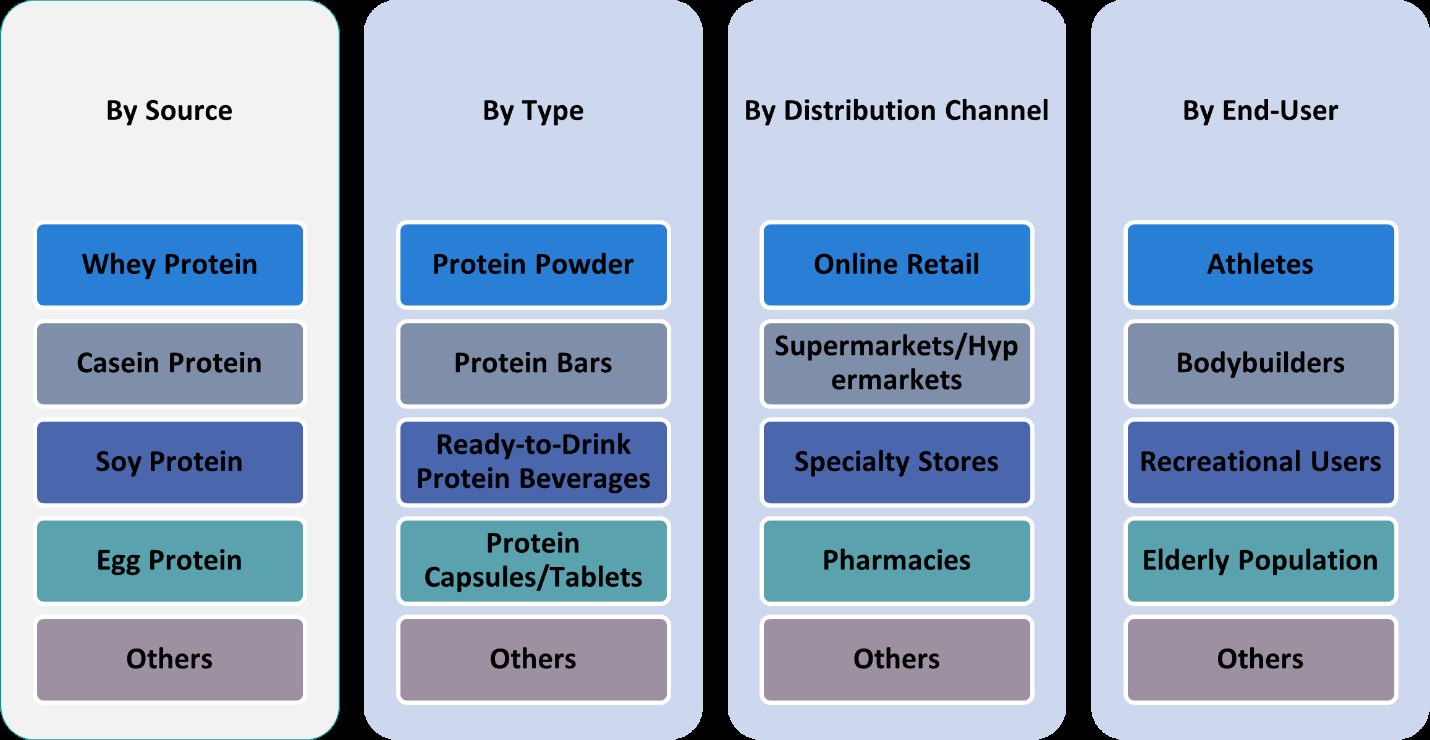
This report segments the Global Protein Based Sports Supplements Market as follows:
Market Drivers
Rising Health Awareness and Fitness-Oriented Lifestyles
he increasing global focus on health and wellness has significantly influenced the growth of the protein-based sports supplements market. Consumers are becoming more conscious of their dietary habits and are actively seeking products that support muscle development, weight management, and overall physical fitness. For instance, government initiatives like India's "Fit India Movement" have been instrumental in promoting fitness awareness among citizens. Similarly, campaigns in the United States, such as "Let's Move!" spearheaded by public figures, have encouraged healthier lifestyles. This shift is particularly prominent among urban populations, where sedentary lifestyles and work-related stress are prompting individuals to engage in fitness activities such as gym workouts, yoga, and running. As consumers strive for better body composition and enhanced performance, the demand for protein supplements as a key nutritional component is surging. Additionally, the growing presence of fitness influencers on platforms like Instagram and YouTube is inspiring individuals to adopt protein-rich diets, thereby driving market expansion.
Expanding Sports and Fitness Industry
The steady expansion of the global sports and fitness industry is another major driver contributing to the demand for protein-based sports supplements. For instance, the establishment of fitness chains like Gold's Gym and Anytime Fitness in multiple countries has made fitness facilities more accessible to the general public. Professional athletes, bodybuilders, and fitness enthusiasts are increasingly incorporating protein supplements into their regular routines to support endurance, recovery, and lean muscle growth. Additionally, sporting events such as marathons, triathlons, and fitness competitions like CrossFit Games are gaining popularity, further fostering interest in performance-enhancing nutritional products. As more individuals across different age groups actively participate in recreational and professional sports, the need for effective protein supplementation continues to rise, thereby fueling consistent market growth.
Innovation in Product Formulations and Delivery Formats
Manufacturers are continuously investing in research and development to introduce innovative formulations that cater to the evolving preferences of health-conscious consumers. The market has seen the emergence of diverse product formats such as protein bars, powders, ready-to-drink shakes, and plant-based alternatives. These innovations offer convenience and cater to consumers with specific dietary restrictions, including vegan and lactose-intolerant individuals. The incorporation of natural ingredients, clean-label claims, and low-sugar or sugar-free variants has further enhanced consumer trust and product appeal. Companies are also exploring advanced delivery mechanisms that improve protein absorption and taste profiles. Such innovations are broadening the consumer base and making protein supplements more appealing to casual users, not just athletes or bodybuilders.
Digital Marketing and E-commerce Expansion
The proliferation of digital platforms and e-commerce channels has revolutionized the way consumers access and purchase protein-based sports supplements. Online retail has become a key driver in market expansion, offering consumers the convenience of browsing a wide range of products, reading reviews, and comparing prices. Digital marketing strategies, including influencer collaborations, social media campaigns, and content-driven engagement, are effectively promoting brand visibility and product awareness. Subscription models and personalized product recommendations offered by online retailers are also boosting consumer loyalty and repeat purchases. The direct-to-consumer model has enabled brands to build strong connections with their audiences, gather valuable feedback, and tailor offerings to meet specific needs all of which contribute to the rapid growth of the protein-based sports supplements market.
Market Trends
Digital Influence and E-commerce Growth
The rise of e-commerce and social media is significantly influencing consumer behavior and brand visibility in the protein-based sports supplements market. For instance, fitness influencers on platforms like Instagram and TikTok are driving product recommendations and brand endorsements. Consumers are increasingly turning to online platforms not only for purchases but also for product education and reviews. This digital ecosystem enables brands to connect directly with their target audiences, launch interactive campaigns, and adapt to consumer feedback in real time. As a result, digitalization is accelerating product discovery, boosting customer loyalty, and shaping purchasing decisions across the global market.
Personalized Nutrition and Functional Benefits
The growing interest in personalized nutrition is driving the development of customized protein-based sports supplements tailored to individual fitness goals and body types. For instance, wearable technologies and apps like MyFitnessPal enable consumers to track their health metrics and select supplements that align with their specific needs. Advances in digital health tools and wearable technologies are enabling consumers to track their health metrics and choose supplements that align with their specific performance needs whether it's muscle gain, endurance, recovery, or weight loss. Additionally, there is a rising demand for multi-functional supplements that offer added benefits such as immune support, joint health, and energy enhancement. To meet these evolving needs, brands are formulating products enriched with vitamins, minerals, amino acids, and adaptogens. This trend toward targeted, value-added supplementation is enhancing user experience and deepening consumer engagement in the sports nutrition space.
Rising Demand for Plant-Based and Clean-Label Products
A significant trend shaping the protein-based sports supplements market is the growing preference for plant-based and clean-label products. With increasing consumer awareness about sustainability, animal welfare, and food sensitivities, demand for plant-derived protein sources such as pea, hemp, soy, and rice has surged. These alternatives offer high nutritional value and appeal to a broader demographic, including vegans, vegetarians, and lactose-intolerant individuals. Additionally, consumers are gravitating towards clean-label formulations free from artificial additives, preservatives, and allergens. Manufacturers are responding by launching organic, non-GMO, and gluten-free protein supplements that cater to health-conscious lifestyles. This trend reflects a shift in consumer values toward transparency, ethical sourcing, and natural ingredients, reshaping product development strategies across the industry.
Convenient and Innovative Product Formats
Convenience continues to be a key purchase driver, prompting manufacturers to innovate across product formats and packaging. Ready-to-drink (RTD) protein shakes, single-serve pouches, protein bars, and powder sachets are gaining popularity due to their portability and ease of consumption. These formats cater to busy lifestyles and on-the-go fitness routines, making it easier for consumers to integrate protein supplements into their daily diets. Moreover, companies are focusing on improving flavor profiles and texture to enhance palatability, especially for first-time users. Functional beverages infused with protein are also emerging as a popular trend, bridging the gap between traditional sports supplements and mainstream food and beverage categories.
Market Challenges Analysis
Regulatory Complexity and Product Quality Concerns
One of the major challenges facing the global protein-based sports supplements market is the complex and evolving regulatory landscape across different regions. Varying standards related to ingredient safety, labeling requirements, health claims, and permissible additives can hinder product approvals and market entry, especially for international brands. For instance, the Food Safety and Standards Authority of India (FSSAI) has issued guidelines to ensure compliance with food safety regulations, including specific labeling and ingredient requirements for supplements. Regulatory scrutiny is particularly high in regions like North America and Europe, where authorities closely monitor supplement formulations for compliance with health and safety norms. Additionally, concerns over product authenticity, contamination, and mislabeling have surfaced due to the proliferation of counterfeit or low-quality supplements in both physical and online retail spaces. These quality control issues can lead to loss of consumer trust and damage brand reputations, making it critical for manufacturers to adhere to strict quality assurance protocols and transparent labeling practices. Navigating these regulatory hurdles while ensuring consistent product integrity remains a significant barrier to sustainable market growth.
High Cost and Limited Consumer Awareness in Emerging Markets
Another key challenge impacting the protein-based sports supplements market is the relatively high cost of premium-quality products, which can limit their affordability and accessibility, particularly in developing economies. Many protein supplements-especially those made from whey isolates, hydrolysates, or plant-based sources-are priced at a premium due to the high cost of raw materials, processing, and packaging. As a result, price-sensitive consumers in regions such as Asia-Pacific, Latin America, and Africa may opt for traditional protein sources or avoid supplementation altogether. Furthermore, limited awareness about the benefits of protein supplementation, coupled with cultural dietary preferences and misconceptions about supplement use, continues to hinder market penetration in these regions. To overcome these challenges, companies need to focus on cost-effective formulations, localized marketing strategies, and consumer education campaigns that highlight the health benefits and safety of protein-based sports supplements. Addressing these barriers is essential for expanding the market’s reach and achieving inclusive growth.
Market Opportunities
The global protein-based sports supplements market presents significant growth opportunities driven by the increasing adoption of fitness regimes across diverse consumer segments. While traditionally targeted at athletes and bodybuilders, protein supplements are now gaining popularity among recreational fitness enthusiasts, senior citizens, and even adolescents seeking improved health and stamina. This widening demographic is creating a favorable environment for market expansion. Moreover, the growing shift toward preventive healthcare and nutritional wellness is encouraging individuals to incorporate protein supplements as part of their daily diets. Emerging economies, particularly in Asia-Pacific and Latin America, are witnessing rapid urbanization and rising disposable incomes, which are expected to further drive demand. As awareness about protein intake and its role in maintaining overall health continues to grow, these regions offer a largely untapped market with considerable long-term potential for both local and international brands.
Another promising opportunity lies in continued innovation and product diversification. Consumers are increasingly seeking personalized nutrition that aligns with specific dietary preferences, such as vegan, keto, and allergen-free options. Brands that invest in developing plant-based proteins, fortified supplements, and functional ingredients can capture a larger share of this health-conscious market. In addition, the rise of digital platforms has transformed how consumers research and purchase sports nutrition products. Companies leveraging e-commerce, mobile apps, and influencer-driven marketing can enhance brand visibility, consumer engagement, and loyalty. Subscription-based services and personalized product recommendations also offer opportunities to boost customer retention. Furthermore, collaborations with gyms, health clubs, and wellness centers can strengthen distribution networks and build brand credibility. As consumer preferences continue to evolve, companies that prioritize innovation, transparency, and convenience are well-positioned to seize emerging opportunities in the dynamic protein-based sports supplements market.
Market Segmentation Analysis:
By Type:
The protein-based sports supplements market is segmented by type into protein powder, protein bars, ready-to-drink protein beverages, protein capsules/tablets, and others. Among these, protein powders dominate the market due to their widespread use among athletes, bodybuilders, and fitness-conscious individuals seeking muscle growth and recovery support. These powders are versatile, offering ease of mixing and a wide range of formulations tailored to specific health goals. Protein bars have gained popularity as convenient, on-the-go nutrition options, particularly among working professionals and recreational users. Meanwhile, ready-to-drink protein beverages are becoming increasingly favored for their portability and taste, especially among younger demographics. Protein capsules and tablets cater to consumers preferring minimal preparation and accurate dosing. The "others" category, which includes snacks and baked products fortified with protein, reflects growing innovation within the industry. Each product type is tailored to fit evolving consumer lifestyles, contributing to the segment’s overall growth and ensuring widespread adoption across various end-user groups.
By Source:
By source, the global market is categorized into whey protein, casein protein, soy protein, egg protein, and others. Whey protein holds the largest market share due to its fast absorption rate and high biological value, making it ideal for post-workout recovery and muscle repair. Its dominance is further supported by its extensive scientific validation and consumer trust. Casein protein, with its slow digestion rate, appeals to users seeking sustained amino acid release, particularly overnight or between meals. Soy protein has carved a niche among vegetarians and lactose-intolerant consumers, offering a plant-based alternative with a favorable amino acid profile. Egg protein is appreciated for its complete amino acid content and high digestibility, making it a reliable animal-based option for those avoiding dairy. The "others" segment includes proteins derived from peas, rice, and hemp, gaining momentum as consumers demand sustainable and allergen-friendly alternatives. Together, these diverse protein sources address a wide spectrum of dietary preferences and performance needs in the global market.
Segments:
Based on Type:
- Protein Powder
- Protein Bars
- Ready-to-Drink Protein Beverages
- Protein Capsules/Tablets
- Others
Based on Source:
- Whey Protein
- Casein Protein
- Soy Protein
- Egg Protein
- Others
Based on End- User:
- Athletes
- Bodybuilders
- Recreational Users
- Elderly Population
- Others
Based on Distribution Channel:
- Online Retail
- Supermarkets/Hypermarkets
- Specialty Stores
- Pharmacies
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America held the largest share of the global protein-based sports supplements market in 2024, accounting for approximately 39% of the overall revenue. The region's dominance can be attributed to the strong presence of health-conscious consumers, widespread gym culture, and a mature sports nutrition industry. The United States, in particular, drives regional growth due to its high consumer expenditure on fitness-related products and increasing demand for functional foods. Moreover, the proliferation of e-commerce platforms and influencer-driven marketing has amplified accessibility and awareness of protein supplements. Major industry players headquartered in the region also contribute to continuous innovation and product diversification. The rising popularity of plant-based protein products among vegan and lactose-intolerant populations further supports the market's expansion in North America.
Europe
Europe follows as the second-largest regional market, capturing a 27% share in 2024. Countries such as Germany, the United Kingdom, and France are leading consumers of protein-based sports supplements, supported by growing awareness around active lifestyles and preventive health. The European market is characterized by a balanced demand for both traditional protein sources like whey and emerging alternatives like soy and pea proteins. Regulatory support for clean-label and organic products has encouraged manufacturers to introduce products with minimal additives and sustainable sourcing. Additionally, increasing female participation in fitness activities and wellness trends has opened new consumer segments. As lifestyle diseases become more prevalent, consumers in Europe are increasingly adopting protein supplements not only for athletic performance but also for general wellness, driving sustained market growth.
Asia-Pacific
Asia-Pacific is emerging as the fastest-growing region, accounting for around 21% of the market share in 2024. Rapid urbanization, rising disposable incomes, and increasing penetration of Western fitness and dietary habits are key factors fueling growth across countries like China, India, and Australia. The younger population is showing a strong inclination towards bodybuilding, sports, and fitness, which is translating into higher consumption of protein-based supplements. Local and international brands are actively expanding their presence through online and offline distribution networks. Furthermore, increased social media engagement and celebrity endorsements are playing a vital role in promoting health and nutritional products. The growth potential in Asia-Pacific remains significant, especially with expanding health awareness in tier 2 and tier 3 cities.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa collectively accounted for approximately 13% of the global market in 2024. Although these regions currently represent a smaller portion of the market, they offer untapped potential. In Latin America, countries like Brazil and Mexico are witnessing increasing interest in health and fitness, aided by rising middle-class populations and improving economic conditions. Meanwhile, the Middle East is seeing a surge in gym memberships and fitness club openings, particularly in the UAE and Saudi Arabia. As consumer preferences evolve and awareness about protein intake grows, these regions are expected to attract new investments and product launches, thus contributing to future global market expansion.
Key Player Analysis
- Glanbia PLC
- Abbott Laboratories
- MusclePharm Corporation
- Quest Nutrition LLC
- The Hut Group (Myprotein)
- Iovate Health Sciences International Inc.
- AMCO Proteins
- NOW Foods
- Optimum Nutrition, Inc.
- Dymatize Enterprises, LLC
Competitive Analysis
The global protein-based sports supplements market is highly competitive, driven by the presence of several prominent players that continually strive for market dominance through innovation, expansion, and strategic collaborations. Leading companies such as Glanbia PLC, Abbott Laboratories, MusclePharm Corporation, Quest Nutrition LLC, The Hut Group (Myprotein), Iovate Health Sciences International Inc., AMCO Proteins, NOW Foods, Optimum Nutrition, Inc., and Dymatize Enterprises, LLC focus on diversifying their product offerings to meet evolving consumer demands. These players invest heavily in research and development to introduce new formulations, such as plant-based proteins, fortified supplements, and functional blends tailored to specific fitness goals. These companies focus on product innovation, offering diverse protein sources such as whey, casein, soy, and plant-based options to cater to a broad range of consumer preferences. Strong branding, partnerships with fitness influencers, and targeted digital marketing campaigns are key strategies for engaging with health-conscious consumers, particularly those in the millennial and Gen Z demographics. E-commerce platforms are becoming increasingly significant, with many companies leveraging online retail channels to expand their reach and improve customer engagement. This digital shift is complemented by growing social media presence and influencer endorsements, which help drive consumer interest. Additionally, companies are increasingly emphasizing clean-label products, sustainability, and health benefits to differentiate themselves in a crowded market. Product diversification, such as offering protein supplements in various forms like powders, bars, ready-to-drink beverages, and capsules, is another strategy used to cater to different consumer needs.
Recent Developments
- In March 2025, Quest Nutrition introduced Quest Protein Milkshakes, ready-to-drink beverages with a category-leading 45 grams of protein per bottle. Available in chocolate, vanilla, and strawberry flavors, these shakes cater to high-protein diets with minimal sugar and carbs.
- In December 2024, Dymatize launched Performance Protein Shakes and Energyze Pre-Workout Powder. The ready-to-drink shakes contain 30 grams of high-quality proteins along with BCAAs for muscle recovery and growth.
- In November 2024, Myprotein expanded operations in India by manufacturing locally to meet growing demand. The brand introduced localized flavors such as Kesar Badam and Nimbu Pani and launched Clear Whey Isolate as a refreshing alternative to traditional protein shakes.
- In January 2024, Abbott launched Protality, a high-protein weight-loss shake designed for individuals on weight-loss medications. Each serving contains 30 grams of protein and is tailored to preserve muscle mass while supporting weight loss.
Market Concentration & Characteristics
The global protein-based sports supplements market exhibits a moderate level of concentration, with a few large players holding significant market share, while numerous smaller and niche brands contribute to a highly fragmented competitive landscape. Major players lead the market by offering a wide range of products, such as protein powders, bars, and ready-to-drink beverages, targeting both professional athletes and recreational users. The market is characterized by intense innovation, with companies constantly evolving their product portfolios to cater to changing consumer demands for plant-based, clean-label, and functional supplements. The growing trend towards personalized nutrition also drives companies to offer tailored solutions for different fitness goals, such as muscle gain, weight loss, and endurance. Moreover, the rise of e-commerce and direct-to-consumer sales models has increased accessibility, enabling both established and emerging brands to expand their reach. Despite fierce competition, market dynamics favor businesses that prioritize product quality, sustainability, and effective marketing strategies.
Report Coverage
The research report offers an in-depth analysis based on Type, Source, End-User, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The global protein-based sports supplements market is expected to continue its growth trajectory, driven by increasing health consciousness and fitness trends.
- Plant-based protein supplements are likely to see significant growth as consumers seek more sustainable and ethical dietary options.
- E-commerce platforms will play a crucial role in market expansion, offering direct access to consumers and enhancing brand visibility.
- There will be a growing demand for personalized protein supplements tailored to individual fitness goals and nutritional needs.
- Advances in protein technology, such as protein fortification and functional ingredients, will fuel innovation in the product offerings.
- Clean-label and transparent ingredient sourcing will become essential as consumers become more discerning about product quality and sustainability.
- Companies will invest in research and development to improve protein formulations, focusing on digestibility and bioavailability.
- Cross-industry collaborations with fitness and wellness brands will strengthen market reach and expand consumer engagement.
- The rise of online fitness communities and influencers will continue to drive consumer interest and brand loyalty.
- Regulatory frameworks will evolve to ensure quality control and safety standards, enhancing consumer confidence in protein supplements.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Health Awareness and Fitness-Oriented Lifestyles
Increasing global focus on health and wellness is prompting consumers to adopt active lifestyles and seek protein-based supplements to support muscle development, weight management, and overall fitness. Public health campaigns and the influence of fitness culture are expanding the consumer base for these products.
Expanding Sports and Fitness Industry
The proliferation of gyms, fitness centers, and organized sporting events is driving demand for protein supplements among athletes, bodybuilders, and recreational users. As more people participate in fitness activities, the need for effective protein supplementation for muscle recovery and endurance is rising.
Innovation in Product Formulations and Delivery Formats
Manufacturers are introducing diverse product formats such as protein bars, ready-to-drink shakes, and plant-based alternatives, making protein supplementation more convenient and appealing to a wider audience. Innovations in taste, texture, and functional ingredients are attracting new users and encouraging repeat purchases.
Digital Marketing and E-commerce Expansion
The growth of e-commerce and digital marketing, including influencer partnerships and social media campaigns, is increasing product visibility and accessibility. Online platforms allow consumers to easily compare, review, and purchase protein supplements, accelerating market growth.
Shift Toward Plant-Based and Clean-Label Products
Consumer demand for sustainable, allergen-friendly, and ethically sourced protein supplements is driving the development of plant-based and clean-label products. This trend is expanding the market to include vegans, vegetarians, and those with dietary sensitivities, further fueling overall growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Protein Based Sports Supplements market?
What factors are driving the growth of the Global Protein Based Sports Supplements market?
What are the key segments within the Global Protein Based Sports Supplements market?
What are some challenges faced by the Global Protein Based Sports Supplements market?
Who are the major players in the Global Protein Based Sports Supplements market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Protein Powder
- 1.2.2 Protein Bars
- 1.2.3 Ready-to-Drink Protein Beverages
- 1.2.4 Protein Capsules/Tablets
- 1.2.5 Others
- 1.3 By Source
- 1.3.1 Whey Protein
- 1.3.2 Casein Protein
- 1.3.3 Soy Protein
- 1.3.4 Egg Protein
- 1.3.5 Others
- 1.4 By End-User
- 1.4.1 Athletes
- 1.4.2 Bodybuilders
- 1.4.3 Recreational Users
- 1.4.4 Elderly Population
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,372.05 million → 2032: USD 13,140.51 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Protein Based Sports Supplements Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Protein Based Sports Supplements Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Protein Based Sports Supplements Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Protein Based Sports Supplements Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Protein Based Sports Supplements Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Protein Based Sports Supplements Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Protein Based Sports Supplements Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Protein Based Sports Supplements Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,372.05 million → 2032: USD 13,140.51 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Protein Based Sports Supplements Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Protein Powder
- 12.3.7.2 Protein Bars
- 12.3.7.3 Ready-to-Drink Protein Beverages
- 12.3.7.4 Protein Capsules/Tablets
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Source - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Whey Protein
- 12.4.7.2 Casein Protein
- 12.4.7.3 Soy Protein
- 12.4.7.4 Egg Protein
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-User - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Athletes
- 12.5.7.2 Bodybuilders
- 12.5.7.3 Recreational Users
- 12.5.7.4 Elderly Population
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Protein Based Sports Supplements End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Protein Based Sports Supplements Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Protein Based Sports Supplements Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Protein Based Sports Supplements Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Glanbia PLC
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Abbott Laboratories
- 18.4 MusclePharm Corporation
- 18.5 Quest Nutrition LLC
- 18.6 The Hut Group (Myprotein)
- 18.7 Iovate Health Sciences International Inc.
- 18.8 AMCO Proteins
- 18.9 NOW Foods
- 18.10 Optimum Nutrition, Inc.
- 18.11 Dymatize Enterprises, LLC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

