
Market Overviews
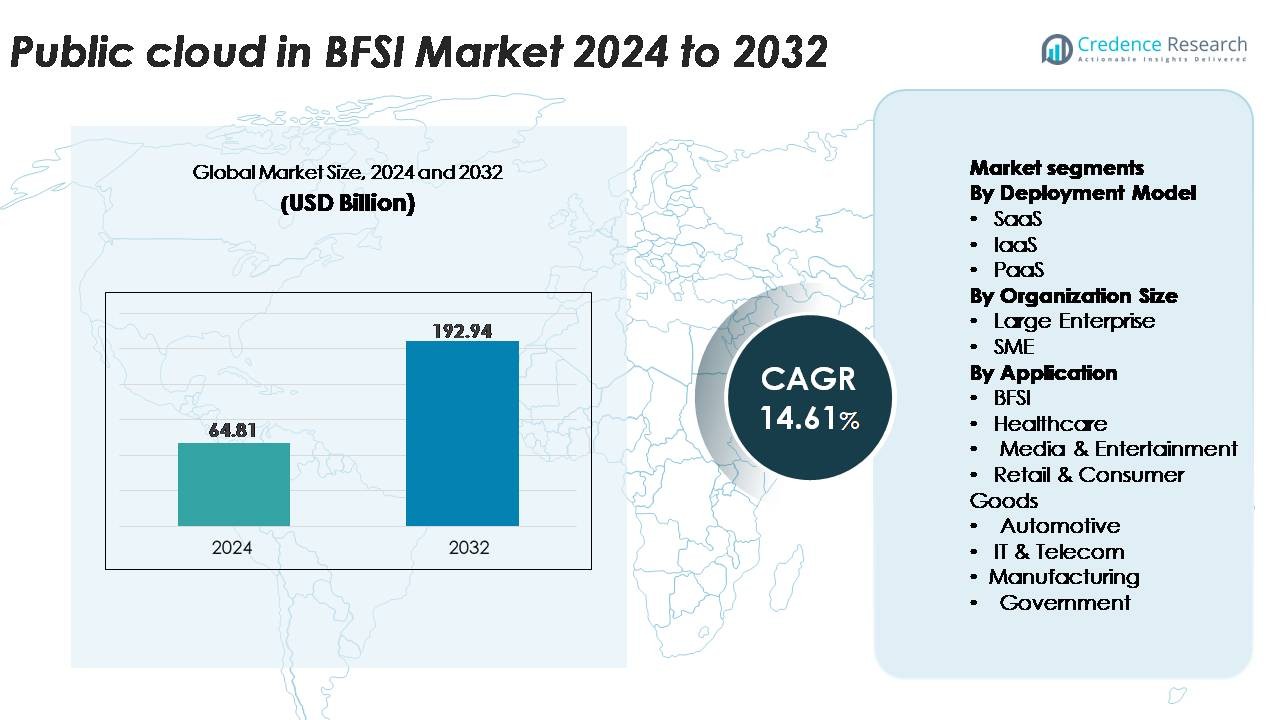
The public cloud in BFSI market was valued at USD 64.81 billion in 2024 and is anticipated to reach USD 192.94 billion by 2032, expanding at a CAGR of 14.61% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Public Cloud In BFSI Market Size 2024 | USD 64.81 Billion |
| Public Cloud In BFSI Market, CAGR | 14.61% |
| Public Cloud In BFSI Market Size 2032 | USD 192.94 Billion |
The public cloud in BFSI market is shaped by major technology providers that offer secure, compliant, and scalable cloud architectures tailored to banking and insurance workloads. Key players such as IBM Corporation, Tencent Cloud, Oracle Corporation, Salesforce, Google LLC, SAP SE, Nutanix, Amazon Web Services, Alibaba Group, and Microsoft Corporation continue to expand industry-specific cloud services, advanced analytics, and AI-driven automation for financial institutions. These companies strengthen competitiveness through data-residency solutions, multi-cloud management, and fintech ecosystem integration. North America leads the market with approximately 34% share, supported by aggressive cloud modernization and strong regulatory alignment, followed by Asia-Pacific and Europe, which show rapid adoption across digital banking and payments modernization.
Market Insights
- The public cloud in BFSI market was valued at USD 64.81 billion in 2024 and is projected to reach USD 192.94 billion by 2032, registering a 14.61% CAGR, driven by accelerated digital transformation across global banking and insurance sectors.
- Strong market momentum arises from rising demand for scalable infrastructure, AI-driven analytics, core banking modernization, and enhanced security frameworks, with SaaS holding the largest segment share due to rapid deployment and compliance-ready features.
- Key trends include rapid expansion of multi-cloud adoption, growth of cloud-native payment systems, and increasing collaboration between cloud providers, fintech platforms, and regtech vendors to support real-time processing and regulatory automation.
- Competitive intensity remains high as AWS, Microsoft, Google, IBM, Oracle, and Alibaba strengthen cross-industry cloud offerings, sovereign-cloud capabilities, and integrated cybersecurity services while addressing restraints such as data-residency rules and migration complexity.
- Regionally, North America leads with ~34% share, followed by Asia-Pacific at ~30% and Europe at ~28%, reflecting strong cloud modernization, digital payments expansion, and open-banking acceleration across these markets.
Market Segmentation Analysis:
By Deployment Model
In the deployment model segment, SaaS dominates the public cloud in BFSI market, capturing the largest share due to its rapid implementation, modular scalability, and strong alignment with digital banking modernization initiatives. Financial institutions increasingly adopt SaaS-based core banking modules, CRM platforms, fraud-detection engines, and regulatory reporting tools to reduce IT overhead and speed up innovation cycles. IaaS gains traction for core infrastructure consolidation, while PaaS adoption rises as banks build cloud-native applications. However, SaaS leads growth as BFSI enterprises prioritize continuous upgrades, subscription affordability, and compliance-ready managed services.
- For instance, Salesforce Financial Services Cloud leverages Einstein AI, which makes tens of billions of AI-powered predictions per day. This technology enables features like real-time credit scoring and customer-engagement automation at scale.
By Organization Size
Among organization sizes, large enterprises account for the dominant market share, driven by accelerated cloud migration roadmaps, multi-region failover requirements, and the integration of advanced analytics and cybersecurity frameworks. Established banks and insurance providers leverage cloud platforms to modernize legacy systems, streamline omnichannel operations, and meet stringent regulatory standards. SMEs are expanding adoption steadily, using public cloud services to minimize upfront investment and leverage preconfigured security and automation capabilities. While SME uptake grows across digital lending and fintech operations, large enterprises remain the primary adopters due to the scale of workloads and transformation budgets.
- For instance, AWS supports multi-region financial deployments using its Global Infrastructure of over 105 Availability Zones, enabling banks to achieve recovery time objectives measured in seconds for critical workloads.
By Application
Within the application segment, BFSI remains the leading sub-segment, accounting for the largest share as banks, insurers, and fintech firms increasingly adopt cloud-based solutions for real-time payments processing, digital onboarding, risk modeling, and regulatory compliance automation. Healthcare, retail, media, and government sectors also contribute to growth as they adopt cloud platforms for data integration and consumer-facing digital services. However, BFSI continues to dominate due to the sector’s high dependency on secure cloud environments, advanced analytics, and AI-driven fraud management systems that support resilient and scalable financial service delivery.
Key Growth Drivers:
Rapid Digital Transformation and Core System Modernization
Banks and financial institutions increasingly prioritize modernization of legacy IT environments to support real-time operations, customer-centric service models, and digital-first engagement. Public cloud platforms enable BFSI organizations to migrate core banking, payment processing, and CRM systems to scalable architectures that reduce operational complexity and accelerate deployment cycles. Institutions leverage cloud-native microservices, containerization, and continuous integration pipelines to deliver faster product updates and improve service reliability. This modernization push is reinforced by rising consumer adoption of mobile banking, instant payments, and digital lending. The ability of public cloud systems to handle high-volume transactions, integrate advanced analytics, and support seamless API connections with fintech ecosystems makes them central to ongoing digital acceleration. As financial institutions pursue long-term operational agility, cloud-based modernization remains a major driver of market expansion.
- For instance, Google Kubernetes Engine (GKE) supports cluster scaling up to 65,000 nodes for Standard clusters (in version 1.31 and later) and 5,000 nodes for Autopilot clusters.
Rising Demand for Data Security, Compliance Automation, and Fraud Prevention
Data protection and regulatory adherence are critical priorities across the BFSI ecosystem, pushing institutions toward public cloud platforms that offer built-in security automation, encryption, digital identity tools, and compliance-ready architectures. Cloud providers deliver frameworks aligned with global standards such as PCI DSS, ISO 27001, GDPR, and region-specific financial regulations, reducing the compliance burden for institutions. Banks increasingly deploy cloud-based fraud detection engines, behavioral analytics, and AI-driven risk scoring models to counter rising cyberattacks and financial crime. Public cloud infrastructures also support enhanced auditability through automated log monitoring, configuration baselines, and controlled data governance. As threats grow more sophisticated, public cloud adoption is driven by the need for adaptive security, proactive threat intelligence, and continuous compliance, enabling BFSI organizations to manage risk more effectively while maintaining operational resilience.
- For instance, AWS GuardDuty analyzes tens of billions of events across multiple AWS data sources (including AWS CloudTrail logs, Amazon VPC Flow Logs, and DNS query logs) to detect anomalies and malicious activity in near real-time.
Expansion of Digital Payments, Open Banking, and API-led Ecosystems
The rapid evolution of digital payments, open banking frameworks, and embedded finance models drives financial institutions to adopt public cloud to support high-speed transaction processing and seamless third-party integrations. Cloud-native APIs enable banks to connect with fintech platforms, payment gateways, and digital identity services while maintaining strong security controls. Public cloud environments offer performance optimization for instant payment schemes, cross-border remittances, and real-time settlement systems that require elastic compute power. The growth of digital wallets, BNPL services, neo-banks, and decentralized financial products further intensifies the need for scalable cloud infrastructure. As regulators encourage data portability and interoperability through open banking initiatives, cloud platforms become essential for institutions aiming to innovate quickly and deliver personalized financial services. This ecosystem-driven transformation significantly boosts market adoption.
Key Trends and Opportunities:
Acceleration of AI, ML, and Advanced Analytics Adoption
Public cloud platforms generate new opportunities for BFSI institutions to scale AI, machine learning, and predictive analytics across customer engagement, risk modeling, underwriting, and portfolio management. Banks deploy cloud-based analytics engines to deliver personalized insights, automate credit scoring, and enhance operational forecasting. AI-driven automation also supports intelligent document processing, chatbot-based servicing, and anomaly detection in financial transactions. As cloud providers offer pre-trained models, GPU acceleration, and integrated data-lake architectures, adoption becomes more cost-effective and faster to deploy. The rising emphasis on hyper-personalization, autonomous finance, and algorithmic decision-making creates long-term opportunities for cloud-enabled AI ecosystems within BFSI.
- For instance, Google’s Vertex AI can train large-scale models using pods of up to 16,384 TPU v5e chips, enabling high-speed execution of fraud-detection and risk-scoring workloads.
Growth of Hybrid, Multi-Cloud, and Sovereign Cloud Architectures
Financial institutions increasingly adopt hybrid and multi-cloud strategies to balance regulatory compliance, data residency requirements, and operational flexibility. This trend creates significant opportunities for public cloud providers offering secure interconnectivity, unified workload management, and institution-specific data localization frameworks. Sovereign cloud initiatives emerge as a strategic priority, enabling BFSI organizations to store sensitive workloads within national boundaries while maintaining access to global cloud innovations. Multi-cloud adoption also mitigates vendor lock-in and enhances resilience through redundancy. As financial regulators promote operational continuity and risk diversification, hybrid and multi-cloud models gain traction, expanding the market’s growth potential.
- For instance, Microsoft’s Cloud for Sovereignty supports deployments across more than 60 Azure regions and enables policy enforcement through over 10,000 built-in compliance controls, ensuring regulated data remains within approved jurisdictions.
Expansion of Cloud-Based Banking-as-a-Service (BaaS) and Fintech Collaboration
The rise of BaaS platforms, digital onboarding solutions, and embedded financial services creates new opportunities for public cloud adoption in BFSI. Cloud providers increasingly partner with fintech companies, core banking vendors, and digital payment solution providers to build modular, API-enabled ecosystems. These collaborations support rapid launch of digital-only banks, micro-lending services, wealth-tech platforms, and insurance-tech products. Public cloud infrastructure enables low-latency integrations and scalable deployment of customer-facing applications. As more institutions shift to platform-based business models, cloud-enabled BaaS becomes a major opportunity area, fostering innovation and new revenue streams across the financial value chain.
Key Challenges:
Regulatory Complexity, Data Residency Constraints, and Audit Requirements
While public cloud adoption accelerates, financial institutions face significant challenges in meeting strict regulatory mandates related to data storage, cross-border data transfer, operational continuity, and audit transparency. Many regions require sensitive financial data to remain within domestic boundaries, limiting how institutions can deploy public cloud workloads. Frequent updates to supervisory guidelines demand continuous risk assessments, vendor audits, and compliance reporting, increasing operational burden. Institutions must also maintain visibility into shared responsibility models, encryption policies, and third-party access controls. These regulatory complexities slow down migration timelines and require robust governance frameworks to ensure adherence without compromising innovation.
Legacy System Integration, Skill Gaps, and Migration Complexity
Integrating legacy core banking systems with modern cloud architectures remains a major challenge for BFSI institutions. Many banks operate decades-old mainframes with tightly coupled applications, making cloud migration technically complex and resource-intensive. The shortage of cloud-native skills such as DevOps, container orchestration, and microservices design further delays transformation initiatives. Migration also involves high operational risk, including potential downtime, data synchronization issues, and architectural redesign. Institutions must balance modernization efforts with day-to-day operations, making phased transitions essential. These integration and skill challenges continue to slow adoption despite strong long-term benefits of public cloud deployment.
Regional Analysis:
North America
North America holds the largest share at approximately 34%, driven by strong adoption of cloud-native banking platforms, digital payment modernization, and stringent cybersecurity frameworks. Large banks and insurance providers accelerate migration of core workloads to public cloud to enhance resiliency, strengthen compliance automation, and support real-time analytics. The U.S. leads deployment, supported by mature financial infrastructure and strong cloud–fintech collaboration. Canada follows with increased investment in digital banking transformation and open-banking readiness. The region’s advanced regulatory alignment and high innovation spending continue to position it as the primary contributor to market growth.
Europe
Europe accounts for around 28% of the global market, fueled by rapid adoption of cloud services across retail banking, payments, and insurance as institutions respond to PSD2, GDPR, and open-banking mandates. Countries such as the UK, Germany, and the Nordics lead cloud migration initiatives, emphasizing data sovereignty, sovereign cloud partnerships, and cross-border digital payment standardization. Financial institutions increasingly deploy cloud-enabled analytics, fraud detection, and digital onboarding solutions. Growing collaboration between global cloud providers and European regulators further accelerates compliance-ready cloud adoption. This structured regulatory ecosystem strengthens Europe’s position as a high-value regional contributor.
Asia-Pacific
Asia-Pacific represents approximately 30% of the market, emerging as the fastest-growing region due to large-scale digital banking expansion, rising fintech activity, and sustained cloud investments in China, India, Japan, and Southeast Asia. Banks adopt public cloud to support real-time payments, digital lending, and high-volume mobile banking environments. Government-led digital economy initiatives and national cloud policies accelerate BFSI migration. The region also experiences strong adoption of AI-driven fraud detection and cloud-based compliance platforms. With a rapidly expanding customer base and high demand for mobile-first services, Asia-Pacific continues to generate strong demand for scalable cloud infrastructure.
Latin America
Latin America contributes around 5% of global market share, supported by growing cloud adoption among banks modernizing legacy systems and expanding digital banking services. Brazil and Mexico lead deployments as financial institutions invest in cloud-based payment rails, digital onboarding, and cybersecurity modernization. Fintech expansion, particularly in digital wallets and micro-lending, further boosts public cloud demand. While regulatory clarity varies across countries, rising cloud partnerships and national digital transformation programs help accelerate adoption. Despite infrastructure challenges, the region presents emerging opportunities driven by increasing mobile banking penetration and rising consumer demand for digital financial access.
Middle East & Africa
The Middle East & Africa (MEA) region holds approximately 3% of the market, with cloud adoption accelerating in Gulf Cooperation Council economies, including the UAE and Saudi Arabia. Banks invest in cloud platforms to enhance compliance, support digital payments, and deploy AI-driven customer engagement solutions. National cloud and data-residency policies such as Saudi Arabia’s digitalization initiatives and the UAE’s cloud-first strategies encourage BFSI migration. In Africa, growing mobile banking ecosystems and fintech innovation stimulate demand for scalable public cloud infrastructure. While adoption remains gradual, MEA shows rising momentum driven by digital transformation agendas and expanding financial inclusion.
Market Segmentations:
By Deployment Model
- SaaS
- IaaS
- PaaS
By Organization Size
- Large Enterprise
- SME
By Application
- BFSI
- Healthcare
- Media & Entertainment
- Retail & Consumer Goods
- Automotive
- IT & Telecom
- Manufacturing
- Government
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape:
The competitive landscape of the public cloud in BFSI market is defined by the presence of major global cloud providers and specialized fintech–cloud partnerships that collectively shape digital transformation strategies across the financial sector. Leading players including AWS, Microsoft Azure, Google Cloud, IBM Cloud, and Oracle Cloud compete by offering compliance-ready architectures, advanced security frameworks, and AI-driven analytics tailored to banking and insurance workloads. These vendors invest heavily in multi-zone data centers, sovereign cloud capabilities, and regulatory certifications to meet evolving financial governance requirements. Strategic collaborations with core banking vendors, payment processors, regtech providers, and digital identity platforms further strengthen market positioning. Providers differentiate through industry-specific offerings such as cloud-native core banking engines, fraud detection suites, API management platforms, and high-performance compute for real-time transaction processing. As BFSI institutions accelerate modernization, competition intensifies around automation, resilience, and integrated AI services, driving continuous innovation across the ecosystem.
Key Player Analysis:
- IBM Corporation
- Tencent Cloud
- Oracle Corporation
- Salesforce, Inc.
- Google LLC
- SAP SE
- Nutanix
- Amazon Web Services, Inc.
- Alibaba Group Holding Limited
- Microsoft Corporation
Recent Developments:
- In May 2025, Nutanix released a public preview of its Cloud Clusters (NC2) on Google Cloud, enabling hybrid and multicloud workload mobility including migration and disaster-recovery capabilities suited for finance environments.
- In May 2025, Oracle launched new cloud services targeted at retail banking institutions, enabling modernization of lending and collections functions through its public-cloud infrastructure and applications.
- In November 2025, IBM signed a long-term agreement with German financial-services provider Atruvia GmbH to modernize its IT platform using IBM’s cloud, automation and data-services portfolio across banking operations and hybrid-cloud workloads.
Report Coverage:
The research report offers an in-depth analysis based on Deployment model, Organization size, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Public cloud adoption in BFSI will accelerate as banks modernize core systems and expand cloud-native digital banking capabilities.
- Institutions will increase use of AI, ML, and automation on cloud platforms to enhance fraud detection, underwriting, and customer analytics.
- Multi-cloud and hybrid cloud strategies will strengthen as organizations balance resilience, vendor diversification, and regulatory compliance.
- Cloud-enabled real-time payment infrastructure will expand to support growing demand for instant transactions and cross-border connectivity.
- Open banking and API-driven ecosystems will deepen cloud dependency as banks collaborate more with fintech and regtech partners.
- Sovereign cloud frameworks will gain momentum as countries enforce data residency, privacy, and governance requirements.
- Cloud-based cybersecurity tools will evolve to address sophisticated financial threats through continuous monitoring and adaptive protection.
- Digital onboarding, KYC automation, and cloud-hosted identity solutions will become mainstream across financial institutions.
- Cloud adoption among insurers will grow through advanced risk modeling, claims automation, and telematics integration.
- The shift toward autonomous finance and personalized digital services will push BFSI providers toward deeper cloud integration across all operations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Digital Transformation and Core System Modernization
Banks and financial institutions are accelerating the modernization of legacy IT environments to enable real-time operations, customer-centric service models, and digital-first engagement. Public cloud platforms support migration of core banking, payment processing, and CRM systems to scalable, resilient architectures, reducing operational complexity and speeding up innovation cycles.
Rising Demand for Data Security, Compliance Automation, and Fraud Prevention
The BFSI sector faces stringent regulatory requirements and increasing cyber threats, driving adoption of public cloud solutions with built-in security, encryption, and compliance frameworks. Cloud providers offer automated fraud detection, behavioral analytics, and risk scoring, enabling institutions to manage risk and regulatory obligations more effectively.
Expansion of Digital Payments, Open Banking, and API-led Ecosystems
The growth of digital payments, open banking, and embedded finance models requires scalable, high-performance cloud infrastructure. Public cloud enables real-time transaction processing, seamless third-party integrations, and supports the rapid launch of new digital financial products and services.
Acceleration of AI, ML, and Advanced Analytics Adoption
BFSI organizations leverage public cloud to deploy AI and machine learning for customer engagement, risk modeling, underwriting, and fraud detection. Cloud-based analytics engines and pre-trained models enable hyper-personalization, operational forecasting, and intelligent automation at scale.
Growth of Hybrid, Multi-Cloud, and Sovereign Cloud Architectures
To address regulatory compliance, data residency, and operational resilience, financial institutions are increasingly adopting hybrid and multi-cloud strategies. Public cloud providers are responding with secure interconnectivity, data localization, and sovereign cloud offerings tailored to BFSI needs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Public Cloud in BFSI market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is Polylactic Acid (PLA) Market projected to grow between 2024 and 2032?
Which Polylactic Acid (PLA) Market segment held the largest share in 2024?
What are the primary factors fueling the growth of Polylactic Acid (PLA) Market?
Who are the leading companies in Polylactic Acid (PLA) Market?
Which region commanded the largest share of Polylactic Acid (PLA) Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 BFSI
- 1.2.2 Healthcare
- 1.2.3 Media & Entertainment
- 1.2.4 Retail & Consumer Goods
- 1.2.5 Automotive
- 1.2.6 IT & Telecom
- 1.2.7 Manufacturing
- 1.2.8 Government
- 1.3 By Deployment Model
- 1.3.1 SaaS
- 1.3.2 IaaS
- 1.3.3 PaaS
- 1.4 By Organization Size
- 1.4.1 Large Enterprise
- 1.4.2 SME
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
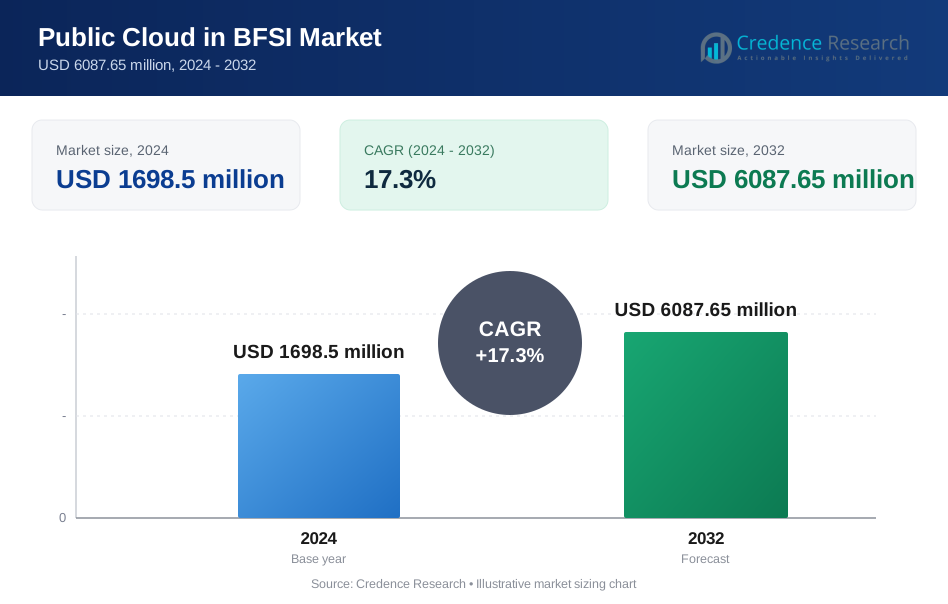
- 2.5.1 2024: USD 1698.5 million → 2032: USD 6087.65 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Public Cloud in BFSI Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Public Cloud in BFSI Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Public Cloud in BFSI Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Public Cloud in BFSI Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Public Cloud in BFSI Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Public Cloud in BFSI Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Public Cloud in BFSI Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Public Cloud in BFSI Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1698.5 million → 2032: USD 6087.65 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Public Cloud in BFSI Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 BFSI
- 12.3.7.2 Healthcare
- 12.3.7.3 Media & Entertainment
- 12.3.7.4 Retail & Consumer Goods
- 12.3.7.5 Automotive
- 12.3.7.6 IT & Telecom
- 12.3.7.7 Manufacturing
- 12.3.7.8 Government
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Deployment Model - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 SaaS
- 12.4.7.2 IaaS
- 12.4.7.3 PaaS
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Organization Size - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Large Enterprise
- 12.5.7.2 SME
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Public Cloud in BFSI End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Public Cloud in BFSI Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Public Cloud in BFSI Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Public Cloud in BFSI Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 IBM Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Tencent Cloud
- 18.4 Oracle Corporation
- 18.5 Salesforce, Inc.
- 18.6 Google LLC
- 18.7 SAP SE
- 18.8 Nutanix
- 18.9 Amazon Web Services, Inc.
- 18.10 Alibaba Group Holding Limited
- 18.11 Microsoft Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

