
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Pumpkin Spice Products Market Size 2024 | USD 998 million |
| Pumpkin Spice Products Market, CAGR | 10.2% |
| Pumpkin Spice Products MarketSize 2032 | USD 2170.6 million |
Market Overview:
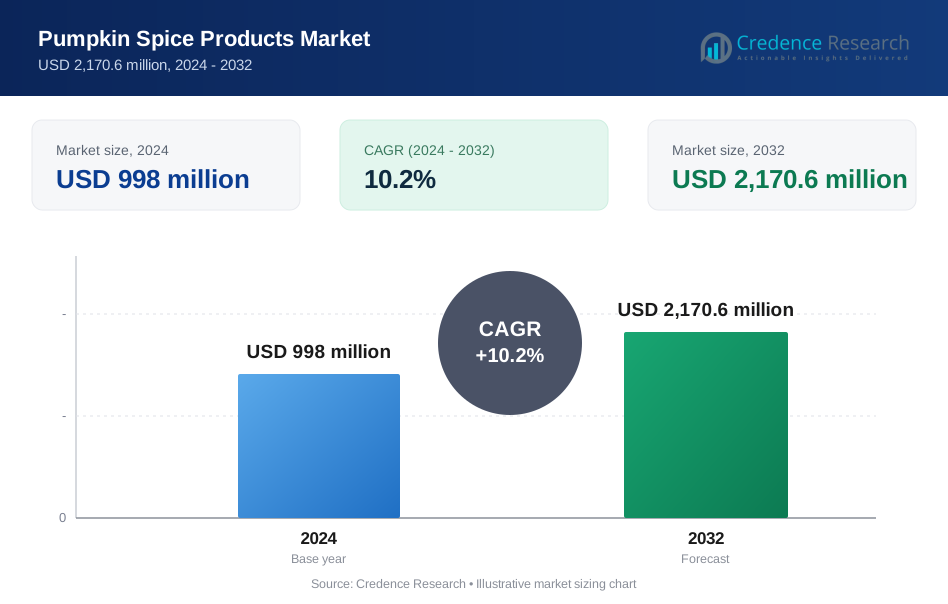
The Pumpkin spice products market is projected to grow from USD 998 million in 2024 to an estimated USD 2170.6 million by 2032, with a compound annual growth rate (CAGR) of 10.2% from 2024 to 2032.
Consumer demand for nostalgic and seasonal flavors drives the market’s core momentum, especially in the autumn months when pumpkin spice becomes a cultural and culinary staple. Companies are capitalizing on this emotional connection by releasing limited-time offerings that generate excitement and urgency. At the same time, the rise of e-commerce, evolving consumer health preferences, and clean-label trends are opening up new market opportunities. Brands are introducing low-sugar, organic, vegan, and gluten-free versions of pumpkin spice products to appeal to a broader customer base. The influence of large chains like Starbucks and Dunkin’ plays a pivotal role in maintaining the trend’s visibility, creating viral seasonal buzz and driving consumer behavior.
Regionally, North America dominates the pumpkin spice products market, accounting for more than half of global revenues. The United States, in particular, sees an annual surge in demand during the fall, driven by both retail sales and foodservice offerings. Europe is emerging as a strong secondary market, particularly in the UK, Germany, and France, where consumer curiosity and import-driven availability are growing. Asia-Pacific represents the fastest-growing region, fueled by rising urbanization, Western cultural influence, and expanding middle-class spending on lifestyle products. Meanwhile, emerging markets in Latin America, the Middle East, and Africa are witnessing gradual adoption of seasonal products, especially through urban retail channels and online platforms. Across all geographies, the pumpkin spice products market remains a compelling opportunity, blending tradition, innovation, and targeted marketing to sustain strong consumer engagement.
Market Insights:
- The pumpkin spice products market is set to grow from USD 998 million in 2024 to USD 2,170.6 million by 2032, with a CAGR of 10.2%, driven by seasonal demand and expanding global reach.
- Nostalgia and emotional connections fuel strong consumer engagement, especially in North America, where autumn traditions boost recurring annual sales.
- Companies are diversifying their offerings across categories like snacks, protein bars, dairy, and even alcoholic beverages to maintain novelty and appeal to wider demographics.
- Clean-label, organic, vegan, and low-sugar pumpkin spice variants are gaining traction as health-conscious consumers seek indulgent yet mindful options.
- E-commerce and subscription models allow brands to extend their reach, test international markets, and respond to seasonal trends with agility.
- The market faces challenges from its seasonal nature and potential flavor fatigue, requiring innovation and strategic planning to sustain relevance.
- North America dominates with over 45% of global share, while Europe and Asia-Pacific emerge as promising regions through urban influence, food innovation, and lifestyle branding.
Market Drivers:
Seasonal Consumer Sentiment and Cultural Appeal Boost Product Demand:
The strong association of pumpkin spice with autumn, holidays, and comfort creates powerful emotional resonance for consumers. This seasonal sentiment drives recurring annual demand, particularly in North America, where pumpkin spice products are deeply embedded in fall traditions. The limited-time nature of these offerings generates urgency and encourages early purchases. Retailers and foodservice providers consistently use seasonal marketing strategies to boost foot traffic and sales. Social media platforms amplify this trend, with consumers sharing their seasonal experiences, contributing to viral marketing cycles. The pumpkin spice products market benefits from this cultural integration, which reinforces predictable spikes in seasonal consumption.
- For instance, Starbucks reported selling over 600 million Pumpkin Spice Lattes (PSLs) since the drink’s introduction in 2003, making it the company’s most popular seasonal beverage.
Innovation Across Food and Beverage Categories Expands Market Scope:
Product innovation plays a central role in the growth of the pumpkin spice products market. Brands have expanded beyond traditional baked goods and beverages into snacks, cereals, dairy items, protein bars, and even alcohol. This diversification allows companies to target different demographics and dietary preferences. Clean-label, organic, and vegan pumpkin spice variants appeal to health-conscious consumers, widening the market base. Innovations in packaging and formulation also improve shelf life and accessibility, making seasonal products viable across more retail formats. The market responds well to innovation that preserves the core flavor profile while offering convenience and novelty.
- For example, Nestlé Toll House reintroduced its Pumpkin Spice Cookie Dough in 2024, available in 14-ounce packages at major retailers nationwide.
Strategic Marketing and Brand Partnerships Drive Consumer Engagement:
Strong branding and collaborative campaigns continue to energize the pumpkin spice products market. High-profile launches by chains like Starbucks and Dunkin’ serve as seasonal triggers that influence consumer expectations and retailer rollouts. Limited-edition packaging and influencer collaborations create excitement and social media traction. Retailers align in-store promotions and shelf placements with the seasonal calendar, ensuring high visibility during peak demand. Companies also use cross-brand partnerships, integrating pumpkin spice flavors into existing popular products to drive incremental sales. These strategies enhance consumer engagement and sustain the flavor trend across both core and adjacent categories.
Rising E-commerce and Global Expansion Support Market Penetration:
Online platforms have made seasonal product access more convenient, helping globalize the pumpkin spice trend. E-commerce allows brands to launch early-season promotions and reach consumers in non-traditional markets. Subscription services and direct-to-consumer models further strengthen access to limited-time offerings. It supports geographic expansion by enabling smaller brands to test new regions without major retail investment. International interest in Western seasonal trends is growing, particularly in Europe and Asia-Pacific. The pumpkin spice products market leverages these digital channels to build momentum beyond its traditional core regions.
Market Trends:
Expansion into Non-Food Categories Enhances Market Versatility:
The pumpkin spice products market is witnessing an increase in non-food applications, broadening its seasonal footprint. Brands are incorporating the flavor profile into candles, air fresheners, skincare, and personal care products. These extensions allow the sensory appeal of pumpkin spice to move beyond the kitchen into lifestyle and wellness domains. Consumers respond positively to the nostalgic scent in everyday products, particularly during fall. Retailers strategically align these launches with seasonal decor trends, boosting complementary sales. The non-edible segment contributes to the overall value of the market and enhances brand presence across diverse consumer touchpoints.
- For instance, SC Johnson’s Glade brand released its limited-edition Pumpkin Spice Things Up scented candles and air fresheners in August 2024, with the line including 3.4-ounce candles and 8-ounce room sprays available at major retailers.
Growing Influence of Limited-Edition Strategies Across Brands:
Brands across multiple sectors are increasingly using limited-edition pumpkin spice offerings to generate seasonal buzz. These products build a sense of exclusivity and urgency, encouraging impulse purchases and repeat visits. The strategy also supports brand loyalty, with consumers anticipating annual releases from favorite retailers or manufacturers. Companies are applying this tactic not only to premium products but also to budget and mass-market items. This trend supports revenue spikes during Q3 and Q4 and fuels a competitive atmosphere among brands to launch earlier or more creatively. The pumpkin spice products market thrives on this cyclical but intensifying launch strategy.
- For example, The Kraft Heinz Company produced only 1,000 units of its limited-edition Pumpkin Spice Kraft Dinner in Canada in 2024, which sold out within days after launch.
Emergence of Functional and Health-Focused Pumpkin Spice Products:
Health and wellness trends are reshaping product development in the pumpkin spice space. Brands are introducing pumpkin spice-flavored protein powders, probiotic drinks, and low-sugar alternatives to meet dietary needs. Functional claims such as gut health, immunity boosting, or clean-label sourcing are now attached to seasonal launches. This alignment with health-conscious behaviors allows pumpkin spice products to appeal beyond indulgence, tapping into daily consumption habits. Retailers highlight these attributes in health food aisles and e-commerce filters to drive targeted sales. The pumpkin spice products market is adapting to modern consumer expectations by blending seasonal flavor with nutritional value.
Social Media and Influencer Marketing Shape Consumer Demand:
Social media continues to play a pivotal role in shaping consumer engagement with pumpkin spice products. Influencers and content creators generate seasonal excitement through product reviews, seasonal shopping hauls, and themed recipe content. Visual platforms like Instagram, TikTok, and Pinterest amplify the aesthetic and cultural appeal of pumpkin spice. Hashtags, viral challenges, and user-generated content accelerate product visibility and create community-driven hype. Brands leverage these dynamics by launching influencer campaigns and seasonal digital experiences. The pumpkin spice products market gains sustained momentum through social-driven trends that convert digital attention into retail demand.
Market Challenges Analysis:
Seasonal Dependency Limits Year-Round Revenue Potential:
The pumpkin spice products market faces a significant challenge due to its strong seasonal association. Most products experience peak sales during the fall months, particularly between September and November. This limited window restricts sustained year-round revenue generation and strains supply chain planning. Retailers and manufacturers must forecast demand with precision, as excess inventory quickly loses value post-season. The market struggles to maintain consumer interest outside of the fall period, making brand engagement difficult during off-peak months. It requires brands to carefully balance novelty with consistency to manage both hype and operational efficiency.
Flavor Fatigue and Market Saturation Create Consumer Apathy:
An oversaturation of pumpkin spice-flavored products across food, beverage, and non-food segments risks causing consumer fatigue. As more brands introduce similar products, the novelty that initially drove excitement may begin to fade. Customers may perceive these offerings as gimmicky or redundant, impacting purchase intent. Lack of product differentiation can reduce brand loyalty and weaken seasonal momentum. The pumpkin spice products market must innovate with new formats, pairings, or health benefits to remain compelling. It faces pressure to refresh its positioning each year to counteract stagnation in a highly competitive seasonal niche.
Market Opportunities:
Expansion into Non-Traditional Categories Broadens Consumer Reach:
The pumpkin spice products market holds strong potential in expanding beyond its core food and beverage categories. Brands can explore growth in beauty, personal care, home fragrance, and pet products to diversify their seasonal offerings. Consumers show growing interest in novelty-driven self-care and lifestyle goods, creating demand for pumpkin spice-themed candles, lotions, soaps, and grooming items. This extension builds emotional connections with the season while introducing the flavor profile into new consumer routines. It allows companies to leverage established seasonal branding while accessing less saturated segments. The pumpkin spice products market can benefit from cross-category campaigns that reinforce brand identity and seasonal sentiment.
Health-Conscious Formulations Attract a Wider Demographic:
Rising demand for better-for-you and clean-label products presents an opportunity to reformulate pumpkin spice offerings for health-aware consumers. Sugar-free, vegan, gluten-free, and organic versions of seasonal items align with current dietary preferences. This shift opens new channels among fitness-focused and wellness-driven customers who previously avoided indulgent seasonal products. The pumpkin spice products market can drive adoption by emphasizing natural ingredients, functional benefits, and nutritional transparency. It also allows brands to reposition pumpkin spice from a nostalgic indulgence to a permissible seasonal treat. Such reformulations support product differentiation and long-term relevance in evolving consumer landscapes.
Market Segmentation Analysis:
By Form
The pumpkin spice products market includes powders, syrups, and blends. Powders are widely used in dry mixes and baking applications due to their versatility. Syrups dominate the beverage sector, offering ease of integration in lattes and seasonal drinks. Blends combine spices for ready-to-use solutions across both edible and non-edible categories.
- For instance, Starbucks offers Pumpkin Spice Sauce as the base for its Pumpkin Spice Latte, while Torani markets its Pumpkin Spice Syrup in 750 ml bottles for both foodservice and home use.
By Application / Product Category
Beverages and baked goods represent the most prominent segments, with pumpkin spice lattes and seasonal bakery items driving consumer demand. Creamers, snacks, and frozen desserts show consistent seasonal uptake. Non-food applications like candles, personal care products, and home fragrances are expanding, supported by consumer preference for nostalgic and seasonal scents.
- For example, in 2024, Entenmann’s released Pumpkin Donuts in 15-ounce boxes, Pillsbury launched Pumpkin Spice Rolls with icing in 17.5-ounce tubes, and Great Value (Walmart) offered Pumpkin Spice Cream Cheese Spread in 8-ounce tubs.
By Distribution Channel
Supermarkets and hypermarkets lead distribution, offering broad access during peak seasons. Online retail is growing due to convenience and brand variety. Specialty stores and cafes play a key role in introducing premium and artisanal products. Convenience stores cater to impulse purchases and limited-time offers.
By End User
Food and beverage companies remain the primary end users, with major brands launching seasonal ranges annually. Household and personal care manufacturers leverage the fragrance appeal of pumpkin spice in lotions, soaps, and scented products.
Segmentation:
By Form
- Powder
- Syrups
- Blends
By Application / Product Category
- Creamers
- Seasonings
- Frozen Desserts
- Baked Goods (e.g., cookies, cakes, pies)
- Beverages (e.g., lattes, teas)
- Snacks (e.g., popcorn, granola bars, nuts)
- Candles
- Personal Care Products (e.g., body lotions, soaps, air fresheners)
- Home Fragrances
By Distribution Channel
- Supermarkets/Hypermarkets
- Online Retail Stores
- Convenience Stores
- Specialty Stores
- Cafes/Restaurants
By End User
- Food and Beverage Industry
- Household/Personal Care
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Leads with Strong Cultural Affinity and Seasonal Marketing Power
North America dominates the pumpkin spice products market, accounting for over 45% of global revenue. The United States drives demand through a deeply ingrained seasonal tradition that blends nostalgia with modern food trends. Major retailers, quick-service restaurants, and FMCG companies launch limited-time offerings in late summer to capitalize on the fall season. Consumers in this region associate pumpkin spice with comfort and indulgence, boosting sales of beverages, baked goods, snacks, and scented home products. Canada follows a similar pattern with strong adoption in urban markets. The region benefits from a mature retail infrastructure, social media amplification, and an enthusiastic consumer base that embraces seasonal variety.
Europe Embraces Pumpkin Spice Through Urban Trends and Food Innovation
Europe holds approximately 25% of the global pumpkin spice products market, driven by increasing exposure to North American food culture and rising demand for seasonal flavors. Countries like the United Kingdom, Germany, and the Netherlands lead the adoption, supported by urban consumer segments that follow global culinary trends. Coffee chains and artisanal bakeries play a key role in introducing pumpkin spice-flavored drinks and confections. The market responds to rising interest in natural and clean-label ingredients, creating room for premium and organic formulations. Local brands often tailor pumpkin spice profiles to regional palates, combining cinnamon and nutmeg with native spices. European markets show steady growth potential due to increased product innovation and seasonal marketing campaigns.
Asia-Pacific and Other Emerging Regions Show Gradual Uptake
Asia-Pacific represents about 15% of the pumpkin spice products market and shows rising interest through globalized foodservice trends and premium café culture. Japan, South Korea, and Australia lead the regional market, where consumers engage with Western seasonal experiences through branded beverage and dessert chains. Adoption remains niche but is growing through exposure to social media and international travel. Local adaptation of pumpkin spice flavors continues to evolve based on traditional spice blends and regional taste preferences. Latin America, the Middle East, and Africa contribute a smaller market share but present opportunities through growing middle-class populations and premium product demand. The pumpkin spice products market continues to expand globally by leveraging cross-cultural branding and seasonal lifestyle positioning.
Key Player Analysis:
- Starbucks Corporation
- The Kraft Heinz Company
- Nestlé S.A. (including Libby’s Pumpkin and Nestlé Toll House)
- McCormick & Company, Inc.
- Dunkin’ (Inspire Brands)
- Entenmann’s
- Trader Joe’s
- Kellogg’s
- Pillsbury
- Kind Snacks
- Harry & David
- Glade (SC Johnson)
- Great Value (Walmart)
Competitive Analysis:
The pumpkin spice products market features a mix of established multinational brands, seasonal product innovators, and regional players competing for consumer attention during a limited selling window. Major food and beverage companies such as Starbucks, Nestlé, General Mills, and Dunkin' dominate with early product launches and strong brand recognition. Retailers and private labels also expand offerings in beverages, bakery, snacks, and home fragrances. The market rewards speed to shelf, creative seasonal branding, and cross-category integration. It shows high competition in North America, with global players adapting flavor profiles for other regions. Companies invest in limited-time marketing strategies, influencer engagement, and product diversification to drive consumer interest. The pumpkin spice products market remains dynamic, with new entrants leveraging e-commerce platforms and niche consumer preferences to gain share. Product innovation, timing, and cultural relevance continue to shape competitive positioning in this flavor-driven seasonal market.
Recent Developments:
- In August 2024, Nestlé S.A. expanded its pumpkin spice product range through its Toll House brand by reintroducing Pumpkin Spice Cookie Dough. The 14-ounce packs, featuring pumpkin spice-flavored dough with white morsels, returned to nationwide retailers for a limited time. Nestlé also continued to offer its Coffee mate Pumpkin Spice Liquid Non-Dairy Creamer and Libby’s Pumpkin for baking and cooking.
- In August 2024, Dunkin’ (Inspire Brands) launched its fall menu featuring the return of the Pumpkin Spice Signature Latte, Pumpkin Cake Donut, Pumpkin Muffin, and Munchkins donut hole treats. Notably, Dunkin’ also introduced the Dunkin’ Spiked Pumpkin Spice Iced Latte, a ready-to-drink alcoholic beverage with 6% ABV, available in 27 states for a limited time.
- In September 2024, Entenmann’s, a Bimbo Bakeries USA brand, brought back its popular pumpkin-flavored bakery treats, including Pumpkin Donuts, Pumpkin Loaf Cake, Iced Pumpkin Cake, and Pumpkin Pop’ems. These limited-edition products were distributed nationally through November.
Market Concentration & Characteristics:
The pumpkin spice products market shows moderate concentration, with a few dominant brands holding significant seasonal influence while niche players actively expand category diversity. It revolves around a limited time frame, typically aligned with autumn and holiday periods, which intensifies product turnover and consumer engagement. The market covers a wide range of segments, including beverages, bakery goods, snacks, cereals, candles, and personal care items. It thrives on nostalgia, flavor novelty, and emotional marketing, with demand largely driven by consumer sentiment and social trends. Seasonal exclusivity and recurring limited-edition releases create urgency and high purchase intent. The pumpkin spice products market adapts quickly to lifestyle shifts and digital trends, with brands leveraging omnichannel strategies to maximize reach.
Report Coverage:
The research report offers an in-depth analysis based on By Form, By Application / Product Category, By Distribution Channel, By End User and By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Seasonal demand is expected to intensify, expanding product launches beyond traditional autumn months.
- Innovation in plant-based and dairy-free formats will broaden consumer reach.
- Retailers will adopt data-driven inventory planning to optimize seasonal performance.
- Expansion into international markets will drive new growth opportunities.
- Premiumization trends will support higher price points and gourmet product lines.
- Cross-category integration into beauty, wellness, and home fragrance will diversify offerings.
- Social media influence and seasonal marketing will continue to fuel consumer engagement.
- Clean-label and organic formulations will gain traction with health-conscious buyers.
- E-commerce and direct-to-consumer sales will rise as seasonal preferences shift online.
- Collaboration between brands and influencers will shape limited-edition strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Pumpkin spice products market?
What are the key segments within the Pumpkin spice products market?
What are some challenges faced by the Pumpkin spice products market?
Who are the major players in the Pumpkin spice products market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Pumpkin Spice Products Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Pumpkin Spice Products Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 998 million → 2032: USD 2,170.6 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Pumpkin Spice Products Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Pumpkin Spice Products Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Pumpkin Spice Products Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Pumpkin Spice Products Market Drivers
- 3.3 Pumpkin Spice Products Market Restraints & Challenges
- 3.4 Pumpkin Spice Products Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Pumpkin Spice Products Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Pumpkin Spice Products Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Pumpkin Spice Products category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Pumpkin Spice Products Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Pumpkin Spice Products Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Pumpkin Spice Products. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Pumpkin Spice Products Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Pumpkin Spice Products Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Pumpkin Spice Products Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Pumpkin Spice Products (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Pumpkin Spice Products
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Pumpkin Spice Products Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Pumpkin Spice Products Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Pumpkin Spice Products Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Pumpkin Spice Products Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Pumpkin Spice Products Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Pumpkin Spice Products Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Pumpkin Spice Products Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Pumpkin Spice Products Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
